
Did we go backwards again?
Yes, probably.
We'll find out for sure whether the New Zealand economy recorded its fifth quarterly contraction out of the last eight when September quarter gross domestic product (GDP) figures are released on Thursday, December 19.
The Reserve Bank (RBNZ) has forecast a 0.2% drop.
It had seemed there was broad agreement among bank economists that 0.2% was about right. But minds have been changing as some of the 'partial' economic indicators for the third quarter have been released. Manufacturing figures appear to have turned out far softer than expected.
At the time I started writing this, I had just two of the big bank economists' previews in front of me. ANZ and Westpac are both picking a 0.4% fall.
As is frequently mentioned, there's a fair bit of a lag on our GDP data, given that we'll see what happened in the September quarter just 12 days before the December quarter ends.
So, it's all a bit historic. But, as ever, we'll be looking for clues as to how the economy might have been faring subsequently.
And there are signs the worst is over. The RBNZ thinks so, and reckons the December quarter will see us record 0.3% growth.
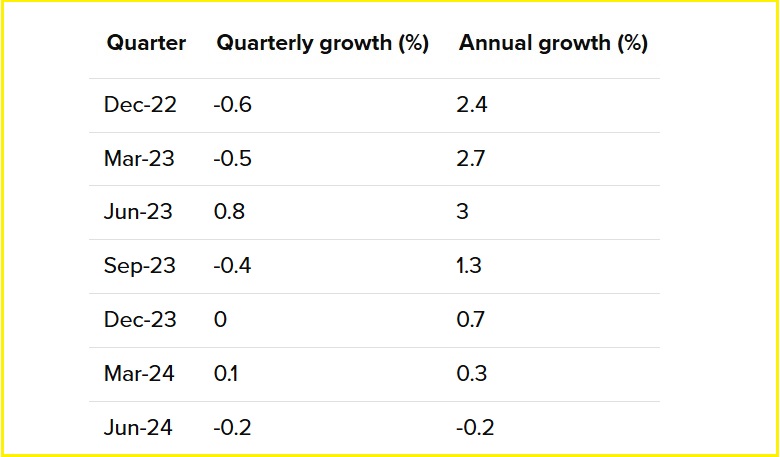
However, assuming a drop in GDP for the September quarter is confirmed, it will mean we've had two consecutive quarters of shrinkage. There was a 0.2% drop in the June quarter.
This means by 'technical' definition another recession.
Really, however, we've been in a kind of rolling recession since the December quarter of 2022 as the below table shows.
These figures have been the product of the RBNZ's wave of Official Cash Rate (OCR) hikes between 2021 and 2023 that saw the OCR pumped up all the way from just 0.25% to 5.50%.
The RBNZ began cutting in August, 2024 and now the rate is down to 4.25%.
On a per capita basis the GDP story has been even worse, remembering that we had a massive inbound migration boom following the pandemic.
Many more hands actually produced less. In the seven quarters to June, per capita GDP fell 4.6%, which is a bigger per capita decline than we had after the Global Financial Crisis.
Revisions will cloud the picture
However, we do need to mention the forthcoming September quarter GDP release will include extensive revisions to prior data.
We'll have to fully unpack all that after we've seen the detail and had it explained, but Statistics NZ is indicating annual GDP growth for the year to March 2023 will be revised up from 2.7% to 3.5%, while the figures for the year to March 2024 will go up from 0.3% to 1.4%.
Presumably the recent past economic performance may therefore not look quite as dire as has appeared. But we will have to wait and see for the detail.
So, that's the previous data. What are we expecting for the September quarter figures?
Well, as mentioned further up there has been a drip feed of 'partial' GDP indicators.
Retail sales volumes fell on a seasonally adjusted basis by 0.1% in the September quarter. That's better than the 1.2% drop in the June quarter, but trading conditions are undoubtedly still very difficult. Actual sales volumes in the September quarter were 2.5% lower than for September quarter 2023.
The volume of building work put in place fell by 3.2%, which was a bigger fall than expected. Residential building work fell by 3.5% to its lowest level in four years.
The volume of total manufacturing sales fell by a seasonally adjusted 1.2% after a surprising 0.3% rise (and that's now been revised down from the originally stated 0.6%) in the June quarter. Wholesale trade sales fell on a seasonally adjusted basis by 1.2% in the September quarter after an downwardly revised 1.3% in the June quarter.
So, what does it all mean?
Well, it certainly suggests GDP declined in the September quarter. At this point, I will leave you with the economists and their views.
ANZ economist Henry Russell and senior economist Miles Workman say in their preview that despite their forecast for GDP (-0.4%) being marginally weaker than the RBNZ’s November Monetary Policy Statement forecast (-0.2%), they don’t anticipate the third-quarter figures will alter the near-term path for monetary policy.
They say RBNZ senior policymakers have already provided guidance that a 50 basis point cut to the OCR is likely at the next review in February, and the bar for a 75bp cut "is likely to be very high".
"The Q3 GDP data (already three months old) is very much a look in the rear-view mirror, and the focus has now turned to gauging the economy’s responsiveness to monetary easing."
"On that front, high-frequency indicators signal the economy is turning a corner, but that will take time to be reflected in hard economic outcomes."
"The stark divergence between where the economy has been, and where forward indicators signal that it is heading, is likely to temper the attention the RBNZ pays to a weaker-than- expected Q3 GDP outcome," Russell and Workman say.
Paving the way for recovery
They say lower interest rates and easing credit conditions are paving the way for an economic recovery. And high-frequency indicators are already signalling the economy is responding, with confidence lifting, the housing market showing signs of life, and activity indicators having bounced off their June lows.
"This recession was caused by high interest rates, so lower rates are likely to be an effective cure, but not an instant one, and there remains considerable uncertainty surrounding the pace of the recovery," the ANZ economists say.
"Our assessment of near-term growth prospects will be informed by how extensive the slowdown in the economy has become outside of the most interest rate-sensitive industries."
"If weakness in [the] GDP release is concentrated in the most interest-rate sensitive sectors, namely construction, manufacturing and retail trade, a stronger rebound in activity could be on the cards, as these industries tend to be the first to respond to falling interest rates."
"If, however, underlying momentum in services industries has weakened more than expected, that could have larger implications for the near-term path for growth, given services industries tend to be a slower ship to turn," Russell and Workman say.
In his latest Eco Pulse publication, BNZ chief economist Mike Jones has posed the question of whether the economy is responding to interest rate reductions.
"...It’s clear that the economic response to rate cuts to date has been small and reasonably tentative," he says.
"That’s not hugely surprising given the OCR is still at restrictive levels overall and it takes a while for cuts to work their way into the interest rates that people pay and receive."
But he says it’s important to note that lower interest payments are not the only way less restrictive monetary policy works. Cutting the cash rate and saying there’s more to come can also lower the exchange rate, boost asset prices, and lift confidence.
Providing an extra leg-up
"These impacts tend to be more immediate and we’re seeing elements of all of them in play. Most of the NZ dollar’s recent decline is linked to the strength of the US dollar post the return of Donald Trump. But the NZD has still underperformed all G10 currencies over the five months since the RBNZ first flagged cash rate cuts were on the cards in July. If the lower NZD/USD is sustained, and our forecasts suggest it will be, it will provide an extra leg-up for export returns that are already starting to look healthy in some sectors (e.g. dairy and horticulture)."
Jones says evidence of a boost for asset prices, and any associated ‘wealth effect’, is mixed.
"The NZ share market is rising but there is a strong offshore updraft to this. Local house prices are not rising but our view is that lower interest rates: a) likely prevented a deeper correction this year, and b) will help drive an upturn in house prices next year."
He says confidence "has most definitely perked up". An expectation of lower interest rates has "supercharged" particularly business confidence recently. Firms’ expectations of their own output are at the highest level since 2014. Historically there’s a strong directional (but far from perfect) link between firms’ expectations of their own business activity and what gets delivered.
"So, while a more confident populace does not mean the recovery is assured, it does provide a rung of support to our forecasts for economic growth to pick-up to around 3% next year."
*This article was first published in our email for paying subscribers first thing Friday morning. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.