
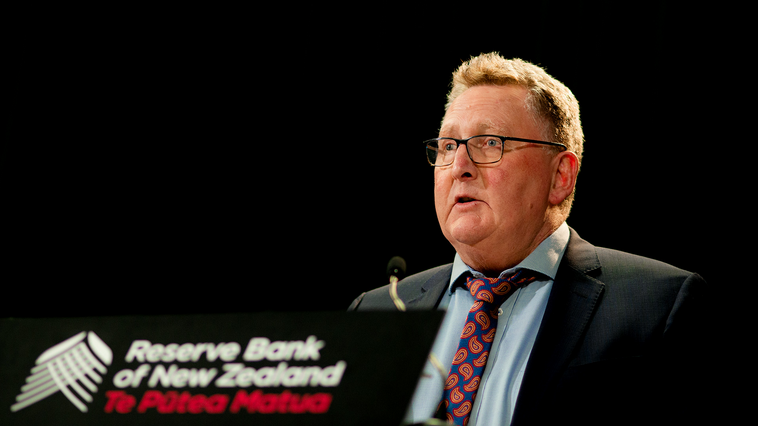
Reserve Bank Governor Adrian Orr is set to give a speech ahead of the RBNZ's first Official Cash Rate decision of the year in which he will discuss why the RBNZ "continues to believe that a flexible inflation target centred on 2% still makes sense".
Orr is set to speak at the high powered 2024 New Zealand Economics Forum at the University of Waikato on Friday, February 16.
He has previously appeared at these events, so, there's nothing surprising, as such, in his appearance this year.
However, last year the subject matter of his speech was on the rather more generic 'promoting economic wellbeing' topic, while this year's topic appears far more specific - and also potentially market moving.
Orr's decision to, it appears, defend the RBNZ's specific targeting of 2% inflation comes at a time when there's widespread expectation of interest rate cuts soon. And it also comes at a time of discussion around the RBNZ's inflation targets and whether they should be reviewed.
The RBNZ has a target of maintaining inflation within a 1% to 3% band, but with a focus on keeping future inflation "near the 2% midpoint".
Inflation has now been outside of the RBNZ's 1% to 3% range for over two and a half years and the RBNZ's not forecasting inflation to return within that band till the September quarter of this year. However, it doesn't forecast that inflation will actually hit the 2% midpoint of the inflation target till September 2025 - in more than a year-and-a-half's time.
Annual inflation, as measured by the Consumers Price Index (CPI) was 4.7% at the December quarter, down from 5.6% in the September 2023 quarter.
The RBNZ has strongly driven up interest rates in the fight against inflation, pushing the Official Cash Rate up all the way from just 0.25% as of the start of October 2021 to the current 5.5%.
With inflation now coming down quickly, financial markets are anticipating falls in the OCR sooner rather than later, with three cuts to the OCR currently being priced in by the markets this year.
However, in a speech given online this week RBNZ chief economist Paul Conway - breaking the RBNZ's three month summer 'silence' between the last OCR announcement of 2023 and the first of 2024 on February 28 - pushed back against such expectations.
After Conway's speech, BNZ head of research Stephen Toplis questioned the RBNZ's desire to get inflation to the 2% midpoint of the target.
"...We would like to think that a better approach would be to simply be less dogmatic about getting inflation to the midpoint of the target band. Alan Bollard, when he was central bank governor was much more relaxed about using the full width of the band. This didn’t seem to cause too much problem," he said.
"And, anyway, even were we to be dogmatic about targeting a mid-point, we have yet to hear a good argument as to why we should be confident that 2.0% is the optimal number. As a point of contrast, if inflation was forecast to be 2.25% in both New Zealand and Australia the Reserve Bank of New Zealand would be running tight monetary policy and the Reserve Bank of Australia loose. Which [central] bank would be right?"
In a note advising of Orr's February 16 speech, the RBNZ said that in his address, Orr "will speak about the changing drivers of inflation over the past couple of years and the shift from transitory to more stubborn underlying inflation. He will also discuss why – despite these challenging years – the Reserve Bank continues to believe that a flexible inflation target centred on 2% still makes sense".
"Orr will also talk about the year ahead for the Reserve Bank. As a full-service central bank, the RBNZ has a wide mandate that spans monetary policy, financial stability, cash operations, and financial markets infrastructure. Ensuring we achieve our mandate is important for New Zealand’s long-term prosperity and economic wellbeing, and we have a full agenda ahead of us to ensure we do so."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.