
Longer fixed term mortgage rates are already reflecting expected Official Cash Rate (OCR) reductions - but shorter term mortgage rates have more 'downside' potential, BNZ economists believe.
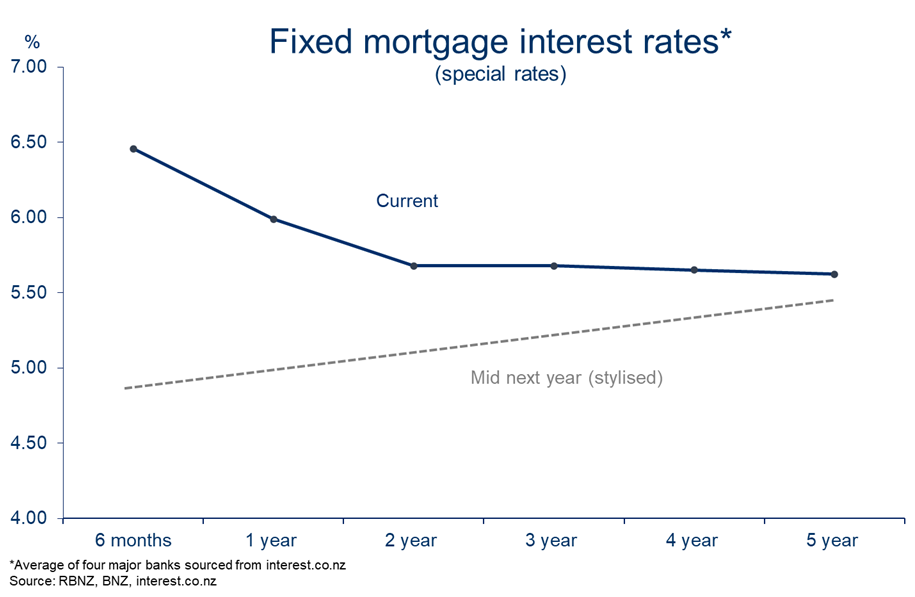
In his latest Eco Pulse publication, BNZ chief economist Mike Jones says one thing that was notable in last week’s round of mortgage rate cuts was the larger (20-25 basis points) declines at the short end of the interest rate 'curve' compared with the modest 5bps or so of cuts at terms of two years or more.
"We think that might be a taste of things to come with those lower, longer-rates already factoring in a schedule of OCR cuts similar to our own forecasts," he said.
Shorter-term rates, by contrast, "have more downside" as they follow the OCR down.
"We don’t forecast the full range of mortgage terms. But the chart [below] provides an indicative sense of how the mortgage curve could look by mid next-year, based on our OCR and wholesale interest rate forecasts," Jones said.
Jones notes that since the start of 2023, mortgage fixers have been "busily shortening fixing terms" in anticipation of lower interest rates.
"In August (the latest month we have data for), a record 86% of new mortgage lending by value was written for terms of 12 months or less.
"This preference for shorter terms will probably stick around in the short-term but we wouldn’t be surprised to see more of an inclination to look at longer terms as we head towards the end of the year," Jone said.
Following a 50 bps cut by the RBNZ earlier this month, the OCR sits on 4.75%.
BNZ economists are forecasting another 50 bps cut in the review on November 27, the final review of 2024, with 25bps cuts at each review next year taking the cash rate to a low point of 2.75% by the fourth quarter of 2025.
Jones says the chances of a "sudden surge" in the housing market throwing the RBNZ off its rate cutting stride appear low.
"The market is still shuffling sideways. Recent and expected mortgage rate cuts have buoyed sentiment and interest, but not so much the hard numbers just yet."
Jones says that for house prices to start rising in a sustained fashion the first thing that needs to happen is the excess supply currently "overhanging" the market needs to be worked off.
"There hasn’t been a whole lot of progress in this regard, as the sales/listing ratio in the chart [below] shows.
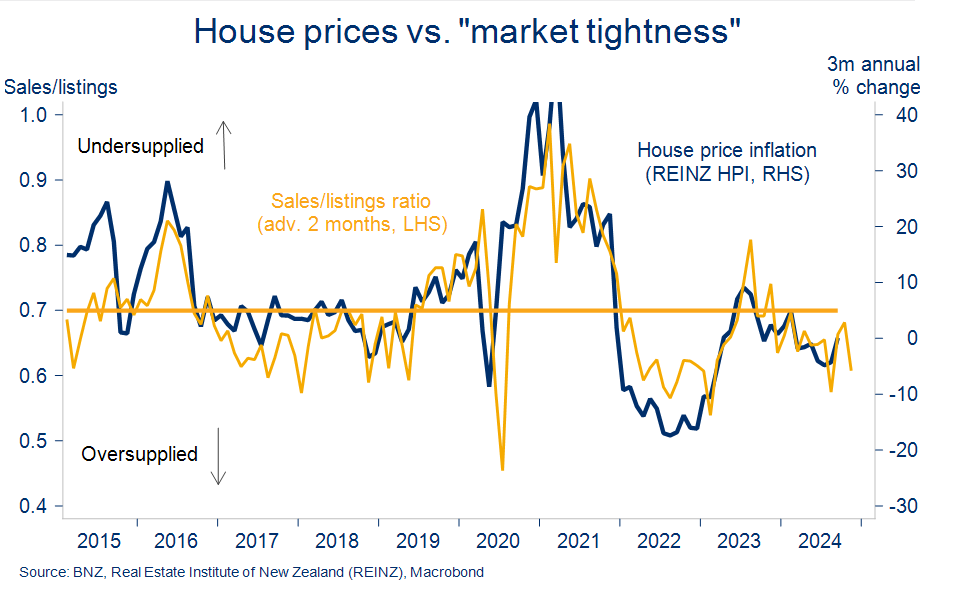
"This being so we remain comfortable with our view for a broadly flat house price performance over the remainder of 2024.
"We continue to expect more of a lift as we move into next year. Our forecasts remain consistent with a 7% increase in house prices through calendar 2025.
"It sounds bullish but it’s almost bang on the long-run average. Note too that if it’s even ballpark correct, house prices would still end 2025 around 10% below the 2021 peak. Compare that to Australia where prices surpassed the previous (2022) peak late last year," Jones said.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.