
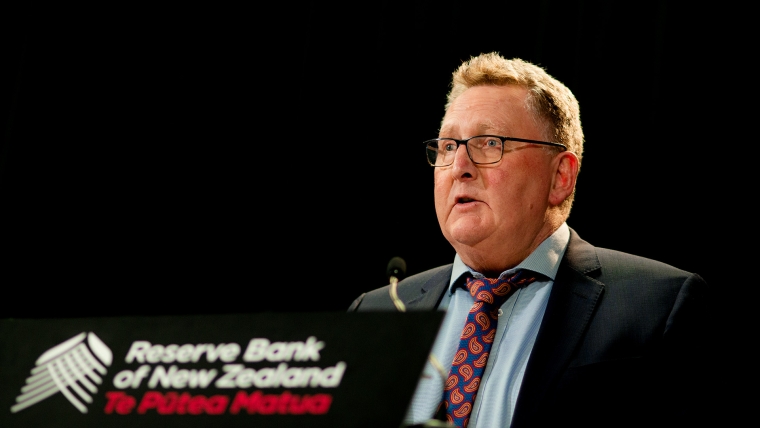
The Reserve Bank believes it has raised interest rates enough to bring inflation back into its target band by mid-2024, with help from migration and government fiscal policy.
There was no announcement of ‘mission accomplished’ from the central bank, but the message was that current monetary policy settings are enough to calm inflation.
In its first ever divided decision, the banks’ Monetary Policy Committee voted to lift the Official Cash Rate (OCR) 25 basis points to 5.5% in a five-to-two vote on Wednesday.
The two members who disagreed voted in favour of holding the benchmark rate at 5.25% while waiting to see how economic conditions played out over the next couple of months.
A lift of 50 basis points—which market traders had partly priced in—wasn’t even entertained by the committee.
The bellwether two-year swap rate dropped about 35 basis points after the decision, and the kiwi dollar fell almost 1.5% against the US dollar, dropping from 62.5 US cents to 61.7 US cents.
Markets moved, but Reserve Bank Governor Adrian Orr said the decision should have no impact whatsoever on mortgage and deposit rates.
“What we are doing today is what we have been foreshadowing for quite some time and, if anything, that will be supportive of current mortgage interest rates,” he said.
A stab in the dark
Despite the foreshadowing, most economists and market traders predicted Wednesday’s decision incorrectly. They thought an inflationary budget and soaring migration would force rates higher, but the Reserve Bank disagreed.
It said Budget 2023 was less contractionary than had been expected back in February, but was restrained enough to help push back on inflation.
“Fiscal policy is projected to add to demand over the 2023/24 fiscal year, then dampen demand in subsequent years. Overall, fiscal policy will be contractionary on demand over the projection horizon”.
Orr said the overall effect was the “only relevant thing” for monetary policy and he wasn’t concerned by the short-term impact on demand.
“[Fiscal policy] is being more of a friend than foe to monetary policy at this point in time,” he told reporters on Wednesday.
He made similar remarks about the sudden pick-up in net migration numbers, which pushed Westpac NZ economists to upgrade their OCR forecast to 6% earlier this month.
Several other economists followed suit and markets began to be re-priced for a higher peak in the benchmark rate. The two-year swap rate had climbed all the way to 6% by Wednesday morning.
But Orr and the Monetary Policy Committee took the view that migration was likely to help, rather than hinder, its efforts to bring supply and demand back
“The increase in net inward migration is providing some relief in a very tight labour market, but the net impact on demand – including for housing – is uncertain, as is the impact on inflationary pressure,” it said.
Orr said those migrants who had already arrived had helped to fill job vacancies and alleviate the worker shortage.
“The number one capacity constraint in the economy has been people. Immigration has certainly eased that,” he said.
This was one issue which divided the committee with some members concerned that strong migration inflows could continue long term, which would boost spending and inflation.
Orr told reporters that almost two-thirds of the migration boom had already occurred and the bank expected future inflows to trend back toward the pre-Covid average.
No recession required
Westpac’s chief economist, Kelly Eckhold said the Reserve Bank had upgraded its view on how much output the economy could potentially generate thanks to the influx of workers.
“Implicitly, migration is adding to the economy’s capacity in tandem with demand on resources, allowing the economy to grow more strongly without adding to inflation pressures,” he said in a note.
ANZ chief economist Sharon Zollner said the Reserve Bank no longer seems to believe that a blatant economic slowdown was necessary in order to get inflation down.
The forecasts in the Monetary Policy Statement feature “the tiniest of recessions” with gross domestic product declining 0.2% in the second quarter and 0.1% in the third.
Orr said this was a “short shallow period of flat, if not marginally negative, economic growth”, with the forecast decline well within the margin of error — a recession so small it may not happen.
Economists were a little more cautious about the possibility that interest rates had peaked for the cycle.
ANZ’s Zollner said it was worth remembering that the RBNZ paused twice during its hiking cycle in 2007 and 2008, once for six months and once for more than a year.
“A pause is not necessarily a peak, though the market will undoubtedly take it that way,” she said.
The central bank could be forced to raise rates if house prices started to climb, migration stayed high, or unemployment stays stuck at 3.4%.
Cuts could come sooner than planned (late-2024) if migration takes the heat out of the labour market too quickly, the US debt ceiling crisis causes disorder, or if inflation suddenly falls.
BNZ’s head of research, Stephen Toplis said there was a clear message that the RBNZ does not expect interest rates to fall any time soon.
The cash rate forecast provided by the central bank showed the first cut in the fourth quarter of 2024 and gradually falling to 3.25% by June 2026.
Toplis said the monetary policy committee was likely to cut rates sooner than this, probably in May 2024 — exactly one year's time.
“With 29% of the Committee already of the view the cash rate should not be 5.25% at this juncture, the bias has been clearly established,” he said.
However, assistant governor Karen Silk said the committee had unanimously agreed to the long-term OCR track and warned the market had a history of miscalculating the bank's decisions.
“The market will do what the market will do, that is a reflection of our position,” she said.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.