
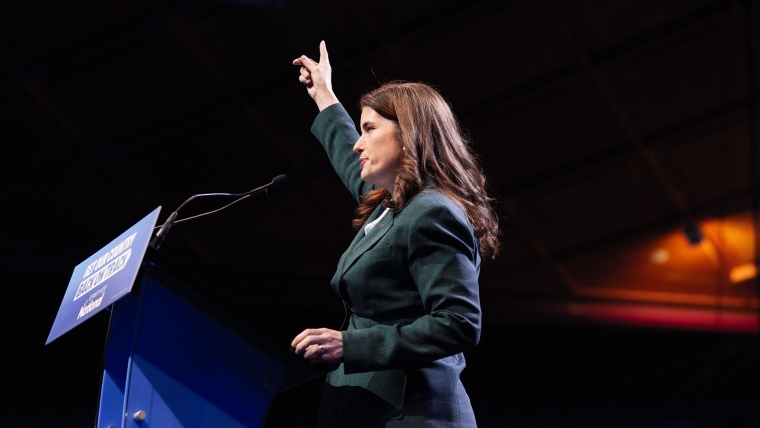
Finance Minister Nicola Willis says the Treasury has warned her that economic growth is likely to be “significantly slower” than previously thought.
Willis will release the Coalition Government’s Budget Policy Statement on March 27, alongside updated forecasts for the economy.
“The numbers haven’t been finalised, but I know enough to say they won’t make happy reading,” she told the Auckland Business Chamber in a speech.
The Treasury has become “even more pessimistic about the growth outlook” since it provided its half-year update in December, prior to Statistics NZ’s GDP revisions before Christmas.
However, forecasts released by the Reserve Bank in February do not predict a more serious slowdown relative to their November numbers — just a lower starting point.
Treasury’s forecast for 2024 growth was more optimistic than the central bank’s prediction and so there may be room for revision.
Regardless, Willis has been signalling she may not be able to return the Crown accounts to surplus by the end of the Parliamentary term as originally promised.
The Coalition Government has already been searching for extra cost savings or revenue measures to help protect its bottom line and possibly make up for lower tax revenue.
Some policies have been tweaked in the past weeks to make them a little bit cheaper.
Interest deductibility will be phased in slower than planned and a commitment to not increase fuel taxes will be partly offset by higher car registration fees.
Willis said she was conscious of speculation about how lower economic growth might impact the upcoming Budget and outlined three possible ways the Government could respond.
One approach would be to walk away from “major commitments” such as income tax cuts and big investments. Another, would be to allow the Crown accounts to weaken further.
Neither of these were options she was willing to entertain, at least publicly.
Instead, the Finance Minister said she would stick to the coalition's spending commitments while cutting what the Government deems to be wasteful spending further and pushing through economic growth policies.
“With low-growth forecasts bearing down on New Zealand, now, more than ever, we must double-down on the drive for real economic growth,” she said.
“We must pull out every stop to beat the gloomy forecasts and get this country growing faster, more productively and more sustainably”.
In a recent interview with Stuff, Associate Finance Minister David Seymour said the Coalition was not considering walking back its tax cuts or borrowing more money to fund them.
The economy was softer than some had hoped, which would mean lower tax revenue, while rising unemployment and higher interest rates added extra costs for the Government.
However, those headwinds weren’t expected to trigger a clause in the coalition agreement which allows the fiscal plan to be amended in response to changed circumstances.
“Put it this way, I’m one of the Budget ministers and there is no talk of not delivering those tax cuts this year,” Seymour said.
The Government would also not be borrowing “more than was otherwise expected” in order to fund the tax cuts. This can only be possible if more revenue or cuts can be found elsewhere.
Tax troubles
The draft fiscal plan faces pressure on all fronts. Revenue may be lower, costs could be higher, and already some key numbers backing up its income tax cuts are coming up short.
National was warned during the election campaign that its tax plan would not work out to be fiscally neutral and now official estimates are confirming that prediction.
One of the biggest earners, a tax on foreign home buyers, never made it past the coalition negotiations. That immediately left the coalition short almost $3 billion across the forecast.
The Climate Change Commission has cast doubt on the $2.3 billion the Government hoped to earn from the Emission Trading Scheme (ETS), with advice to halve the number of units ASAP.
It will be very interesting to see how Treasury forecasts future revenue from the scheme in light of that advice, when a decision on unit settings isn’t expected until after the Budget.
The cost of restoring interest deductibility has increased by almost $800 million since the election campaign due to higher mortgage rates. It is now estimated to be $2.9 billion.
Treasury said National underestimated the revenue that would earned by be removing commercial building depreciation. It thinks it will be $200 million higher, at $2.3 billion over four years.
But the proposed online gambling tax may only raise a fraction of the $716 million baked into National’s fiscal plan. The Treasury said it would bring in just $150 million.
Keeping Labour’s so-called “App Tax” saves the Coalition $206 million relative to the fiscal plan and moving the Brightline tax back to two years was correctly estimated at $202 million.
But the end result of all these changes is that the Back Pocket Boost tax plan will need an additional $3.8 billion in funding over the next four years — assuming ETS revenue holds.
That’s a far cry from the promise that it would be fiscally neutral and the shortfall can only be made up with new taxes, spending cuts, or from small unallocated budget allowances.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.