
There are tentative signs that home loan affordability has turned a corner for aspiring first home buyers, bringing the prospect of owning their own home slightly closer.
The latest improvement comes after many years of worsening affordability for first home buyers followed by a brief period of relative stability, and may mark a turning point in the market.
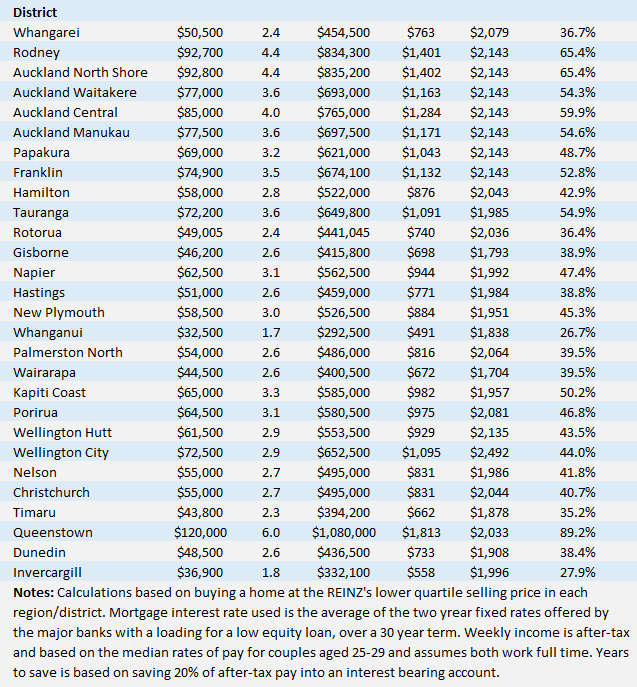
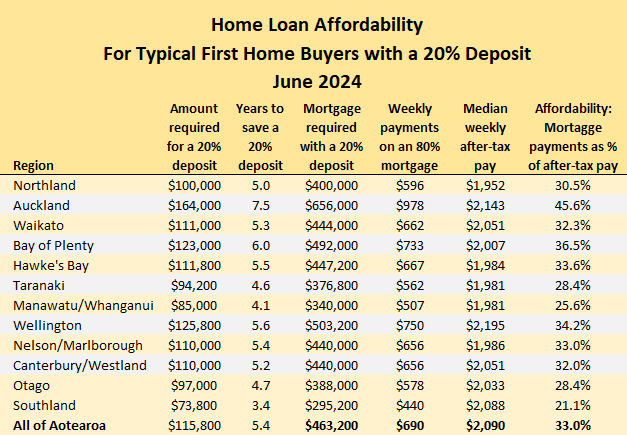
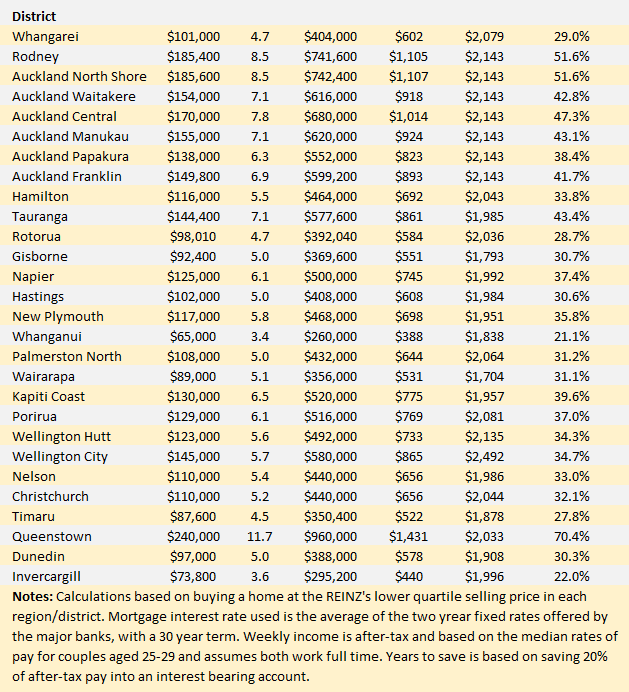
Interest.co.nz tracks the mortgage payments for a home purchased at the Real Estate Institute of New Zealand's lower quartile selling price in each major urban district, and compares that to the median after-tax wages of 25-29 year old couples.
Mortgage payments are considered unaffordable if they take up more than 40% of their after-tax pay.
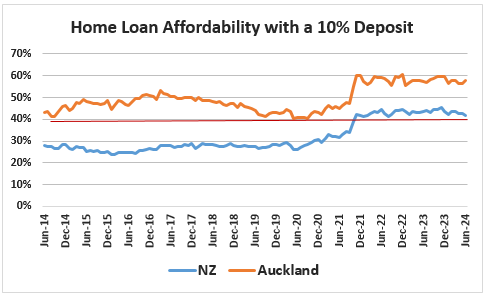
That latest figures show the percentage of typical first home buyers' take home home pay that would be taken up by mortgage payments on a home purchased at the national lower quartile price with a 10% deposit, has declined for the last three consecutive months, from 43.8% in March to 41.9% in June.
That means home ownership for typical first home buyers has gone from being solidly in unaffordable territory at the start of the year to just marginally unaffordable in June.
If the current trend continues, then affordability at the national level would likely dip under the 40% threshold in the fourth quarter of this year.
If that happens, it would the first time that housing has been considered affordable for first home buyers at the national level since October 2021.
The recent improvement in affordability has been caused by a fortuitous combination of several factors:
- Small falls in REINZ's lower quartile selling price which has declined for three consecutive months, from $600,000 in March to $579,000 in June.
- Small falls in mortgage interest rates, with the average of the two year fixed rates charged by the major banks declining for seven months, from 7.04% in November last year to 6.72% in June this year.
- The drop in interest rates combined with falling prices has seen the mortgage payments on a lower quartile-priced home purchased with a 10% deposit, steadily decline from $935 a week in November last year to $875 a week in June this year, providing a saving of $60 a week in mortgage payments. If the same property was purchased with a 20% deposit, the mortgage payments would have declined from $740 to $690 over the same period, giving a saving of $50 a week.
- Ongoing increases in wages, although these have slowed considerably this year after substantial growth last year. Interest.co.nz estimates the after-tax pay for couples aged 25-29 and both working full time, has increased from $2078 a week in January this year to $2090 in June, giving them an extra $12 a week.
However the latest improvements in affordability should be regarded as a small step in the right direction rather than a great leap forward in home ownership measures.
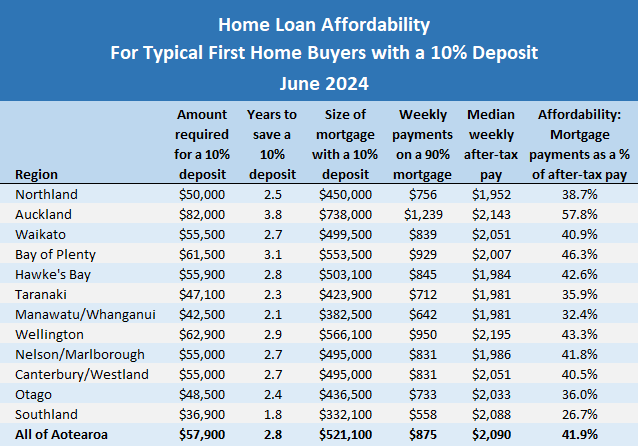
Housing is still severely unaffordable for prospective first home buyers on average incomes in Auckland and is also particularly difficult for them in Bay of Plenty, Hawke's Bay and Wellington.
It would take a sustained decline in mortgage interest rates and house prices at the bottom of the market and an ongoing rise in wages to make home ownership an affordable option for typical first home buyers in those regions.
The tables below give the main affordability measures in all of the main urban areas throughout the country.
- The comment stream on this story is now closed.
*This article was first published in our email for paying subscribers early on Friday morning. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.