
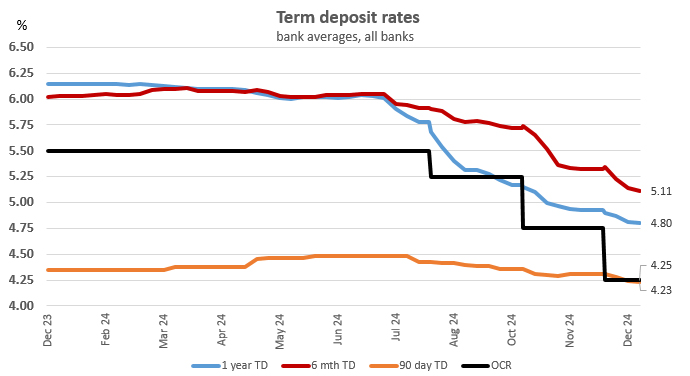
2024 has been a year when savers lost some of the big gains they got in 2023.
Those 2023 gains brought back fond memories of the very high rates savers enjoyed just prior to the GFC.
After the GFC, things fell apart somewhat and they had to suffer a long period of below-inflation yields. So the 2023 rise was a welcome development.
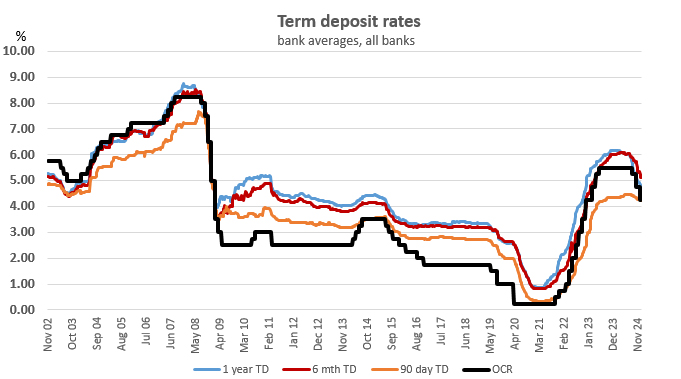
But 2024 was a roll-back year. Not all the way to the pandemic depths, but enough to grab some attention, and enough to wonder about what 2025 might bring.
Of course, the average shift varied between deposit-taker institutions.
The following table tracks the net change from where we started the year, to where we finished.
And we have now included the registered Non-Bank-Deposit Takers. And that is because there is less than 200 days until it will seem like they can front it with the banks, because they will be in the Deposit Compensation Scheme, which guarantees up to $100,000 won't be lost in the event of an institution failure. The taxpayer will make the depositor good.
Readers should note that the RBNZ will be charging institutions a fee for that protection. But the fee will be entirely risk-based - that is based on each institution's risk profile. A key risk they will be looking at is liquidity risk. The more risk, the higher the fee, and that may well impact Non-Bank Deposit Takers harder than banks. In turn, that will likely mean they will be unable to offer interest rate returns to savers in the way they did in 2024. Only time will tell how these factors play out for each institution. And there could well be risk differences between community-based institutions and finance companies.
| January 2024 | December 2024 | |||||
| 3 mth | 6 mth | 1 year | 3 mth | 6 mth | 1 year | |
| % | % | % | % | % | % | |
| Main banks | ||||||
| ANZ | 4.20 | 6.00 | 6.10 | 4.15 | 5.05 | 4.75 |
| ASB | 4.20 | 6.00 | 6.10 | 4.15 | 5.05 | 4.75 |
| BNZ | 4.20 | 6.00 | 6.10 | 4.10 | 5.10 | 4.75 |
| Kiwibank | 4.20 | 6.05 | 6.15 | 4.20 | 5.10 | 4.80 |
| Westpac | 4.20 | 6.00 | 6.10 | 4.30 | 5.05 | 4.75 |
| Challenger banks | ||||||
| Bank of China | 4.90 | 6.00 | 6.15 | 4.50 | 5.35 | 5.00 |
| China Construction Bank | 4.70 | 5.85 | 6.00 | 4.30 | 4.95 | 4.80 |
| Cooperative Bank | 4.20 | 6.10 | 6.20 | 4.15 | 5.15 | 4.80 |
| Heartland Bank | 4.25 | 6.05 | 6.30 | 4.35 | 5.15 | 4.85 |
| ICBC | 4.90 | 6.00 | 6.15 | 4.50 | 5.35 | 4.95 |
| Rabobank | 5.05 | 6.15 | 6.30 | 4.35 | 5.10 | 4.80 |
| SBS Bank | 4.20 | 6.05 | 6.15 | 4.15 | 5.10 | 4.80 |
| TSB | 4.25 | 5.90 | 6.00 | 4.15 | 5.05 | 4.75 |
| Non-Bank Deposit Takers | ||||||
| Christian Savings | 4.40 | 6.05 | 6.15 | 4.40 | 5.15 | 4.85 |
| Finance Direct | 3.95 | 6.50 | 3.95 | 6.50 | ||
| First Credit Union | 4.75 | 5.75 | 6.50 | 4.25 | 5.45 | 4.90 |
| General Finance | 7.00 | 7.50 | 4.20 | 6.30 | 6.50 | |
| Gold Band Finance | 4.00 | 6.75 | 3.75 | 6.40 | ||
| Heretaunga Building Society | 4.35 | 6.10 | 6.25 | 4.30 | 5.15 | 4.85 |
| Liberty Financial | 4.75 | 6.60 | 7.10 | 4.25 | 5.85 | 5.50 |
| Mutual Credit Finance | 7.00 | 6.50 | ||||
| Nelson Building Society | 4.20 | 6.00 | 6.10 | 3.90 | 4.85 | 4.55 |
| Police Credit Union | 4.10 | 5.95 | 6.00 | 4.10 | 5.05 | 4.75 |
| UnityMoney | 4.20 | 6.00 | 6.00 | 4.15 | 5.00 | 4.55 |
| Wairarapa Building Society | 4.20 | 6.00 | 6.25 | 4.05 | 4.50 | 4.75 |
| Xceda Finance | 6.85 | 7.50 | 6.50 | 6.40 | ||
So then the question becomes, what will happen in 2025?
Regular readers will know that we don't predict or forecast future rate levels. But the financial markets do, by setting forward pricing. This isn't infallible, and as each circumstance changes, that pricing in adjusted (as it should be). In 2024 there were many adjustments, so what these markets priced for 2025 at the start of 2024 turned out to be quite different to what they priced at the end. No-one should be surprised. That is just how financial market pricing works, and always has done.
This is what is priced in as at December 20, 2024, for the year ahead when looking at the OCR.
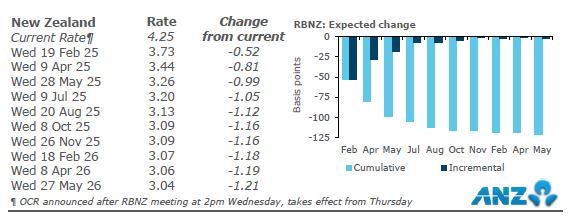
We can add that to our 2024 charting. That might help you think about what could be in store for term deposit rates in 2025. Stay short? or go long from here? Nobody knows the future, especially spruikers pitching their products. Your judgment will be as good as anyone's, and probably better than anyone conflicted by salesmanship. If it seems to good to be true, it almost certainly is.
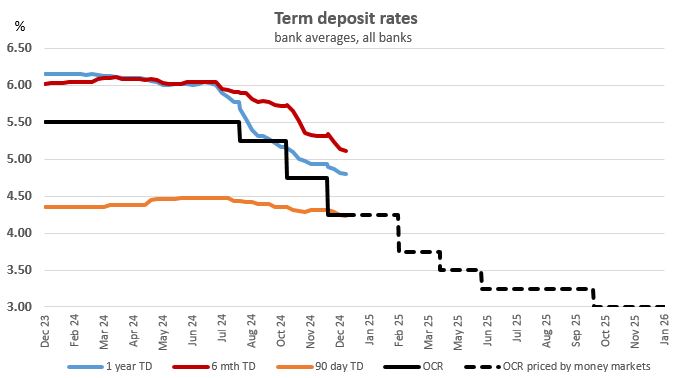
The above chart has been updated/corrected.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.