
Okay, THIS one is BIG.
Look, you might think we always say that. But this one IS REALLY BIG.
Statistics NZ releases the Consumers Price Index (CPI) inflation figures for the June quarter on Wednesday, July 17.
Why is this one in particular so important?
Well, it was always going to be hugely important, but the Reserve Bank (RBNZ) has actually upped the ante with some very unexpectedly 'dovish' remarks in its Official Cash Rate (OCR) review on July 10.
Financial markets never need encouragement to get ahead of the game and following the RBNZ comments there's been some aggressive moves in wholesale interest rates. At time of writing - and please, bear in mind this is a very movable feast - the financial markets were pricing in about a two-thirds chance of an OCR cut as soon as next month. An OCR cut in October is now fully priced in, while TWO cuts are now priced in for November.
I'm inclined to think that's all a little exuberant. But no doubt the rate cut buzz will only get louder if the inflation results this coming Wednesday are the 'right' ones.
So, what do we need to see? And where are the potential pitfalls?
We need to see meaningful falls in the inflation rate so that the Reserve Bank (RBNZ) can be confident inflation is under control and therefore can contemplate lowering interest rates.
This was always going to be the key quarter even before the RBNZ raised the stakes with its comments in the past week. This is when, I would argue, we can find out definitively if the inflation battle really is being won or not and therefore whether the current expectation of imminent falling interest rates is justified.
This quarter will either be the proof in the RBNZ's pudding - or it will be the bad egg that ruins the pudding.
The RBNZ is charged with maintaining inflation between 1% and 3%, with an explicit target of 2%. All is well and good well if inflation behaves. But It has most certainly not behaved; having now been above 3% for three years. Three years. That is a long, long time.
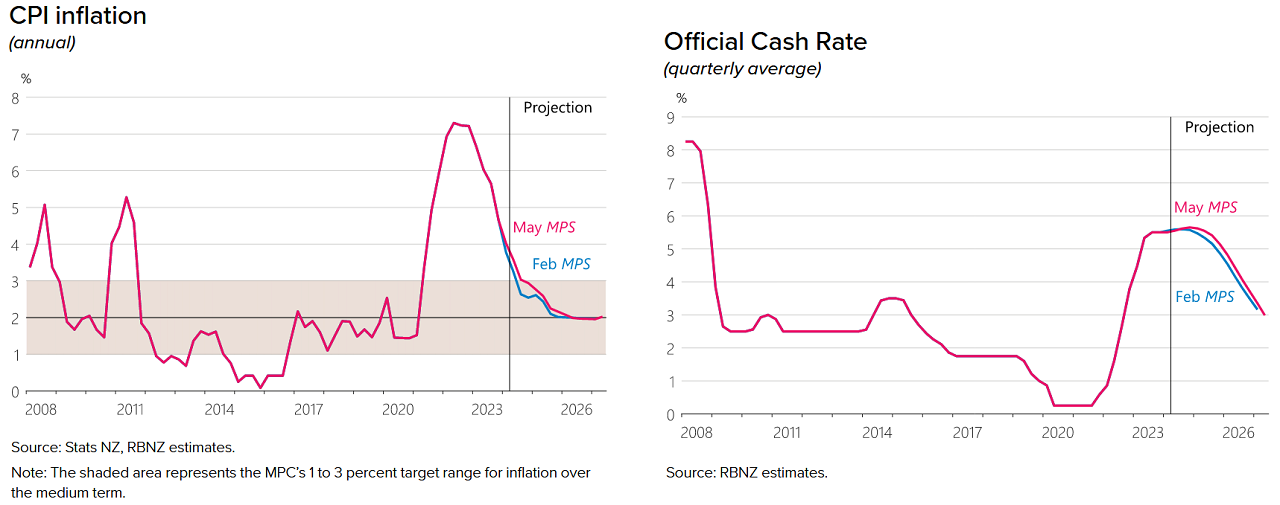
Everything got out of hand very quickly. As of March 2021 annual inflation was 1.5%. Twelve months later it was 6.9%. Aaaaarrrrggggh, is I believe, the word. The peak of 7.3% was in June 2022. The trip back down from the peak has been nothing like as fast as the ascent was. In March 2023 annual inflation was still at a very elevated 6.7%.
Now we are seeing real progress though. As of March 2024 the annual inflation rate was down to 4.0%. It's been expected to fall further in the June quarter. How much further it HAS fallen will be the big drama in the coming week.
Annual inflation rate down to 3.6%? Lower?
The RBNZ is forecasting that the annual inflation rate will have come down to 3.6%. But that is a forecast made in May prior to its more dovish OCR comments in the past week. I didn't have all the major bank economists' forecasts in front of me at time of writing, but Westpac has 3.5% and both ANZ and ASB reckon just 3.3% - which is interestingly what the inflation rate was back in June 2021 when it first broke out of the 1% to 3% range.
So, okay. That's great. We've just about fixed this thing! Bring on the interest rate cuts! Well...as the RBNZ has been saying itself, until certainly the last week - not so fast.
There's a few potential plot twists here. Inflation is measured in several ways. The point of saying that is: While the so-called 'headline' inflation figure might be looking good, there could be other inflation measures that are not.
Enter 'tradable' inflation and 'non-tradable' inflation. Very loosely the 'tradable' figure refers to 'imported' inflation - think things like petrol prices. 'Non-tradable' inflation is, again very loosely, domestically generated inflation - think things like new home building costs and rents.
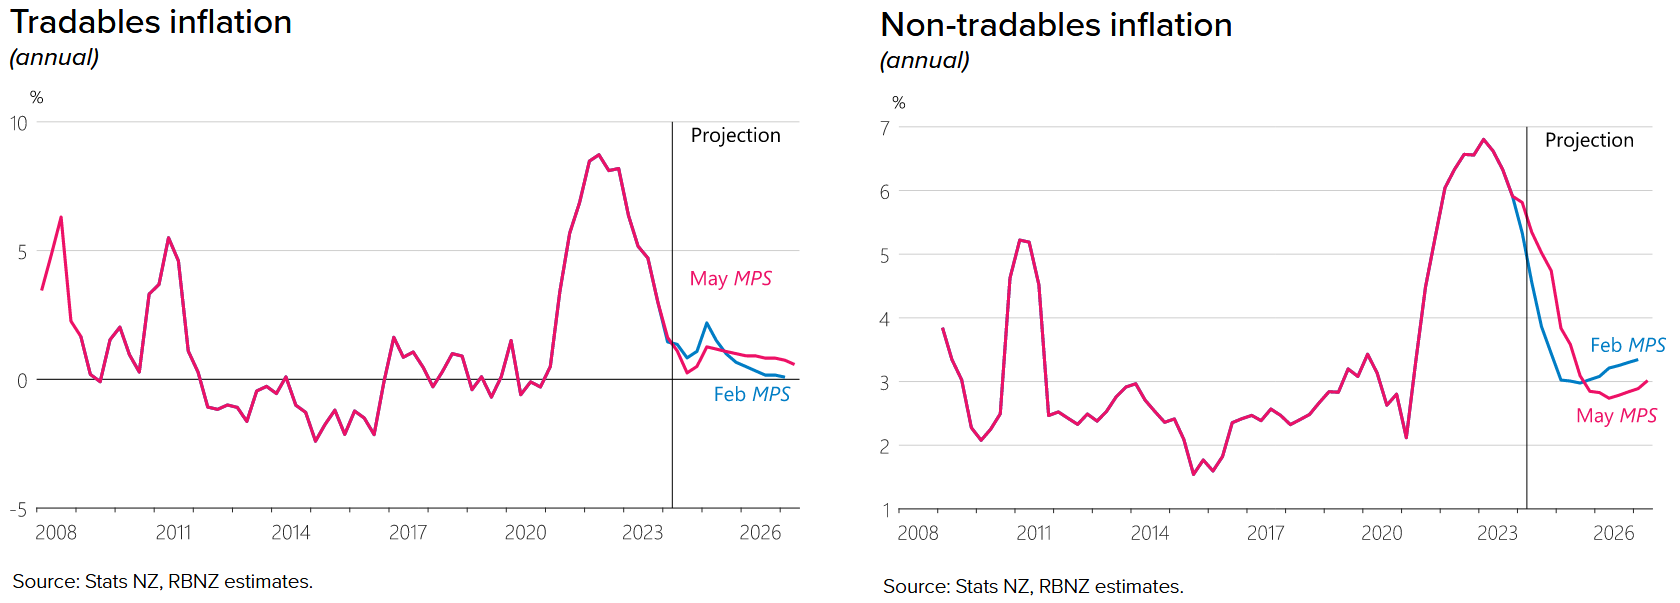
In very simplistic terms our post-pandemic inflation battle has actually been conducted in two parts. First we had to fight through incendiary levels of 'tradable' inflation, which peaked at an eye-watering 8.7% annual rate in June 2022.
More recently as global supply chains have been painstakingly unbroken again and various other things have come back into equilibrium, the tradable inflation has retreated like a fast-running ebb tide. As of the March quarter the annual tradable inflation figure was down to 1.6%. The RBNZ's forecasting the figure will be just 1.1% for the June quarter and there's some thoughts from economists it might even be lower than that, with petrol prices having dropped meaningfully recently. (All the graphs here come from RBNZ's May MPS).
And non-tradable inflation? Ah, well, you spotted it. There's the problem. Part two of the inflation fight. Non-tradable inflation.
After the first wave of imported inflation hit us, local NZ prices were put up across the board in response. And this domestic inflation has proven 'sticky' as the economists like to describe it. Non-tradable annual inflation was 6.0% as of March 2022. By March 2023 it had actually risen to a new peak of 6.8% and it has fallen only very, very gradually subsequently.
The domestically generated inflation has been very much on the minds of the RBNZ folk. The RBNZ had forecast non-tradable annual inflation to be 5.3% as of the March 2024 quarter. But the actual figure when released surprised very unpleasantly on the upside. It was 5.8%, barely down from the 5.9% annual figure reported for the December quarter. All this meant that even though the so-called 'headline' figure had dropped nicely from 4.7% to 4.0%, the RBNZ, as Governor Adrian Orr expressed it to Parliament's Finance and Expenditure Committee, was "annoyed".
It means the RBNZ - notably until this week - has kept pushing back with 'hawkish' sentiments against those who would like to see interest rates coming down soon. In terms of inflation, the RBNZ can't do much about the imported stuff. It's the domestically generated inflation it takes aim at with higher interest rates in order to slow spending and take steam out of the economy.
As we know, the RBNZ's reaction to the inflation explosion was to rapidly hike the Official Cash Rate from just 0.25% at the start of October 2021 to 5.5% as of May 2023. At which point the RBNZ called a halt to proceedings.
Bring on the cuts!
According to its latest forecasts made in the May 2024 Monetary Policy Statement (MPS) (see page 50) the RBNZ hasn't seen the OCR being cut till the second half of 2025.
The financial markets have not agreed, even before the RBNZ's 'dovish' turn in the past week.
We don't get new forecasts from the RBNZ till its next OCR review on August 14 at which point a new MPS will be published. Given the RBNZ's comments in the past week, it is to be assumed it is certainly changing its mind about when the cuts will come - but in terms of what it actually decides, that will depend hugely on the inflation figures and to some extent also on the forthcoming labour market figures on August 7.
The public of course are more than just politely interested bystanders in all this. Many mortgage customers have been 'going short' with their fixed mortgage rates - as short as six months - in the belief that rates are coming down sooner rather than later. So, will rates come down soon?
What do we need to see from the inflation figures? Well, obviously they need to come down. As a corollary to that the inflation figures need to show that the RBNZ is on track with its forecast that inflation will be back under 3% by the end of this year. The May MPS forecast was for annual inflation to be 3.0% in the September quarter and then 2.9% in the December quarter. Interestingly in its OCR review in the past week the RBNZ talked about inflation getting back under 3% "in the second half" of the year - which suggests it's thinking this might now happen a bit earlier than it thought - probably in the third quarter. A number of economists think sub-3% WILL be achieved in the September quarter.
But where things might go wrong is if the 'headline' figure is good (and I think it will be), but the domestic, non-tradable figure is still super sticky (which it may or may not be, but my best guess, and to some extent hope, is that it might this time have 'unstuck' itself and dropped accommodatingly).
The RBNZ has previously been taking out its frustrations about the stubbornly high non-tradable inflation figures by pointing out some of the main 'culprits' - such as local authority rates, energy prices, rents and excise duties on cigarettes and tobacco. There's not a hell of a lot that the OCR can do to 'reach' those kinds of price rises.
By pointing these out as inflation miscreants, the RBNZ has almost been giving a little plea to the likes of councils to just ease up. (Before you jack your rates up, think of the country!)
The economy 'has let go'
Little wonder when you look at inflation culprits like those named above that some economists think the RBNZ should be looking past some of them and not worrying as much about the 'non-tradable' inflation figure as much as it has been.
For what it's worth, my feeling is that the economy has 'really let go' in about the last eight weeks or so. The RBNZ seems to be getting the message now too. I think, for sure, GDP will have contracted again in the June quarter after showing an anaemic 0.2% gain for the March quarter.
What that means is that inflation should be heading off a cliff about now. Prices can't be raised when people either can't or won't afford them. And that's where we are now, I think.
As mentioned earlier, the RBNZ's picking a 'headline' annual inflation figure of 3.6% in Wednesday's CPI results, with a 'tradable' figure of 1.1%. Then there's the non-tradable figure, which remember the RBNZ picked to be 5.3% in the March quarter and it was actually 5.8%. Well, the RBNZ's picking 5.3% again this time - so, if the figure comes in at that level or lower, it might just be about time to start heading for the fridge to get that bottle of champagne out. We. Will. Nearly. Be. There.
Fingers crossed for the CPI figures on Wednesday then. We need them to be down. And we need the RBNZ to be fully convinced that inflation is getting the elbow.
If the RBNZ can be suitably placated then there's really every reason we can have a nice OCR cut (or two!) before Christmas. The economy might need that even more than the RBNZ is beginning to realise.
*This article was first published in our email for paying subscribers early on Friday morning. See here for more details and how to subscribe.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.