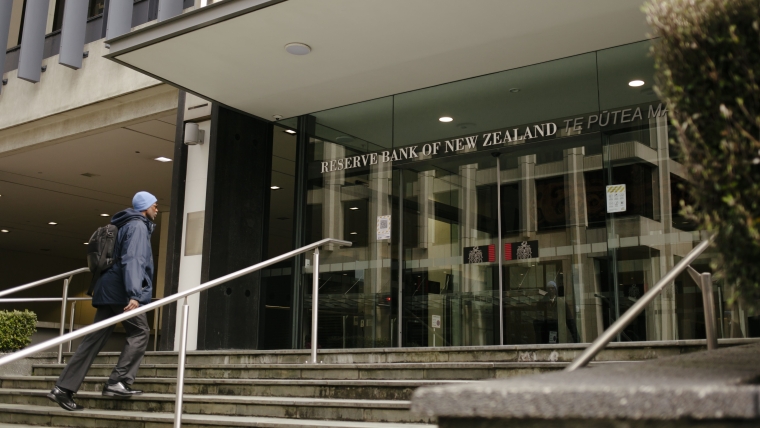
The New Zealand government added half a billion dollars to the Reserve Bank’s balance sheet last month and gave it an indemnity to provide fire-power to intervene in currency markets.
A Treasury document from May shows the agency recommended these measures to cover financial risks from holding and managing reserves, as well as “potential costs in the event of an intervention using hedged foreign reserves”.
The Reserve Bank website said since the NZ dollar has a floating exchange rate it can be mostly left alone, but there are situations in which intervention might be required.
For example, it could need to restore order in the currency market after a big earthquake, or a global financial shock.
“In these situations, liquidity in the NZD exchange rate may be heavily reduced or even disappear completely. We would be prepared to support liquidity until normal conditions returned,” it said.
Holding foreign reserves acts as a type of insurance against a major threat to financial stability which might occur during a crisis situation.
The other reason the Reserve Bank might intervene in the currency market was if the exchange rate was exceptionally high or low and causing problems in the NZ economy.
According to Reserve Bank data, it had currency intervention capacity of $12.9 billion as of June.
Treasury said the central bank’s current level of foreign reserves had not been updated to reflect growth in the economy and global financial markets and may not be sufficient for some scenarios.
The $500 million in fresh capital had been decided by modelling “severe but plausible scenarios” and would be sufficient alongside an indemnity.
The Reserve Bank would use the money to build up its foreign reserves and be ready to intervene at short notice.
Treasury said having the financial backing pre-positioned also provided the market with confidence and helped to mitigate possible crises.
Moving money from the Crown balance sheet to the Reserve Bank’s balance sheet doesn’t have any effect on net debt and can be done outside of the Budget process.
The indemnity would cover situations where the Bank intervenes in the foreign exchange market beyond its positive net foreign asset position and is effectively ‘short’ foreign currencies.
It is essentially a promise to cover the cost of any financial losses that occurred defending the currency.
Treasury said it expected this situation would be rare, and that an indemnity was preferable to a capital contribution
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.