
By Roger J Kerr

It is said that “a week is a long time in politics” and the same description can be applied to financial and investment markets.
A week ago in this commentary I stated “A Trump win produces a "risk off" investor sentiment scenario and thus lower bond yields on safe haven buying. The Federal Reserve would also delay increases in short term interest rates under the Trump scenario”.
Wrong again!
However, this column has been consistent in stating that eventually a catalyst would reverse the fall and very low interest rates we have witnessed over recent years.
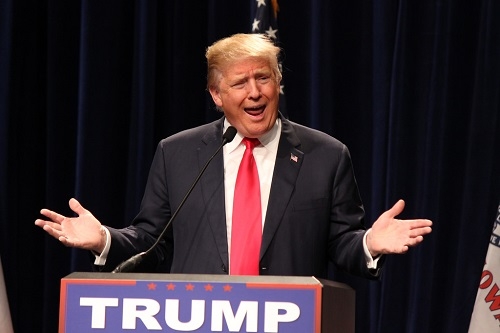
The unexpected Trump victory in the US has delivered that catalyst to the New Zealand interest rate markets with our long-term rates following the US rates higher, despite another cut in the OCR to 1.75%.
The bond market in the US has rapidly concluded that Trump promises of a rebuild and improvement in US Government infrastructure assets would further increase US inflation and the additional Federal Government borrowing to pay for the spend could only send interest rates upwards.
The NZ interest rate yield curve has steepened yet again as short-term rates are anchored by a reduced and low OCR, whilst long-term interest rates track the US yields higher.
The high level of foreign investor ownership of NZ Government Bonds and their treatment of NZ bonds as a higher yielding extension of US bonds is the reason behind the close correlation. When they sell US bonds, they sell their NZ bonds at the same time.
It seems that the recent un-anticipated political and financial market events in the US will have finally convinced both borrowers and investors in New Zealand that our interest rates have seen their ultimate bottom and the far greater risk going forward is rising interest rates.
Just how far our term swap interest rates can increase in the new world order of super low inflation is debatable.
However, the reality is that both US and NZ inflation rates are going to be above 2.00% sometime in 2017.
The speed of rate increase should not be underestimated.
Some bond market pundits are already predicting US 10-year Treasury bonds to increase to 2.50% over coming months from the current 2.13% level. Therefore another 35 point increase in our 10-year swap interest rates to 3.60% seems probable.
Trumponomics has already arguably spelt the end of the artificially low interest rate environment borrowers have enjoyed over the last four years.
Daily swap rates
Select chart tabs
Roger J Kerr contracts to PwC in the treasury advisory area. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.