
The shareholders of giant dairy co-operative Fonterra might reap as much as $3 billion - about $2 per share - from a successful sale of its global consumer businesses, including household name brands such as Anchor and Mainland.
This is according to corporate advisers Northington Partners in an independent review of Fonterra's annual performance conducted for Fonterra shareholders and unit holders.
Fonterra announced back in May that the consumer businesses - which include Fonterra Oceania and Fonterra Sri Lanka - were being put on the block and said it was looking at a timeframe of 12-18 months to achieve a sale.
In a strategy update issued by Fonterra in late September, the co-op pledged a "significant capital return" if it achieves the planned asset sale. However, it has not quantified in dollar terms what the return might be.
But Northington Partners, in its review, has given some clear indications.
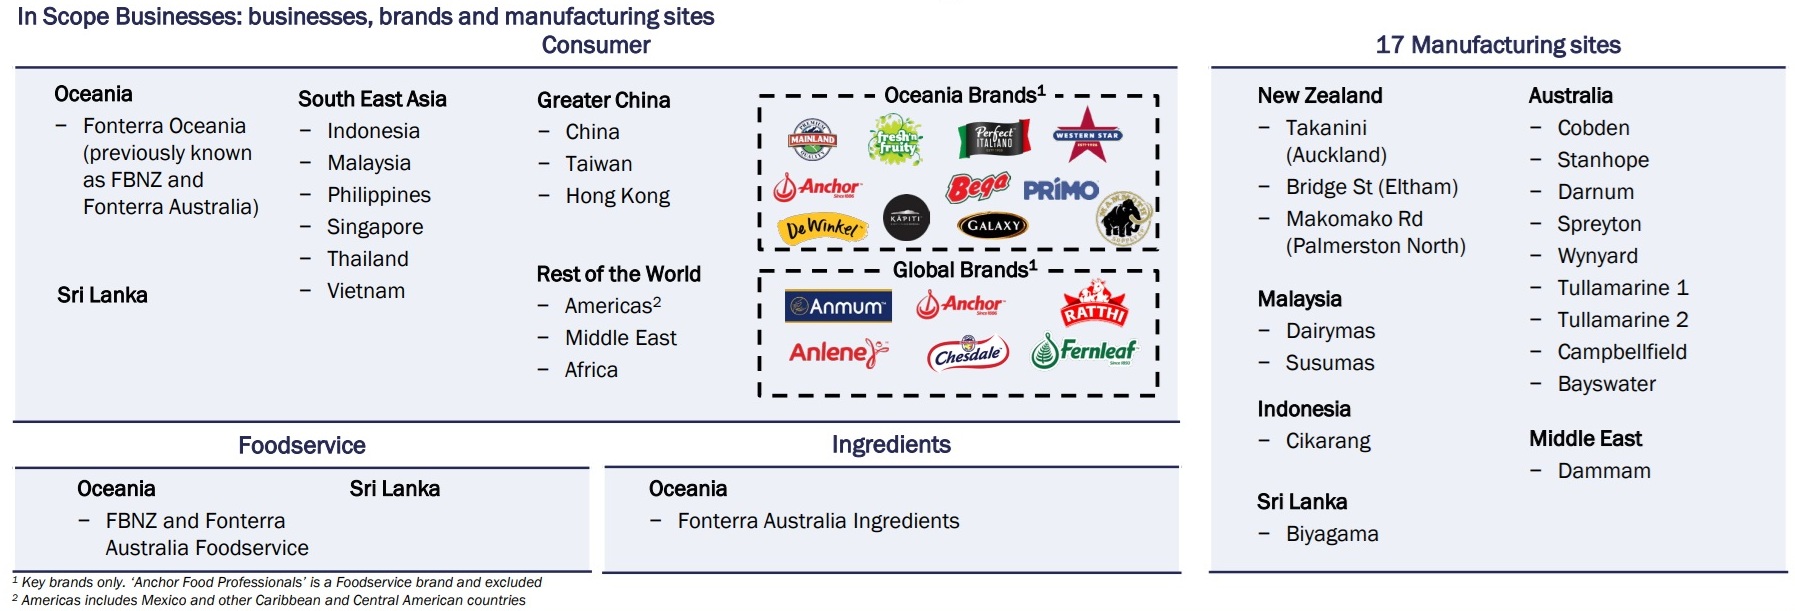
Given the value of the businesses potentially for sale, the implications of the divestment for Fonterra and its shareholders "are significant", Northington Partners says.
"We estimate that Fonterra could return up to $3 billion of capital to shareholders assuming a full exit."
The advisers say that they think that the majority of any sale proceeds could be returned to shareholders while still allowing Fonterra to maintain its “A” band credit rating.
"A value of $3 billion-$3.4 billion for 100% of the 'In Scope' businesses represents approximately $2.00 per share. While the level of capital that will be returned to shareholders following a successful divestment process will be influenced by a wide range of factors (including seasonal working capital requirements and expected capital expenditure), it could be material relative to the current share price," Northington Partners says.
The farmer-only shares in Fonterra are currently trading at $4.16, while units in the Fonterra Shareholders Fund (open to non-farmer investors), are trading at $4.88.
Northington Partners say the potential sale of the businesses may result in an upward “re-rating” of the Fonterra share price depending on the price achieved and level of capital returned to shareholders.
"This is largely due to the potential scale of the capital return compared to the current share price (~50% of the farmers-only market price) while a sale would have less impact on earnings, only reducing by ~20% (based on FY24 pro-forma estimates)."
The advisers' report says some of the potential benefits of divestment may include:
• Concentrates Fonterra’s effort on its core business of collecting and processing milk while stabilising supply and improving processing efficiency.
• Creates a simplified co-operative with a focus on maximising returns from its core operations.
• Allows for an exit of the Australian business which has required significant investment at return levels lower than what have been achieved in Fonterra’s other channels and markets.
• Prioritises investment in the Ingredients and Foodservice channels while releasing capital from the In Scope Businesses which would generate more value for shareholders.
• Provides the potential to achieve better return on capital in the remaining businesses.
However, there may be some potential downsides from the divestment "which need to be more fully addressed". These include:
• Less exposure to “value-add” consumer brands and their growth potential. However, historic growth has been limited which may be due to the brands not living up to their potential under Fonterra ownership. We also note that a value-add strategy can readily be pursued through the Ingredients and Foodservice channels on a B2B basis;
• Less diversified earnings streams and a reduced milk pool due to the divestment of Australia; and
• The potential loss of milk sales volumes if the potential divestment does not include milk supply arrangements with Fonterra or the buyer(s) subsequently moves away from Fonterra supply.
Northington Partners notes that Fonterra has committed to engage in further consultation with shareholders in relation to any potential divestment.
"We therefore expect that more information will be provided in due course including details on transaction structure, transaction value, use of sale proceeds (including the level of capital return to shareholders), implications for the brands, manufacturing and people and the ongoing relationship between Fonterra and the purchaser (e.g. milk supply arrangements).
"We expect that more information will become available over the course of the remainder of FY25. We also note that both the sale of the In Scope businesses and any associated capital return are expected to require shareholder approval."
This is the dairy industry payout history.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.