With the latest GDT auction results this week farmers will be feeling a little relieved that the steady decline in prices being experienced since March (small June exception) has finally been reversed. This reversal has been reasonably significant with a +4.9% lift overall and WMP up +5.1% A summary of the specific prices is below:
- Butter index up +3.3%, average price US$5,369/MT
- Cheddar index up +1.0%, average price US$5,046/MT
- SMP index up +1.5%, average price US$3,575/MT
- WMP index up +5.1%, average price US$3,610/MT
The banks should be feeling a little smug having held to their belief that the prices would return to levels which would justify their mostly somewhat bullish predictions. The reason for the turn around is largely laid at production weaknesses, mostly in New Zealand with July production down -6% and the trend continuing into August likely to show a -4% drop.
- Rabobank $9.00
- Westpac $9.25
- ASB $10.00
- ANZ $8.50
Higher prices undermined by much higher costs
The high input costs experienced by all farmers, but particularly Northern Hemisphere farmers, mean that they are not likely to be able to crank up their production quickly to take up the opportunity provided. Fonterra says production will be down -1% for the season. ASB are going further in predicting that New Zealand’s seasonal supply will be down by about -1% to -3% on last season which also had experienced a drop on the previous year. They also predict the NZ$ is not likely to do major turn arounds and climb against the US$ to a level which undermines the value of farmgate prices meaning the high predictions are ‘locked in’.
Rabobank in their last report which was pre the latest GDT are still wary of the China influence which maybe why they have a adopted a more cautious MS price prediction. ANZ, again pre last GDT result, are the most cautious of the major banks and still holding to their $8.50 forecast. The graph they included in their last AgriFocus update clearly shows the fall in dairy production globally.
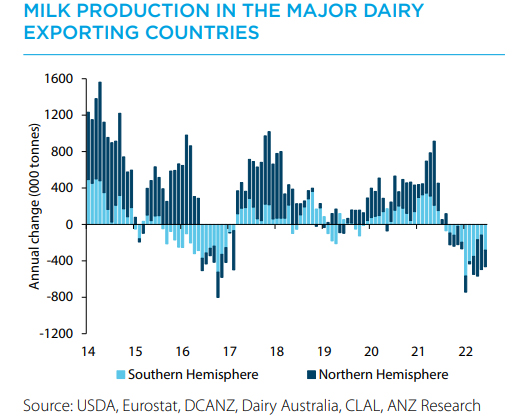
Increasing costs and climate constraints likely to be the major cause and neither showing any likelihood to abate in the foreseeable future.
Forestry's march masked
Going onto a different track, REINZ released an update of rural farm sales recently. In the 3 months leading up to the end of July 2022 there were 127 fewer farm sales than for the same period last year. Going back the full year 289 fewer farms were sold with 1,590 farms sold. Dairy, perhaps surprisingly, bucked the trend with 3% more sales being made although Dairy support were down 31% Grazing farms down 25% Finishing Farms down 13.5% and Arable farms down 19.4%.
Dairy farms prices paid per MS for the quarter ending July 2022 was $36.94 up +10.9% up on the same period last year. Despite this when sales are adjusted for location and differences in farm size (REINZ Dairy Farm Price Index) the index only increased by 1.8%. For the last three months ending July the median price per hectare was $38,880 up from $35,740 for the same period last year. A summary of prices is below with Horticulture being the big mover.

One thing the numbers do not appear to have captured is the number of pastoral farms being converted to Forestry, as the anecdotal reports are that there are plenty.
Grazing farms have increased in value but with the combined Bay of Plenty and Gisborne/Hawke’s Bay (-18 sales) region recording the biggest decreases in sales, mass conversions are not (yet?) being seen in the numbers. It also appeared that the recent sales which were approved by the OIO were included in the sales with “Two sales of larger grazing properties on the East Coast portion of the Gisborne district”. It is quite possible that the way the data is collected, planned conversion to forestry do not get shown and sales remain as grazing until sold as forestry sometime in the future.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.