One of the global fallouts of the Russian invasion of Ukraine has been the highlighting of just who vulnerable world food security can be to disruption.
Wheat or at least grains are a staple part of a balanced diet as well as being a major component of domestic animal diets. They also have the benefit of being able to be stored and relative to other food types can be grown relatively cheaply. However, depending upon where (in this case) wheat is grown there is a large variation in both production and cost of production.
Latterly both of these factors have come under pressure also partly although not solely due to the Ukrainian conflict with fuel and fertiliser costs ratcheting up considerably. Due to the recent impact of the conflict published data is not going to capture all the recent increases in costs however given the widespread nature of the cost increases it can be expected that the same or at least similar relativity between regions will remain.
Wheat, which has been around for over 8,000 years and grown on over 240 million hectares, is able to be grown in most hemispheres of the planet with large volumes being grown in both North and South Americas, East and Western Europe, Australia (and New Zealand) the Indian sub-continent, China and Africa. However, despite the widespread nature of where wheat is grown there are still plenty of countries which are largely, in some cases, totally, reliant of importing wheat to meet their needs.
The top 10 wheat producing countries by volume are:

However, if the EU were combined as one block, they would be second only to China with 126,658,950 tons.
It is also worth noting that although corn is the most produced grain crop globally, wheat is the most traded across borders and 30% of that is made up of Russia’s and Ukraine’s. (An aside of some interest is given how world trade has been disrupted by the Ukraine conflict, New Zealand makes up approximately 35% of world traded dairy products. This shows how vulnerable world dairy demand is to the vagaries of New Zealand production and if there was a sharp drop-off in production here it would have global ramifications).
Yields vary considerably across different regions with rates going from 1.5 tonnes per hectare or less in developing countries often affected by drought, although Australia at the national level also is around only 2 tonnes per hectare with New Zealand at 10 tonnes on the top of the pile.

As can be seen when comparing the top 18 nations on productivity only China and the EU as a block feature on both tables.
The other issue that emerged was how little profitability is achieved by any of the major producing countries. A study by Purdue University (USA) showed that on average over the 5 years from 2016 – 2020 the majority of farms studied (at the national level) showed that the wheat enterprises operated at a loss for at least several years. It does not necessarily mean that the farms on the whole were not profitable with other enterprises ‘carrying’ the wheat losses.
The largest typical farm in the Ukraine had an average loss per hectare of US$100. Average losses per hectare for the typical farms in Australia, Saskatoon, Germany, North Dakota, and Kansas were $18, $18, $56, $55, and $103 per hectare, respectively, during the five-year period. The lowest economic profit during the five-year period for the typical farms was 2019 with an average loss of $80 per hectare. The average loss in 2020 was $79 per hectare. Average economic profit was positive for 2016, 2017, and 2018.
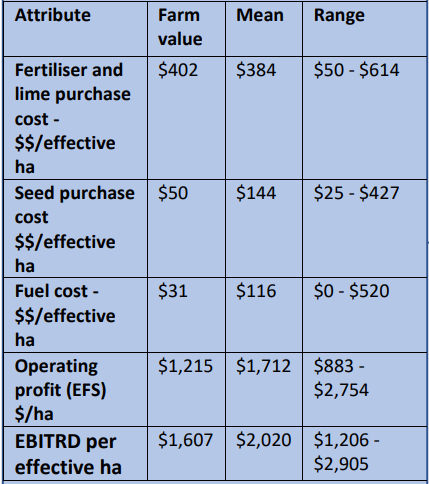
The situation in New Zealand while seemingly difficult to get an overall picture, an Autumn 2022 paper put out by FAR and based upon Manawatu farms in this case showed a more positive outlook for arable farms in general with a profit level of around $2,000 per hectare.
However, New Zealand blessed with rainfall and irrigation while seemingly as or more profitable per hectare than other countries has a greater range of land use options which may provide greater returns. There is of course the potential for this to change if all enterprises externalities were taken into account and costed in.
The EU in late March, aware of the spanner in the works the Russian invasion was/is having of world food trade and costs to consumers, agreed to subsidise its farmers to the tune of US$550 million to increase in particular wheat production.
On a positive note, it is now looking as though some resolution is being reached to enable wheat and other food stocks currently locked in Ukraine access to the Black Sea and out onto world markets.
In the meantime both costs to producers and consumers will skyrocket as fuel and fertiliser costs are increasingly still impacting upon returns to growers and hence onto consumers.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.