A recent inquiry over the impact of fire or other natural disturbances on a forestry block (of whatever type) that is registered to collect carbon credits from the ETS, prompted this article and coming on the heels of the latest IPCC report perhaps makes it a bit more relevant.
At the moment total emissions from “natural disturbance” in New Zealand forests over the latest calibration period I could find (1990–2009) is a relatively small fraction of the country’s total forest carbon budget (e.g. it represented about 5% of the annual net removals by planted forests; MfE 2012) when compared with other countries such as Canada, where natural disturbances are responsible for up to 30% of the country’s total emissions.

Source: MPI 2014
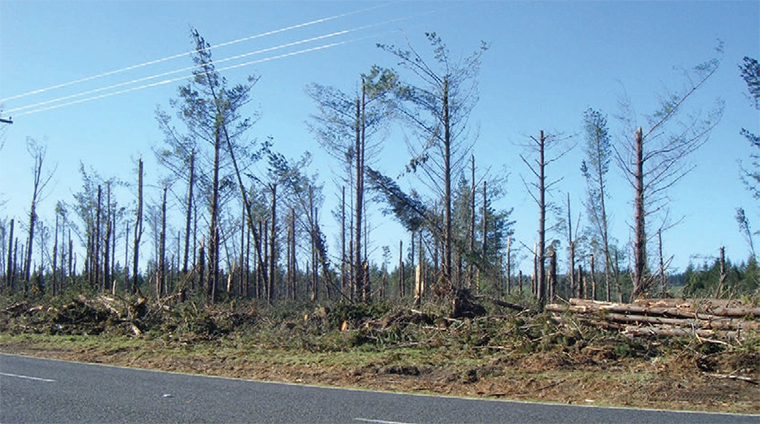
Over the period recorded wind was the major cause of losses with fire relative minor. Those around Canterbury in 2013 will also remember the huge losses which resulted in an estimated 4,000ha of forest flattened, and greater damage occurring back in 1975.
Source:NZFFA
Since the mid-1960’s approximately 70,000ha’s of forest has been destroyed, but then New Zealand is a windy country. However, in recent times, the perception at least is that fire is over taking wind as the major culprit of destroying forest. The area of forest burning each year in New Zealand is going up. It has doubled since recent records began, from about 300 hectares a year since 1988 to over 600 hectares by 2015. While some of this area is native forest, the majority is exotic plantation. Last year an estimate is that over 2,000ha’s was burnt. In the meantime, outside of New Zealand the reporting of wildfires has become a daily event with the areas over all continents being measured in thousands of kilometres not hectares.
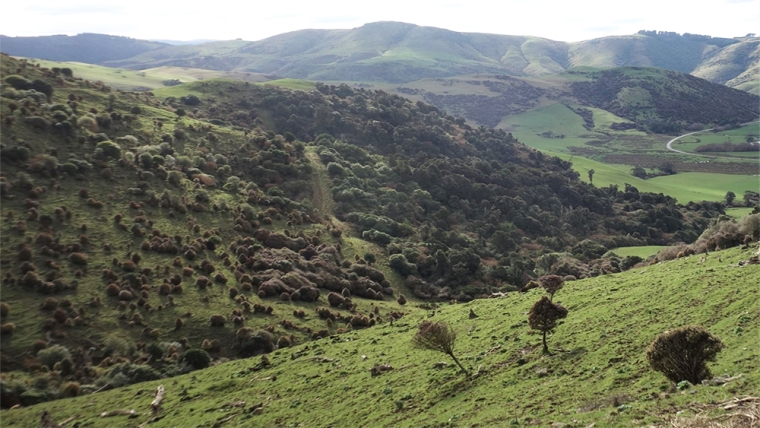
In the background we are still hearing stories about productive farmland being converted to forestry.
It begs the question have these forestry investors done their homework around future risks of being able to achieve the returns they expect? Below is a map of the expected increases in projections of annual frequency of Very High and Extreme (VH + E) forest fire danger over fire season months (Oct–Apr).

Source: Forestry: An International Journal of Forest Research, Volume 92, Issue 1, January 2019,
When averaged over all sites, the number of days with VH + E fire risk is projected to increase by 71 per cent by 2040, and by a further 12 per cent by 2090. Of course, wind, disease and insect damage are also predicted to increase with the onset of climate change.
Forest established from now on are likely to be using the updated ETS system for forestry which allows them to adopt averaging accounting as laid out by MPI. Under this system foresters using averaging accounting won’t have to pay back NZUs after adverse events. (Fire, wind, volcanic events and Alpine fault like earthquakes to name some). This means no requirement to pay back emissions units for carbon storage lost after a significant adverse event, if the affected area is re-established within four years. This non-liable aspect must make the perceived risk appear less. At least on the surface.
Unfortunately, the law also has a non-double dipping clause which means no additional carbon credits can be earnt until the forest is back up to the stage at which it was destroyed. This could be another 15 -30 years as younger forests tend to be a bit safer. So, the forest owner not only has the cost of replanting and delayed harvest dates to contend with but also no carbon credits, which presumably have been a major part of the motivation for planting the forest in the first place. Insurance could be seen as an obvious ‘first defence’ against financial losses and a forestry online put the following example of what some of the potential losses are.
Like what you read? Support our journalists. Find out how.
Marlborough Fire December 2015
Estimated 1250ha burnt over 14days. Cause determined as a hot chainsaw left unattended. Estimated $2M in fire suppression costs. At the time, likely New Zealand’s largest commercial plantation fire at an estimated $14,000,000 claim value. If the forest was covered then any insurance company is not going to willingly dig into their pockets.
It is likely most forests are not fully covered also, given the full cost of insurance.
Something else to consider; if the landowner is aiming to establish a ‘permanent forest’ there will come a time when the forest stops sequestering carbon. This is the case whether the plan is to harvest it or to leave it alone as a ‘Permanent Forest Sink Initiative Forest’. So, the credits will eventually stop coming. But the liabilities will likely go on forever. At the very least the forest owner may need to maintain those insurance payments in perpetuity, and regularly pay for someone to check that your carbon still exists and register that fact with MPI.
For sheep and beef farmers (this may also apply to deer and some dairy) there are other ways in which they are able to mitigate the risk. Most hill farms have areas of lesser use for livestock production. These could be put into ‘pockets’ of forestry of smaller areas. This should mean that risk from fire and wind are reduced are there are effective ‘firebreaks’ and changes in ‘aspect’ which offer some protection.
Smaller plantations do often mean that costs of establishment and harvesting are higher but there are ways to work this to the landowner’s advantage. This can be by selective logging where the best logs are extracted first over time and allowing the lesser trees to obtain their optimal value and a later date. Finishing farmers should be very familiar with the concept where smaller numbers of prime lambs and cattle are drafted off at regular intervals allowing lesser animals more time to come up to weight and value. John and Rosalie Wardle have been practicing this concept for decades now to their advantage. The video link is worth a look to those unfamiliar with either them or the concept. Selective logging should also reduce the incidence of damage created by slash (waste trimmings) washed into waterways in floods etc.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.