Considering the amount of publicity given to people facing so-called mortgage stress, the number of homes facing a mortgagee sale remains surprisingly low. Perhaps this is in part due to a secret weapon the banks have when dealing with home owners who can't make their mortgage payments.
It goes by various names but is most commonly referred to as either an unauthorised overdraft or unarranged overdraft. For the purposes of this article we will simply refer to as an overdraft.
According to the Reserve Bank, it generally works like this:
"When a customer has a standard loan facility [mortgage] with payments linked to their current account, and there are insufficient funds to cover a loan payment, most banking systems will not mark the loan as in default.
"Instead, they will automatically place the current account into an unauthorised overdraft."
This means the full amount of the regular mortgage payment will be paid from the overdraft, and any shortfall arising from what the customer can afford to pay, accumulates in the overdraft account.
So in simple terms, say the regular mortgage payments are $1400 a fortnight but the customer can only afford to pay $1200.
The full payment of $1400 is made from the overdraft account, and the shortfall of $200 remains within the overdraft.
Over time the shortfall would continue to accumulate within the overdraft, but the mortgage payments would be up to date.
However for the borrower, this brings with it problems of its own, because essentially they are paying down debt with more debt, and are also partly replacing relatively cheap debt (on the mortgage) with very expensive debt (on the overdraft).
Debt managers spoken to by interest.co.nz, who have asked not to be named, say the interest rates charged by the banks on so-called unauthorised overdrafts can be around 22%.
To be fair to the banks, you would have to say that such arrangements carry a very high level of risk, and the interest rates charged reflect that.
The advantage of such arrangements is that they provide a little bit of breathing space until a permanent solution can be found and that avoids having to proceed immediately to a mortgagee sale.
Interest.co.nz monitors the number of residential mortgagee sales coming to market and these are currently running at around a dozen a week.
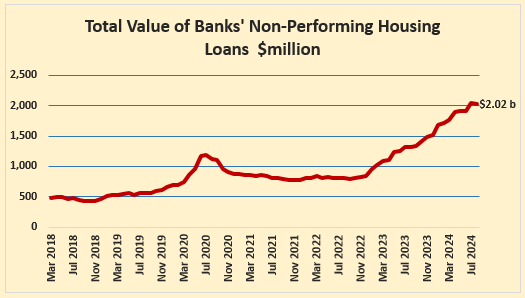
That's a drop in the bucket considering that according to Reserve Bank figures, the total value of non-performing housing loans was $2.02 billion at the end of August (see graph below).
That figure includes mortgages with the type of overdraft facility described above.
According to the Reserve Bank, when an overdraft is put in place to cover a shortfall in mortgage payments, the mortgage is classified as "past due' and after 90 days this becomes "non-performing."
So eventually the piper must be paid and as well as finding a way to meet their ongoing mortgage commitments, the borrower will also need to pay down however much has accumulated in the overdraft under such arrangements.
But hopefully they should still have their house.
The comment stream on this story is now closed.
*This article was first published in our email for paying subscribers. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.