
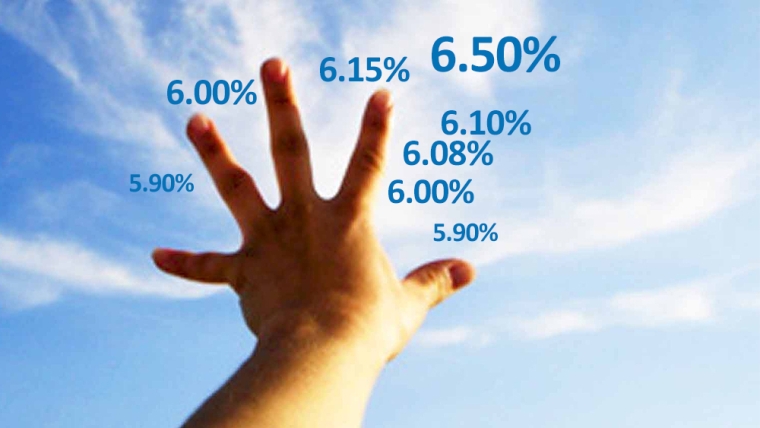
They are not quite there yet, but the main banks are getting much closer to offering a 6% term deposit (TD) rate.
ANZ has now stepped up to match BNZ and Kiwibank with a 5.90% one year TD rate. That is its highest rate since just before the Global Financial Crisis.
Update: And now Westpac has matched these same rates with a set of +10 bps rises.
Higher rates are motivating savers to shift funds from low-yielding current accounts and savings accounts. They are also helping grow customer deposits.

The spreading of higher rates to the main bank offers will enhance that shift. And it should get a new push along when main banks start offering rates of 6% and more. (Or maybe that should be "if" main banks start offering rates of 6% and more).
But 6% rates are available now from many challenger banks.
For nine-month terms, Bank of China offers 6.08%, Heartland Bank offers 6.00%, and Rabobank also offers 6.00%.
For one year, way out in front is SBS Bank which offers 6.50%. Heartland Bank offers 6.10% for 12 months. Bank of China offers 6.18% for 12 months. Kookmin Bank offers 6.00% for a minimum $10,000 deposit, but 6.10% for a minimum $100,000 deposit. China Construction Bank is also at 6.00%. TSB does too. But Rabobank offers 6.15% for a one year term deposit.
Only one bank, Rabobank, offers 6.00% for a longer term, out to 18 months. Otherwise offers from all banks fall away fast from there. There are more details on how and why here.
One risk savers should watch is the cost of wholesale money and you can do that looking at swap rates. You can do that here. Earlier this week the one year swap almost touched 6.0% again. It did that first in May. We have had a long almost three year run up in background money costs. The Official Cash Rate rises have been part of that. If this trend reverses for any reason, the pressure on rates to savers will ease making those who locked in longer rates look good. Wholesale swap rates haven't shown any sign of pushing up bank to the 6% level in recent weeks.
Almost all banks are pricing longer rates lower than their one year offers, and that inversion is growing.
An easy way to work out how much extra you can earn is to use our full function deposit calculator. We have included it at the foot of this article. That will not only give you an after-tax result, you can tweak it for the added benefits of Term PIEs as well. It is better you have that extra interest than the bank, especially if you are in the 39% tax bracket - PIEs are taxed at 28% flat.
* Kookmin Bank's 6.10% one year offer is for deposits of $100,000 and more. For a $10,000 minimum it is 6.00%.
The latest headline rate offers are in this table after the recent increases.
| for a $25,000 deposit July 27, 2023 |
Rating | 3/4 mths |
5 / 6 / 7 mths |
8 - 11 mths |
1 yr | 18mth | 2 yrs | 3 yrs |
| Main banks | ||||||||
| ANZ | AA- | 4.30 | 5.75 | 5.80 | 5.90 | 5.70 | 5.50 | 5.25 |
 |
AA- | 4.20 | 5.65 | 5.65 | 5.85 | 5.75 | 5.70 | 5.60 |
 |
AA- | 4.30 | 5.75 | 5.80 | 5.90 | 5.70 | 5.50 | 5.20 |
 |
A | 4.20 | 5.75 | 5.80 | 5.90 | 5.40 | 5.20 | |
 |
AA- | 4.30 | 5.75 | 5.75 | 5.90 | 5.50 | 5.40 | 5.20 |
| Other banks | ||||||||
| Bank of China | A | 4.70 | 5.88 | 6.08 | 6.18 | 5.80 | 5.50 | 5.30 |
| China Constr. Bank | A | 5.00 | 5.85 | 5.90 | 6.00 | 5.85 | 5.50 | 5.40 |
| Co-operative Bank | BBB | 4.20 | 5.70 | 5.75 | 5.90 | 5.65 | 5.60 | 5.50 |
| Heartland Bank | BBB | 4.00 | 5.90 | 6.00 | 6.10 | 5.35 | 5.30 | 5.30 |
| ICBC | A | 4.70 | 5.65 | 5.90 | 6.00 | 5.80 | 5.45 | 5.40 |
| Kookmin Bank | A | 4.40 | 5.60 | 5.70 | 6.00* | 5.20 | 5.20 | |
 |
A | 4.75 | 5.90 | 6.00 | 6.15 | 6.00 | 5.70 | 5.60 |
 |
BBB | 3.90 | 5.50 | 5.40 | 6.50 | 5.35 | 5.35 | 5.35 |
 |
A- | 4.25 | 5.30 | 5.40 | 6.00 | 5.50 | 5.50 | 5.25 |
Term deposit rates
Select chart tabs
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.