

By Roger J Kerr
'Learn from your mistakes' is what we all tell our kids – which doesn't always work 100%.
However the managers of monetary policy should always look back and evaluate what they did in the past and examine the success or otherwise of a particular monetary policy stance.
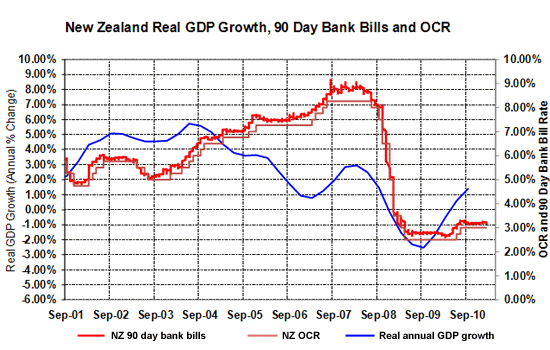
If they made policy setting errors they should learn from those mistakes. I have eternal hope that the RBNZ did look back critically at the 2005/2007 period when they tightened policy with interest rate above 8.00%, when the economy was already on a track to much weaker growth (see the GDP growth chart below plotted against interest rates).
At the time they were pre-occupied with excesses in the residential property market pushing inflation higher. Having monetary policy too-tight-for-too-long at that time caused the subsequent economic recession in 2008/2009 and severely damaged the export/productive sector via the high exchange rate.
Today we have the inverse of that situation developing with the RBNZ running the risk of having monetary policy too-loose-for-too-long.
The danger is that inflationary risks build up in a stronger growing economy this year because the RBNZ delay monetary policy adjustments until it is too late to be effective.
The markets and the RBNZ are currently looking back at the flat economy over the second half of 2010 and concluding that there is low risk of inflationary pressures in 2011/2012 and thus monetary policy can remain "very loose" for much longer into 2011.
Mr Bollard has clearly stated that he wants to see conclusive and hard statistical evidence of growth this year before moving the OCR up.
My ongoing contention is that by the time he has the evidence and proof it will already be too late to pre-empt inflationary pressures.
The result is that the RBNZ find themselves behind the 8-ball in controlling inflation and have to push short-term interest rates up more rapidly and in larger steps than otherwise could have been the case.
The outcome of that situation is a sharply rising Kiwi dollar value and further damage to the all-important export sector - yet again!
Monetary policy errors have real economic consequences and lurching from one extreme to another has caused problems in the past. The RBNZ need to avoid being behind the 8-ball later this year and the early-March Monetary Policy Statement coming up is an opportunity for the RBNZ to articulate the risks of leaving monetary policy too-loose-for-too-long.
The RBNZ’s pre-occupation with the residential property markets as the key driver of the NZ economy (thus monetary policy settings) is also a dangerous in-built bias.
If they are waiting to see some life in the housing market this year before adjusting the OCR upwards, they will be looking at the wrong lead indicator.
The critical lead indicator to stronger GDP growth this year will be when and how farmers spend their much increased incomes form the record high beef, lamb and diary prices.
The RBNZ are firmly of the view that all the extra income will go to repaying debt (particularly in the highly indebted parts of the dairy sector).
The majority of farmers will however be reinvesting the additional cash in their businesses with fertiliser, fencing, contractors and machinery.
That increased spending has an enormous impact on provincial New Zealand and eventually feeds into the cities. The high prices are a big incentive to lift output off the land. As dairy land prices recover back up and farm balance sheets improve the bank lenders will relax somewhat.
--------------------
* Roger J Kerr runs Asia Pacific Risk Management. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.