
Bernard Hickey details the seventh in this series of Top 10 charts for 2010 in association with Bank of New Zealand.
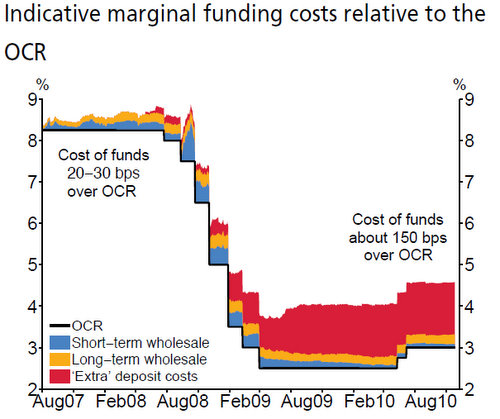
This chart from the Reserve Bank's December quarter Monetary Policy Statement shows the 'extra' funding costs banks must pay to borrow money.
The chart below expresses this 'extra' cost as a margin to the Official Cash Rate (OCR), which sets the base for all short term interest rates.
The banks pay a slight margin to borrow short term 'wholesale' funds from each other and international banks.
Our banks still rely on this short term 'hot' wholesale money, but to a lesser extent than before the Global Financial Crisis froze the markets for such funds in the wake of the collapse of Lehman Bros. This is the light blue area in the chart below. These costs are now back to the levels pre-Lehman.
They also rely to a significant extent on longer term wholesale borrowings, often from international banks and pension funds. These costs, shown by the yellow area in the chart, are back to pre-Lehman levels.
The big area of difference in the funding costs for the banks is for term deposits (red area). See all term deposit rates here for one to five years.
Pre-Lehman the banks didn't compete too hard for these local term deposits because they could get such funds easily from international 'hot' markets and they weren't required to raise funds locally.
That has changed because it is harder to get such funds internationally and the Reserve Bank has stipulated in its 'Core Funding Ratio' that more than two thirds of bank funding must come from long term and local 'stable' sources.
All this means the banks are now offeringing significantly more than the OCR to raise funds locally, to the extent that Kiwibank now has to raise funds offshore because of competition for such funds from the big four banks.
More than two years after Lehman's collapse total 'extra' funding costs are still about 150 basis points (1.5%) above the OCR. Before Lehman this 'margin' was about 20-30 basis pionts.
The banks are passing this on in the form of charging higher floating and fixed rates (relative to the OCR and wholesale interest rates) than before Lehman's collapse.
Some had expected this margin to contract back to 'normal' levels, but more than two years later it remains high.
It isn't expected to contract much over 2011, although the banks are expected to try to reduce these funding costs somewhat by issuing covered bonds offshore.
However, they are limited to issuing up to NZ$32 billion, less than 10% of total assets, which means any gains will be marginal at best. See more here on covered bonds.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.