

Here's our summary of key economic events overnight that affect New Zealand, with news China is still winding up its debt support of their economy.
But first, the US Federal Reserve balance sheet is still shrinking, now for the fifth consecutive week. After growing sharply to almost US$7.2 tln, it is now down below US$7 tln, a decline of -$248 bln.
The USDA's WASDE report has raised its forecast for imports of beef into the US and lowered its forecast of US milk production. US red meat production is falling and is projected to fall well into 2021 even if the trend is minor. Both trends will aid New Zealand's trade in these key commodities. But they do see dairy output rising in 2021 even if they missed forecasting it falling in 2020.
Canada's economy added almost one million jobs last month, as businesses reopened after their COVID-19 shutdowns. And that is on top of the +290,000 it gained in May. But despite that two-month stretch, there are still -1.8 mln fewer jobs in Canada as at the end of June than there were in February. Almost half their job gains were part-time jobs. Their jobless rate fell to 12.3% in June, down from the record high of 13.7% it hit in May. (Across the southern border, the US unemployment rate is 11.1%.)
China's economy is expanding. Their car sales rose in June for the fourth consecutive month and posted the first quarterly rise in two years. It's now the world's largest car market and 2.3 mln vehicles were sold in June, rising almost +12% year-on-year. However the industry is warning they face up to a -20% fall from here if conditions worsen.
But new debt is doing its part still. Chinese banks extended ¥1.81 trillion yuan (NZ$400 bln) in new yuan loans in June, up a startling +22% from May and up +13% year-on-year. There is nothing new debt can't solve in China.
In Singapore, as expected, the ruling PAP party swept to victory again winning all but ten seats in their general election. The Lee family reigns supreme with as corrupt an election system as any in Asia, and now including Hong Kong.
In Australia, ANZ says the six-week lockdown of metropolitan Melbourne will lead to a second wave of businesses going belly up. Further, they say homeowners may need to sell up too if they can't pay. And the Canberra government is readying more wage support as their current program comes to an end. Its a treadmill they can't get off. In fact, so far no country has shown how to get off.
Equity markets are higher today with the S&P500 up +1.0% in late afternoon trade on Wall Street. They are closing in on a weekly gain of +1.7% and taking the year-to-date loss in market capitalisation down to -US$420 bln. European markets closed the week higher on the day too, generally up more than +1%. Frankfurt was up +0.8% for the week, Paris was down -0.7% and London was down a bit more than -1%. Shanghai closed yesterday -2% lower on the day to cap a week of strong gains, up +7.3% as profits we taken at the end and State pension funds started selling. Hong Kong was up +1.4% for the week while Tokyo was unchanged for the week. Locally, the ASX200 ended the week with a -2.3% loss and the NZX50 ended with a -1.5% loss.
The latest compilation of COVID-19 data is here. The global tally is 12,342,000 and that is up +223,000 since this time yesterday. Global deaths reported now exceed 556,000 (+5000).
A quarter of all reported cases globally are in the US, which is up +69,700 overnight to 3,257,700 3,188,000. US deaths now exceed 136,000. The number of active infections in the US is now up +41,600 to 1,687,000. Both infections and deaths are on the upswing again.
In Australia, there have been 9359 cases reported, another +303 since this time yesterday, and still concentrated in Melbourne which is now in lockdown. Their death count is unchanged at 106 and 13 people are now in ICU (+3). Their recovery rate has slipped back further to 81%. There are now 1627 active cases in Australia (up +249 in a day).
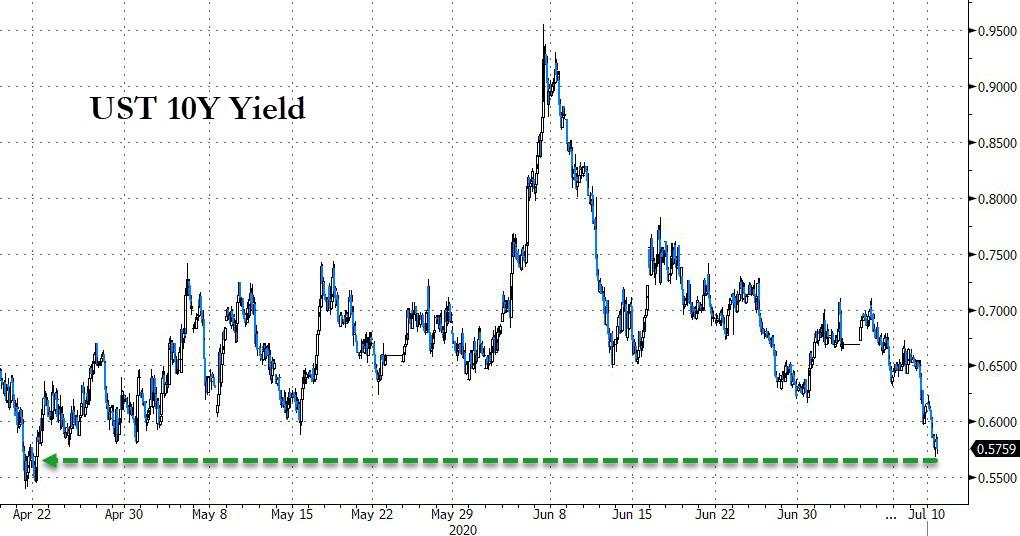
The UST 10yr yield is a little firmer today, now just on 0.64%. Their 2-10 curve is up to +48 bps. Their 1-5 curve is also firm at +15 bps, and their 3m-10yr curve also firmer at just under +53 bps. The Aussie Govt 10yr yield is up +2 bps at 0.89%. The China Govt 10yr is down today by -5 bps at 3.13%. And the NZ Govt 10 yr yield is also down, up by -4 bps to 0.98%.
The gold price has slipped further, today by another -US$3 today to US$1,798/oz.
Oil prices are up today, and by a bit more than +US$1. They are now just over US$40.50/bbl in the US and the international price is just over US$43/bbl.
But the Kiwi dollar is little-changed at just over 65.7 USc. On the cross rates we are firmer at 94.6 AUc. Against the euro we are still hanging in at 58.2 euro cents. That means our TWI-5 is still at 70.3.
The bitcoin price is unchanged overnight at US$9,225. The bitcoin rate is charted in the exchange rate set below.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.