
Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
ASB has changed most of its fixed rates today, cutting its 18 month and two year rates, raising its 3, 4 and 5 year rates. ICBC's hot 4.99% three year rate is ending today. It will revert to 5.25%. All current mortgage rates are here. And note, you can compare mortgage offers with our unique calculator that takes into account other costs and cashback incentives, here.
TERM DEPOSIT/SAVINGS RATE CHANGES
ASB has tweaked a small number of rates up, but only to match their main rivals. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
RISING FASTER
Residential construction costs are shooting up again. Residential building costs increased sharply +4.8% in Q3-2026 from a year ago and are now well above long term average. It is not a metric that will encourage more affordable housing.
LOSING SHARE
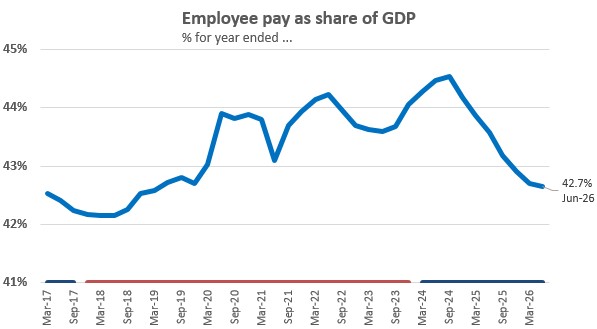
StatsNZ released more details about Q2-2026 GDP today, and that included sector accounts. Within the household sector data is an item called "compensation of employees". Related to overall GDP, that gives us a view of whether employees are getting a larger share of economic activity or not. The answer seems to be 'not'. It perhaps explains why many people feel under pressure. In fact, it is interesting to overlay the government administration driving the economy, especially as it is election year.
MORE ON THE Q2 INCOME & WEALTH DATA
There was more in this StasNZ release than the above relationship of course. The other key takeaways (courtesy of Westpac's economists) include the continuing rise in overall household income levels. Much of that is due to increases in 'entrepreneurial earnings' (which is in part due to increased earnings in the agricultural sector). Wage and salary growth has been more limited but has picked up. Household savings levels have been rising for three years now, with another solid rise over the past three months.
Overall household wealth levels have risen modestly. Although the value of households’ financial assets is continuing to rise, housing assets have essentially shown no growth since late 2023. Household spending on interest costs rose just slightly in the June quarter. That’s the first increase in two years. The easing in average borrowing costs seen over the past few years has come to a close with the RBNZ’s hiking cycle now underway.
TOP CONCERNS
ASB has been surveying businesses of their main concerns and the top two are now the general economic uncertainty (79% of those surveyed) , and followed by the cost and availability of energy (73%). Fewer than 40% of businesses expect they could continue operating for more than three days if their primary energy source was down. (40% actually seems an heroic level for urban businesses.)
ANOTHER MOVES UP
After yesterday's dairy auction, Westpac has moved to raise its payout forecast by +25c to $9.50/kgMS, putting it mid-pack. They make an interesting point that El Nino is apparently not figured in to the risks to these levels. All the same, if they are and that results in lower output, then you might expect export dairy prices to rise. So far, milk flows are strong and we are approaching the peak of the dairy season, usually at the end of October..
NZX50 DIPS
As at 3pm, the overall NZX50 index is down -0.1% so far and down -1.1% for the past 5 trading sessions. It is up +4.7% from six months ago. From a year ago it is now only up +1.1% now. Market heavyweight F&P Healthcare is up +0.7% so far today. Stride, a2 Milk, Spark and Freightways gain while Gentrack, Oceania, Ryman and SkyCity casino decline.
HIGH DEMAND
In today's NZGB tender, just on $2 bln was bid in 86 applications for the $450 mln available in two maturities. 25 bidders won something. Yields were up +43 bps for the April 2029 one since its last outing 17 weeks ago, up +9 bps for the May 2036 one, a week ago.
EXHAUSTED?
US consumer debt rose just +1.9% in August, about half than the expected level and even less than the July level. Perhaps it is a sign of exhaustion given that spending has been rising much faster than incomes recently. Borrowing capacity may have been maxxed out. As the spending habits of the American middle class is one of the key driver of the world's economy, the implications of this updated data should not be overlooked.
ALSO EXHAUSTED?
China returns to work today after its Mid-Autumn Festival holiday; at least, their stock markets does. And despite outsized holiday travel it seems consumer spending has been relatively subdued. You can sense that because their official media hasn't been trumpeting it. Reality will start to be reflected in the Shanghai stock exchange pricing. An early reading is below.
SWAP RATES LITTLE-CHANGED
Wholesale swap rates will likely be marginally softer today. Keep an eye on our chart below which will record the final positions closer to 5pm. The RBNZ 90 day rate was unchanged at 3.23% on Wednesday. Today, the Australian 10 year bond yield is down -2 bps at 5.39%. The China 10 year bond rate is now at 1.69% and up +1 bp. The Japanese 10 year bond is now at 3.08% and little-changed. The NZ Government 10 year bond rate is now at 5.13% and also little-changed from this time yesterday. (The RBNZ 10 year rate is 'prior day' and was unchanged at 5.11% on Wednesday.) And the UST 10yr yield is now at 5.30% and also little-changed from yesterday.
EQUITIES MOSTLY LOWER
The NZX50 has dipped -0.2% from Wednesday's close. The ASX200 has opened down -0.5%. Tokyo is down -0.7%. The KOSPI is down another -0.7% today to be -3.6% lower so far this week. Hong Kong is down -0.3% in Thursday trade while Shanghai has re-opened and is up +0.4%. Singapore is down a very sharp -2.6% in early Thursday trade today, apparently hurt by changing trust rules in China. Wall Street ended its Wednesday trade with the S&P500 down -0.2% and the Nasdaq was also down -0.2%.
OIL PRICES MIXED
American oil prices have fallen -US$1 from this time yesterday with the WTI benchmark now at just over US$89.50/bbl, while the international Brent price is just under US$102/bbl and up +50 USc, again on unresolved supply uncertainties.
CARBON PRICE HOLDS
There have been more trades today but the price remains little-changed at $52/NZU. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD STABLE
In early Asian trade, gold has eased a slight -US$13/oz from this time yesterday, now at US$4139/oz. Silver is -50 USc softer at just on US$60.50/oz.
NZD LITTLE-CHANGED
The Kiwi dollar is still just under 56.1 USc and little-changed from where we were this time yesterday. Against the Aussie we are also little-changed at 80.5 AUc. Against the euro we are marginally firmer at just over 50 euro cents. This all means the TWI-5 is is now just under 59.9 and little-changed.
BITCOIN RETREATS
The bitcoin price is now at US$83,372 and down -2.2% from yesterday at this time. Volatility has been modest at just over +/- 1.4% again.
HOW THE GLOBAL ECONOMIC FORCES AFFECT US
If you want to catch up on what happened last night, try our Economy Watch podcast, here.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs

This soil moisture chart is animated here.
Keep abreast of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.