
Here's our summary of key economic events overnight that affect New Zealand with news policymakers are still struggling with the last-mile gains in their war on inflation.
But first, the number of Americans making initial jobless claims rose last week and by slightly more than expected. That takes them back to early June levels and while not high, it does arrest the recent reduction trend. And there were less claims in the same week a year ago. It is too early to say if this is a labour market turning point, or an outlier. There are now just under 2 mln people on these benefits.
The Philly Fed factory survey rose sharply to its best level in four months driven by new orders. The outlook for the next year was especially positive.
Japanese exports rose to a three month high in June, a much better outcome than anticipated. While not a record, these exports are at an historically high level and only bested by two previous months in the past year. They are up more than +5% year-on-year and delivered a surprise trade surplus. That is mainly because energy costs no longer swell their import bill.
India's central bank is turning its attention away from supporting breakneck economic growth, to controlling inflation. They signaled this in a Bulletin released yesterday - and a return to the policies of Raghuram Rajan, the ones he got removed by Modi for.
The ECB monetary policy review overnight delivered no change to their official interest rate settings. They are holding their restrictive policies because inflation pressures remain and wage gains seem to be driving those. European companies are suffering decreased profitability because they are unable to pass on these elevated costs, they say. But they reckon the pressures will be temporary until inflation is beaten. Still they seem very unsure when rate cuts will happen again.
In Australia, their employed workforce expanded by +50,100 in June to 14.4 mln. +43,300 of those new jobs were full-time, +6,800 were part-time. Their jobless rate rose marginally to 4.1% and their participation rate is still hovering around 67%. Their employment rate of their working-age population is 64.2%. (In New Zealand, these metrics came in at 4.3%, 71.5%, and 68.4% as at March 2024. Our June levels will be released on August 7, 2024.)
Container freight rates were little-changed last week but that is of no comfort because they are staying +286% higher than year-ago levels. The usual factors remain in play although the Panama Canal water levels are recovering and back to the 5-year average. July is when levels usually start to recover. Bulk cargo rates are little-changed from a week ago, although they did rise modestly in between before retreating yesterday.
And we should probably note - again - that the copper price is still retreating hard, down -7.5% in the past week alone. The reason relates to demand out of the stuttering Chinese economy. Nickel, cobalt and lithium are all suffering too, all components of the 'green transition'.
The UST 10yr yield is now at 4.19% and up +5 bps from yesterday. The key 2-10 yield curve inversion is little-changed at -27 bps. Their 1-5 curve is still at -76 bps. But their 3 mth-10yr curve inversion is less at -116 bps. The Australian 10 year bond yield starts today at 4.29% and little-changed. The China 10 year bond rate is little-changed at -2.27%. The NZ Government 10 year bond rate is now at 4.40%, and down -4 bps.
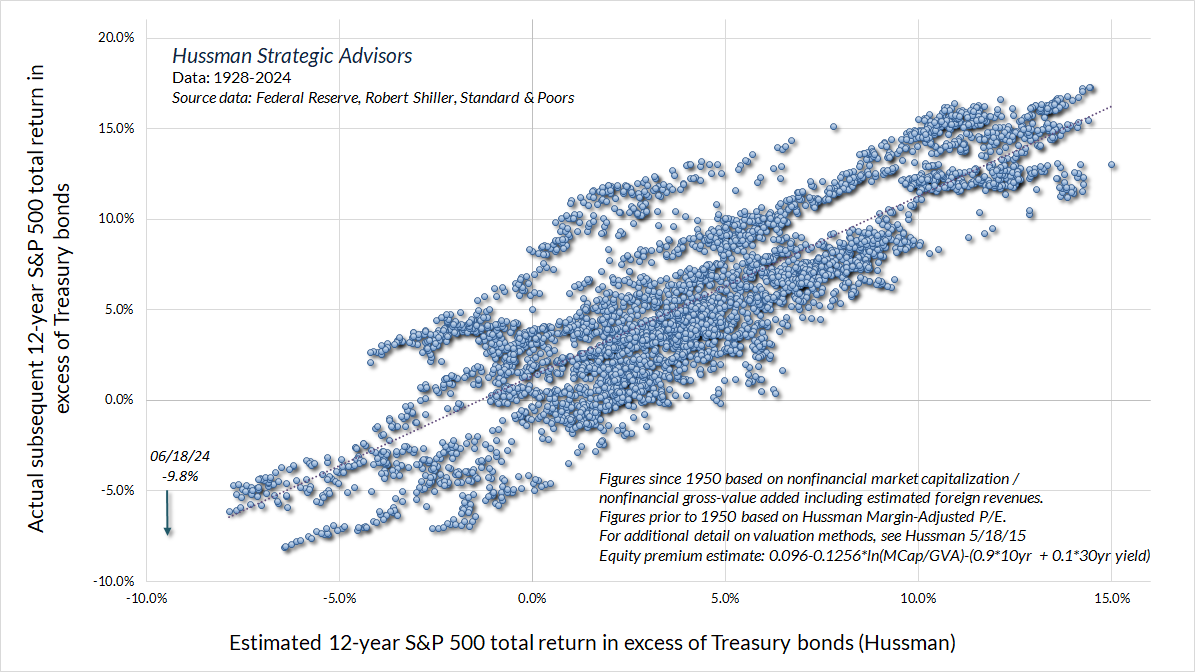
Wall Street is down -0.9% on the S&P500 in Thursday trade and backing off further from its record high. (Instability from a prospective Trump Administration is behind this one.) Overnight, European markets closed mixed in their Thursday trade with Paris and London up +0.2% and Frankfurt down -0.4%. Yesterday Tokyo also ended down a very sharpish -2.4%, Hong Kong ended up +0.2% and Shanghai was up +0.5%. Singapore fell -0.5%. The ASX200 fell -0.3% and the NZX50 ended Thursday up +0.3% and again one the best of the markets we follow.
The price of gold will start today up +US$2 from yesterday at US$2455/oz and still hovering near its all-time highs.
Oil prices are up +50 USc at just on US$82/bbl in the US while the international Brent price is just over US$84.50/bbl.
The Kiwi dollar starts today little-changed at 60.6 USc. Against the Aussie we are also little-changed at 90.2 AUc. Against the euro we are still at 55.6 euro cents. That all means our TWI-5 starts today at 69.4 and essentially unchanged from this time yesterday.
The bitcoin price starts today at US$63,799 and down -0.9% from this time yesterday. Volatility over the past 24 hours has been modest at just on +/- 1.4%.
Daily exchange rates
Select chart tabs

The easiest place to stay up with event risk is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.