

Here's our summary of key economic events over this holiday weekend so far that affect New Zealand, with news the tougher China's economic track seems, the tougher they are getting on allowing their people to explore for themselves.
But first, the World Food Price Index slipped in May as prices for vegetable oils and dairy products retreated somewhat. But prices for cereals and meat rose again, both to record highs. And the overall index is more than +22% higher than a year ago. Food price stress remains extreme.
In China, the gradual easing of pandemic restrictions in Shanghai will see their key Pudong and Hangzhou port centers reopen. And export volumes are predicted to jump in the immediate future. Demand for ocean freight services and container shipping costs are expected to tick up as firms rush to get goods out.
And officials are also claiming that activity is returning to their housing markets. But Chinese workers must now endure regular PCR testing to get back on the job.
Encouraging them are a rush of 'red envelopes', direct cash payments and coupon stimulus to residents to encourage them to get out and spend. An interesting twist is that authorities are rushing out some of this as digital money. Having stimulus bypass the banking system is an attraction to central bankers, and not only in China.
In China, the use of VPNs to avoid the Great Firewall are now illegal and authorities are moving aggressively to ensure their population is barred from access to outside news.
In Hong Kong, police have effectively squashed any public remembrance of the 1989 Tiananmen Square massacre is year - and probably forever. Not in Taiwan however. But Hong Kongers seem to be giving up on their City quicker. 93,000 residents left in 2020, 23,000 in 2021. But in 2022 so far it appears that almost 100,000 have left already. Beijing's grim crackdowns have locals voting with their feet. Schools ae emptying out.
Late last week, South Korea reported a CPI inflation rate of +5.4%, well above the +4.8% in April and the expected +5.1%. That will likely mean another official rate hike there.
Singapore reported retail sales up more than +12% in April from a year ago, but they might have been disappointed in the tepid rise from March.
In the US, their petrol price hit a new all-time record high to start their summer. At US$4.82/gal, that is now the equivalent to NZ$1.95/L (both U91). In the US they aren't paying NZ$1.08/L in taxes however (incl GST, just as the US prices include state and local Sales Taxes) as we are (or NZ$1.21/L in Auckland). Today's local Auckland price seems to be about NZ$3/L for U91. Bottom line is that they are paying about the same as we are.
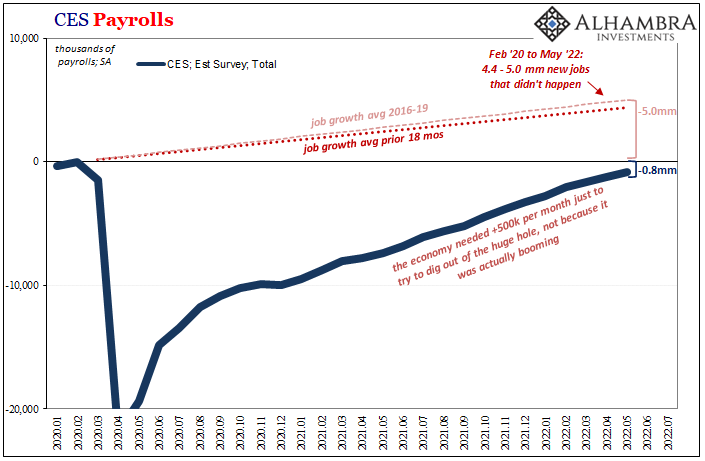
Meanwhile, analysts had expected American non-farm payrolls to rise +325,000 but the key reported rise was +390,000 and this is being considered a positive result. But that leaves them still with -822,000 fewer jobs than before the pandemic struck. Wall Street sees this latest good rise as confirmation that the US Fed will hike aggressively at its next review on June 16, and is ending the week on a glum note.
But as regular readers will know, we like to look past the 'seasonally adjusted' numbers everyone else looks at, and drill into the actual shifts. And these explain why the giant American economy is actually more resilient than most are noticing. The actual May rise was +809,000 more people employed in May than April, on top of the actual +1.1 mln rise in April from March, and the +762,000 rise in March from February. These are all huge gains, taking the actual paid workforce to 151.8 mln people. And even more revealing, that is more than +800,000 above the actual 151 mln employed before the pandemic struck. Yes, they have now recovered all the lost jobs on an actual basis, way better than the standard narratives.
They have a situation where average pay of workers not in management is rising +6.4% pa, and overall payrolls are expanding fast. The combination adds purchasing power to their economy very aggressively - probably too frothy for policy makers.
Most of these employees are in the service sector, and the latest evidence is that this is expanding solidly in the US too. The widely watched ISM survey has it expanding slightly slower than in the prior month, with the internationally benchmarked survey also recording a solid but slightly slower expansion. They may be at the limits of what is achievable with their workforce.
To do better than they currently are, the US will need to find a way to raise its labour force participation rate. It is running at 62.3% of the working aged population, and while it is creeping up it is still low by international standards and still -1% below pre-pandemic levels. But with immigration low and an ageing population, that would involve encouraging those who chose early retirement at the start of the pandemic to get back into the workforce, and that seems an unlikely change.
Last week, the US Fed began the process of shrinking its almost US$9 tln asset portfolio (~35% of US GDP and probably much smaller than you may have assumed) by not reinvesting some of the maturities. This is a sure sign their economy is recovering fast, and builds on the fast-shrinking Federal Government deficit. Both are evidence of much more professional economic management in place there now.
But not everyone is upbeat about where their economy is headed. Both Elon Musk and Jamie Dimon have issued warnings about what their own companies face, although in Musk's case it might be a sign of stress from over-reach, especially in China and Europe, and in Dimon's case it could be that a leveling out might threaten his giant bonus. It's all about the future, so anything is possible.
In the EU they reported April retail sales volume levels and they didn't bounce back as much as they had expected, and they would certainly have been disappointed in the monthly slip.
Germany has raised its minimum wage to €12/hour (NZ$19.75 /hr) in a move said to help 6 million low paid workers.
And in Australia, their new government is pushing for a +5.1% minimum pay increase for their low paid. It will take their minimum wage to AU$812/week (NZ$22.50/hr NZ$900/week or NZ$46,800 pa). It will go to about 1.3 mln Australians. Australia's CPI is currently running at 5.1%.(New Zealand's adult minimum wage is currently NZ$21.20/hr. Given Australia's taxes are higher, it may surprise readers how low Australia's (and Germany's) minimum wages are, compared to ours.)
In Australia, there has been something of a crash in mortgage lending. Lending to owner-occupiers was down -7.3% in April from March and down a stunning -12.8% year-on-year. Even lending to investors fell -4.8% in April from March. There are getting more commentary there of "a great house price correction' being underway, targeting a -15% to -20% drop from peak to trough. Negative equity worries are rising.
The UST 10yr yield will start today down -2 bps at 2.94%. A week ago it was at 2.74%. The UST 2-10 rate curve is little-changed at +28 bps and their 1-5 curve is also little-changed at +79 bps. Their 30 day-10yr curve is flatter however at +207 bps. The Australian ten year bond is now at 3.50% and down -3 bps. The China Govt ten year bond is unchanged at 2.82%. And the New Zealand Govt ten year will also start today unchanged at 3.66%. A week ago it was at 3.52%, so a +14 bps rise in seven days.
The NZX50 ended last week with a creditable +3.0% rise in its overall capitalisation, its best week in a long time. But that run of prior weakness means it is now down -1.8% in a month, down-9.7% in a year. F&P Healthcare (FPH, #1) rose +6.6% last week, as did Auckland Airport (AIA, #2). Mainfreight (MFT, #4) rose +8.0%, A2 Milk (ATM, #10) gained +11.9% after being seen as a winner from the US baby formula crisis. Going the other way, E-Road (ERD, #50) crashed another -% last week. Of the sectors we monitor closely, the energy sector is up +3.4% in a week, flat over the past month, but down -5.2% over the last year. Meridian (MEL, #7) was up +8.3% last week and Contact Energy (CEN, #6) up +4.1%. The retirement home sector had a tough week (again). It was down -3.9% last week, and is in a bear market over the past year, dropping more than -20% in that time. A lot of the recent weakness is due to Ryman (RYM, #11) which fell -8.4% last week alone as it was dumped by index funds. But the long-term decline suggests this sector has wider issues for investors, a sharp contrast to the 'goldmine status' it once had.
The price of gold is up +US$2 today from Saturday, now at US$1851/oz.
And oil prices are up +US$1.50 from this time Saturday, now just under US$119/bbl in the US, while the international Brent price is now just under US$121/bbl. That international price was -US$5/bbl lower a week ago. We are now within US$25/bbl of the [brief] 2008 all-time highs. The transition away from fossil fuels is getting an economic boost.
The Kiwi dollar will open today down -½c at just under 65.1 USc. Against the Australian dollar we are unchanged at 90.3 AUc. Against the euro we are also unchanged at 60.7 euro cents. That all means our TWI-5 starts today at 71.9 and little-changed in a week.
The bitcoin price has risen by +1.5% and is now at US$29,958. Volatility over the past 24 hours has been modest at +/- 1.0%.
It is a public holiday in New Zealand today. Markets are closed.

The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.