
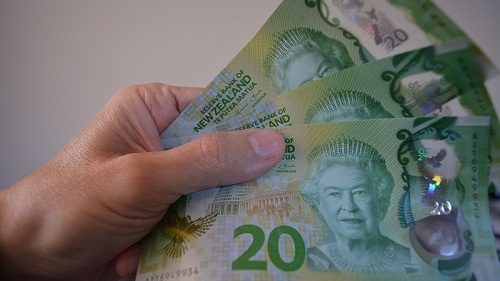
The Reserve Bank is mulling the possibility of a "single provider" of cash in this country in the future, perhaps through something like a private-public partnership, Assistant Governor Christian Hawkesby says.
Hawkesby was sharing some of the central bank's thoughts on the future provision and use of cash in a speech to the Royal Numismatic Society of New Zealand, Annual Conference in Wellington.
He said it has become clear that the cash system as it stands "will not be sustainable in a world where cash is used less and less".
"This requires a broader response with either a series of changes to the cash system or a transformational redesign of the entire system."
He didn't go into further detail on how the "single provider" system might work, or a timeframe for when such a thing may become a reality.
With the rapidly declining usage of physical cash, the RBNZ has been doing a lot of work on the subject through its Future of Cash programme including the issue last year of a consultation document, in which the central bank take on a stewardship role in the cash system, providing system-wide oversight and coordination.
The Reserve Bank has historically been responsible for issuing bank notes and coins on demand. This meant issuing cash to banks, collecting unfit cash, and processing, storing or destroying the cash that is returned to us. The remainder of the cash system, i.e. the banks’ distribution of cash to the public and the transportation of cash to and from retailers has been in the words of the RBNZ "held together by a set of informal arrangements and commercial incentives".
The proposal for the RBNZ to act as "the steward of cash and the cash system" has been included in the recently introduced Reserve Bank Bill.
Taking care of money
"Stewardship is defined as 'the act of taking care of or managing something'," Hawkesby said.
"For us this means ensuring that New Zealand has a cash system where people can easily withdraw, deposit and pay with cash when they need to, and the cash system remains efficient and resilient to sudden shocks and a declining transactional use of cash."
The RBNZ recently created a new department called Money and Cash - Tari Moni Whai Take.
"Te reo Māori version of the name sums up its purpose nicely, 'the department bringing money that’s fit for purpose'", Hawkesby said.
"This department is now responsible not only for the production and distribution of bank notes and coins, but also evaluating the broader policy issues associated with the future of money in New Zealand. Accompanying this, we are planning to establish a new governor-level Payments and Currencies Committee, responsible for strategic, policy and oversight decisions for our roles as an issuer of currency, operator of payments and settlement systems, and steward of the cash system."
Hawkesby said the RBNZ was continuing to engage with the public and industry, including on "system-level information and resilience needs".
Developing standards
"We are also formalising and embedding the distributed vaulting arrangements deployed during Covid-19. Alongside this, we will be working with industry to develop standards for banknote processing machines to ensure the authenticity and quality of our notes."
However, it had become clear that the cash system as it stands would not be sustainable.
The RBNZ would therefore "undertake a holistic and strategic review of the cash system".
"The objective of the review will be to ensure that the physical and business arrangements for cash distribution are efficient, resilient, lower carbon and set up to meet the public’s needs now and into the future. The review will also take into account the public benefits and the increasing costs and efficiency challenges of providing cash," Hawkesby said.
"One option to ensure that cash is available for the long-term might be concentrating cash services in a single provider.
"For example, the end-to-end cash infrastructure could be provided by an industry monopoly model.
'Private-public-partnership'
"Alternatively, a private-public-partnership as seen in some parts of the water, transport and electricity industries could be used. Such a model would recognise the public case for cash."
Hawkesby reiterated that Covid-19 had also highlighted the important role that cash plays in times of economic uncertainty.
"During the weeks leading up to the March 25 pandemic lockdown, New Zealanders demanded an unprecedented amount of cash, with $800 million of bank notes issued in March alone (compared to $150 million in March 2019).
"These bank notes have not yet returned to the banking system, meaning they are likely still being held by the public."
Hawkesby said since then, cash in circulation had continued to increase, growing by about 15% year on year during the second quarter of 2020.
"Many other countries have also experienced increased demand for bank notes during the pandemic, as a store of value and a back up method of payment.

"It is not unusual for cash holdings to increase during periods of uncertainty. In the lead up to the year 2000 wide-spread uncertainty of potential computing failures (the so-called “Y2K bug”) resulted in a sharp increase in cash in circulation (quarterly). Similarly, economic uncertainty during the financial crisis over 2008 - 2009 resulted in a rise in cash in circulation. Smaller increases in cash holdings can also be seen with regional events such as the 2011 Canterbury earthquakes."
Digital currencies
Hawkesby's speech also made reference to digital currencies and the potential for central bank digital currencies (CBDC).
The Bank for International Settlements (BIS), which is owned by 62 central banks, including the RBNZ, recently issued a report in conjunction with seven of the heavyweight central banks identifying the foundational principles necessary for any publicly available CBDCs to help central banks meet their public policy objectives.
The RBNZ has looked at the question of digital currency.
In his speech, Hawkesby said ultimately, the catalysts for researching CBDC depend on local needs.
"Central banks in economies with declining use of, and access to, cash are considering whether a CBDC could deliver an additional form of legal tender. For example, in Sweden, the Riksbank is considering an e-krona as a digital complement to cash given the decline of cash in circulation.
'Stepping stone'
"Conversely, central banks in economies with a heavily reliance on cash are investigating the potential for CBDC’s as a stepping stone to help the unbanked population move into the formal banking sector. A CBDC could improve financial inclusion, particularly if it is established with a government-led digital identity scheme. For example, the Central Bank of the Bahamas has launched a CBDC pilot called “Project Sand Dollar” with the goal of increasing financial inclusion across the islands in the Bahamas, where many people rely on cash but face difficulties accessing bank branches.
"Further, in the case that a foreign-issued or privately-issued currency became prevalent, a CBDC could enable a central bank to retain monetary sovereignty and price stability."
And the case in New Zealand?
"To be clear, we have no immediate plans to launch a CBDC in New Zealand," Hawkesby said.
"We are, however, following developments very carefully, and are among the 80% of central banks that are actively researching CBDCs."
Hawkesby made no reference to the recent stated intention of a new Auckland-based financial services company P^werFinance to launch what it is styling as a "world first" digital version of the New Zealand dollar early next year.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.