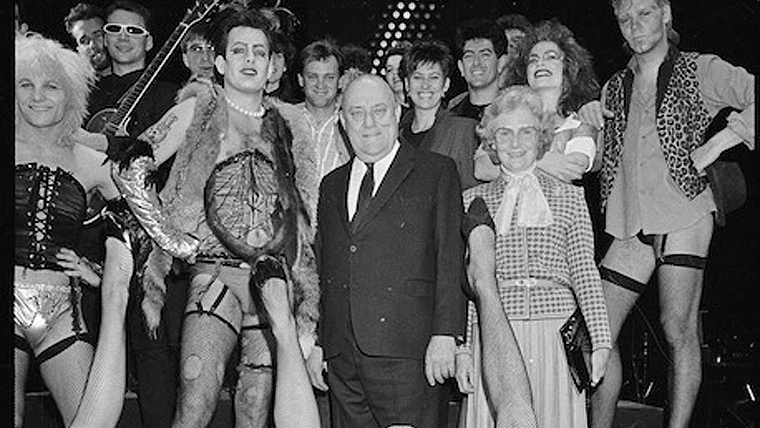
By Andrew Coleman*
Fifty years ago, the Labour government passed the New Zealand Superannuation Act (1974) and introduced a contributory saving scheme. Shortly afterwards the National Government led by Robert Muldoon revoked the Act and replaced it with a new universal retirement income scheme which evolved into the scheme we now have, New Zealand Superannuation. This scheme provides a universal pension to all New Zealanders over 65 who satisfy eligibility criteria, funded from general tax revenues.
Despite some very good features New Zealand Superannuation has three major downsides. Most importantly, it imposes very high costs on current and future generations of young people, who are required to pay much more in taxes than is necessary to provide the pensions they will receive. It means New Zealand eschews some of the most efficient taxes used around the world, particularly social security taxes or contributions to compulsory savings schemes, but relies on taxes that artificially distort investment decisions and inflate property prices. Finally, it unnecessarily exacerbates inequality across the wider community even as it reduces inequality amongst older people. Throughout this series I have argued that many of these flaws could be addressed without reducing the benefits New Zealand Superannuation provides.
Muldoon had a follow up career as the narrator in the Rocky Horror Picture Show, where he won accolades for his performance of the “Time Warp.” This seems very apt when it comes to retirement income policy, as we seem stuck in a time warp of our own that dates back to the 1970s and 1980s. The world has moved on and yet we have been unwilling to reconsider the policies adopted back then.
Just as an example, none of the three major tax reviews held this century analysed the case for social security taxes or a compulsory saving scheme, even though this is the single biggest difference between our retirement and tax system and the retirement and tax systems in the countries in the rest of the OECD. In the third decade of the 21st century it must surely be time to reconsider whether the politicians of the 20th century got everything perfectly correct. The world has changed considerably in the last 50 years, and it is quite probable that a scheme designed in the second half of the 20th century no longer perfectly suits the way people live in the 21st century. It is long past the time to be concerned that change should be avoided because it may involve a jump to the left or a step to the right.
This series has had four broad objectives. The first objective is to outline why the current system needs changing. The paper has focussed on three issues – taxation, inequality, and the opportunity cost of pay-as-you-go retirement income schemes – and argued that the current system generates adverse consequences for many young people, as well as for the economy overall. Young people may be paying twice as much as they need to pay for the pensions they will receive. Whatever one thinks about reform proposals, the problems associated with the current system are real and should not be swept under the table.
Secondly, the series has made some suggestions outlines the possible choices younger cohorts could make. Last week I outlined one possible set of reforms, KiwiSaver 2.1, that would likely reduce many of the problems with the current system, while keeping many of its advantages. KiwiSaver 2.1 is compulsory saving scheme designed to replace New Zealand Superannuation for the first few years of a person’s retirement, and accumulate surplus funds for the rest. It would allow income taxes to be reduced, and it would reduce the overall cost of the retirement income scheme by taking advantage of investment opportunities. It can be designed so that older people get benefits at least as large as the current system, while reducing inequality in the broader community. It should reduce the way that the tax system artificially inflates house prices, and it is even likely to be good for the planet, to the extent that the savings it generates are invested in the type of environment-enhancing projects that many foreign pension schemes favour.
This is just one suggestion, but the more general point is that the current goals of New Zealand Superannuation plus more can be achieved at lower cost by doing things differently. There is simply no need to believe that a scheme designed for the conditions prevailing in the 1970s is still the scheme best suited to the needs of younger people.
The third objective has been to open a discussion about the plurality of policy choices in a country. Democracies allow people to choose the policies they like, but this does not mean all people must have the same policies. Since people cannot change when they were born, it is straightforward to design age-specific policies that allow different generations to achieve the goals they desire. These policies can be designed in an intergenerationally neutral manner that makes them straightforward to change as the outcomes different generations want change. The contrast with New Zealand Superannuation, which imposes increasingly larger costs on younger and future generations, is striking. Young generations should not be obliged to have the same policies as their parents and grandparents, unless that is what they want, particularly if the policies they inherent are particularly costly to themselves.
The fourth objective is to discuss the transition issue and show that it can be manageable, but not costless. Some of the changes to the retirement income system that I have discussed could be made with relatively few direct effects on older people. For example, younger people could have KiwiSaver accounts taxed on an EET (Exempt, Exempt, Tax) basis rather than a TTE (Taxed, Taxed, Exempt) basis without needing to change much at all for older New Zealanders.
However, other changes would require an increase in the costs that older people face during a transitory period. If New Zealand were to adopt more save-as-you-go funding of one type or another (for example, the adoption of the KiwiSaver 2.1 proposal, or additional taxes that contribute greater amounts to the New Zealand Superannuation Fund) there would need to be additional costs for people over 50 to help reduce the costs on younger people. Fortunately, survey evidence suggests there is considerable willingness to share the burden more evenly.
In this series I have made several suggestions about the ways retirement incomes and tax policies could be reformed. If you don’t like these, there are others. Many rich countries such as Norway, Sweden or Germany already use quite different retirement and tax systems that collect more taxes than New Zealand – but because they consciously design taxes to reduce their distortionary effects, they do it in ways which keep incomes high, and which generate less inequality than in New Zealand. Often this means they have lower income taxes than New Zealand.
The key requirement for progress is the willingness to discuss the issue and find a solution. If New Zealand doesn’t do something sooner, it will have to do something bigger at a later date. If these discussions are not held now, and current pension entitlements are maintained, young people will face higher and higher taxes. Young people might choose to pay higher taxes in the future to maintain current pension payments – or they could choose to reduce the pensions older people receive, or leave to countries where the balance between taxes paid and benefits received is more favourable. None of these possibilities are very attractive.
If you have been reading over the last three months, you will know I have repeatedly argued that it is New Zealanders aged less than 45 who should consider a fundamental restructure of New Zealand’s government retirement income system and its associated taxes. The dividing age does not need to be 45, but nobody under 45 voted in the 1997 referendum that ensured New Zealand has the most unusual retirement system in the world, and these New Zealanders have spent and will spend their entire working lives in the 21st century. If they don’t want to use a retirement income system designed in the 20th century, it should be up to them to say so. Those of us over 45 should encourage them to take the initiative.
This is the last article: I hope you have enjoyed them, or at least found them stimulating. Most of these ideas are based on a series of research papers I have written over the last 15 years that are expressly about New Zealand. The ideas are all inspired by and informed the thinkings and experiences of overseas countries. They are the result of a lot of discussions and boozy sessions with (bored??) colleagues and friends at Motu Economics, the New Zealand Treasury, the New Zealand Productivity Commission, the University of Otago, Al-Akhawayn University, the Asia School of Business, and the Reserve Bank of New Zealand (which remains “unresponsible” for any of this work).
I would particularly like to thank Gareth Vaughan from interest.co.nz, who made this series possible, James Weir, Jeanne-Marie Bonnet, Naeem Sheikh, Clive Thorp, and Anthea Coleman; but thanks also to all who commented in the comments sections and gave me pause for thought. I am looking forward to the forthcoming debates and hope they will be led by New Zealand’s current and future citizens and leaders in an engaging and constructive manner.
*This series and an accompanying paper are based on work I started in 2020 with Jeanne-Marie Bonnet while we were both at the University of Otago. I am very grateful for her assistance and insights. All errors remain my own.
(This article is the 13th and final one in this series. You can find all other articles in the series here).
**Andrew Coleman is a visiting professor at the Asia School of Business. This article is his personal view of retirement policy in New Zealand, based on academic study.
Coleman is on extended leave from the Reserve Bank of New Zealand, while working overseas. The views expressed in this article do not represent the RBNZ and are unrelated to work conducted at the Bank, which has no responsibility for retirement policy in New Zealand.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.