By Andrew Coleman*
In 1974, the Labour government led by Norman Kirk introduced a compulsory saving scheme. Two years later it was scrapped and replaced by an early version of the current retirement scheme, National Superannuation. As a result of this decision, New Zealand now has the most unusual retirement income and tax policies in the OECD.
If these policies were better than those used in other countries, this would be fine. But this might not be the case. Despite some very good features, our policies have three major problems. They impose high costs on current and future generations of young people, who are required to pay much more in taxes than is necessary to provide the pensions they will receive. They mean New Zealand relies on some inefficient taxes that artificially distort investment decisions and inflate property prices. And they exacerbate some dimensions of inequality.
To mark the 50th anniversary of the compulsory saving scheme, this series of articles re-examines whether New Zealand’s retirement income policies are suited to the 21st century. If not, it may be time to redesign aspects of the system, particularly for those younger New Zealanders who have inherited policies they had no role in creating. We will begin by looking at the history of retirement income systems in New Zealand and around the world.
Mandatory retirement income schemes come in two main types. The first type is a social insurance or contributory system, which includes compulsory saving schemes. These schemes are designed to help people save for their own retirements by making them put money aside when they are young and middle-aged. Contributory schemes are funded from special social security taxes on wages and salaries, while compulsory saving schemes are funded by placing a fraction of a person’s wages or salaries into a personal saving account. The government keeps track of each person’s contributions and bases their pension on this total. Since these schemes are designed to help people save, people who make larger contributions get larger pensions when they are old.
The second type is a welfare system. These retirement income schemes are designed to provide older people with a minimum income level to keep them out of poverty. They are funded out of general tax revenues and the size of the pension people receive is unrelated to their tax payments. Welfare pensions can be universal, so everyone gets the same pension, or they can be means-tested. If they are means-tested high-income or wealthy people receive a smaller amount, or even nothing.
In addition to these mandatory schemes, many governments also have voluntary saving schemes like KiwiSaver, designed to make it easier for people to save for their old age, but without compulsion.
The first contributary scheme was introduced in Germany in 1889, and the first welfare scheme was introduced in Denmark in 1891. Other countries followed suit, typically with one system or the other. These systems evolved over time as the advantages and disadvantages of both types of systems became apparent. They also became much larger in the 1950s and 1960s as life expectancy increased. By the end of the 1960s, most developed countries adopted a hybrid system based on (i) a contributory or social insurance model to help people save for retirement and (ii) a welfare model to ensure low-income people have adequate income when they retire. New Zealand is quite different to the rest of the world because it only has a universal welfare-based pension scheme.
New Zealand created a welfare-based government pension plan in 1898, funded out of general tax revenues. These pensions were available to most people over 65 of “good moral character” who had spent at least 25 years in New Zealand, although they were not initially available to Chinese immigrants. The pension was small, £18 per year (or about $4300 today) when average wages were £75 per year for men, and £30 for women. It was stringently income- and asset-tested. People who earned more than £34 had their pension reduced one-for-one when they earned extra money, so anyone earning over £52 received nothing. The aim was to give money to people who had no other means of support, rather than to help people save for their old age.
The “Age Benefit” pension was modified between 1898 and 1938 by increasing its size, by reducing the eligibility age for women to 60, and by including Chinese New Zealanders. But it was still designed to provide welfare for low-income people and the means-test remained central.
Several changes were made in 1938 by the Labour government headed by Michael Savage. The rate was increased, the age for the means-tested “Age Benefit” pension was reduced to 60 for men as well as women and a second “contributory” pension was introduced for people over 65. This “contributory” pension was the same for everyone, and while it was initially much smaller than the “Age Benefit” pension, it was meant to increase over time until it was the same amount. The new over-65 pension was funded by a social security tax on wages and salaries and was not means-tested. This was an unusual scheme because people paid social security taxes but the amount of the “contributory” pension they received did not depend on the taxes they paid. The contributory pension steadily increased in the 1950s as planned but the separate Social Security tax was abolished in 1958 and payments were funded from general tax revenues.
There were two major changes in the 1970s. A Labour government introduced a proper compulsory contribution scheme in 1974, in conjunction with the existing pension scheme. The contributions were 8% of income, paid for by employees and employers. This was a true contributory scheme as the payments were only levied on labour income and the size of an individual’s pension depended on the size of their contributions. This is broadly consistent with what was happening in other countries where the pension systems were converging to a mixed welfare and contributory scheme.
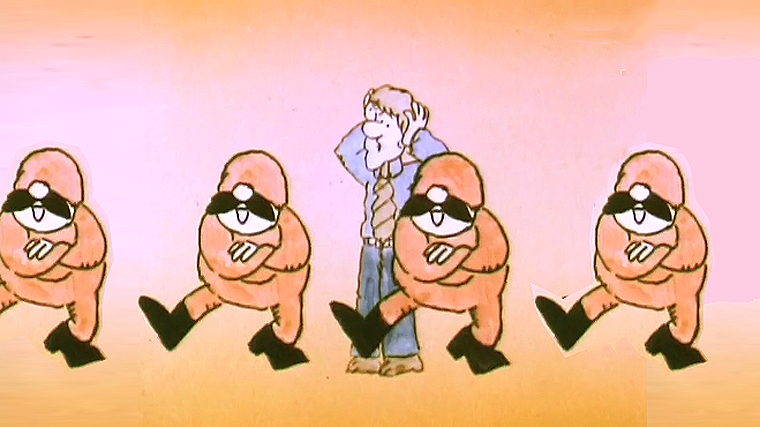
It did not last. In the 1975 election, the National Party led by Robert Muldoon campaigned to abolish the compulsory saving scheme and replace it by a universal, flat-rate pension. The campaign featured New Zealand’s most influential advertising effort ever, featuring the infamous dancing Cossacks. After a landslide victory, the new scheme, National Superannuation, was introduced in 1977. The pension for a couple was increased to 80% of the average wage and made available to everyone over 60. But taxes were not increased, so New Zealand started running large government deficits and the national saving rate dropped sharply.
It soon became obvious that the scheme could not persist without higher taxes. Successive governments cut back the scheme by decreasing the pension and by imposing surcharges to reduce payments for higher income people. These changes became increasingly complicated, and the surcharges were abolished in 1988. More changes followed in the early 1990s. The pension age was gradually increased to 65, and strict means-tests were imposed. Many of these changes caused considerable political backlash, and means-testing was abolished.
In 1997 a referendum was held, giving voters the option to choose a compulsory retirement scheme like the one Australia had just introduced. It was rejected by over 90% of voters and that was that. It meant New Zealand entered the 21st century with a retirement income scheme almost identical to the 1977 scheme, although less generous: a universal pension provided to all New Zealanders over 65 who satisfy eligibility criteria, funded from general tax revenues.
Since 2000 there have been two new features. The New Zealand Superannuation Fund was established in 2001 to finance some of the expected future costs of New Zealand Superannuation. The Fund allows the government to “bank” additional tax revenues to pay part of the future pension bill. The Fund was over $60 billion by the end of 2023, in part due to excellent investment returns.
In 2007 a voluntary saving scheme, KiwiSaver, was introduced to help people save by getting them to regularly place a small proportion of their wages into a saving account that, with a few exceptions, cannot be accessed until 65. It does not affect a person’s entitlement to the government pension.
All this means New Zealand started the 21st century much as it started the 20th century – with a non-contributory retirement income system funded from general taxes rather than social security taxes. The current system is much more generous and it is no longer means-tested. But it is still fundamentally a welfare programme not a saving system and this means it is very different to the retirement income systems in other OECD countries. It is what older New Zealanders asked for when they voted to get rid of the contributory scheme in 1975, and when they rejected a compulsory savings scheme in 1997. However, it may not be what New Zealanders under 45 want, for they have never been asked.
New Zealand Superannuation has several attractive features. It also has several serious downsides and these disproportionately affect younger people. The next few articles look at these downsides, to see why a pension scheme based on a mixture of contributory and welfare principles may be more attractive to young people than the scheme they have inherited.
*This series and an accompanying paper are based on work I started in 2020 with Jeanne-Marie Bonnet while we were both at the University of Otago. I am very grateful for her assistance and insights. All errors remain my own. (This article is part 2 in the series. Part 1 is here).
**Andrew Coleman is a visiting professor at the Asia School of Business. This article is his personal view of retirement policy in New Zealand, based on academic study.
Coleman is on extended leave from the Reserve Bank of New Zealand, while working overseas. The views expressed in this article do not represent the RBNZ and are unrelated to work conducted at the Bank, which has no responsibility for retirement policy in New Zealand.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.