
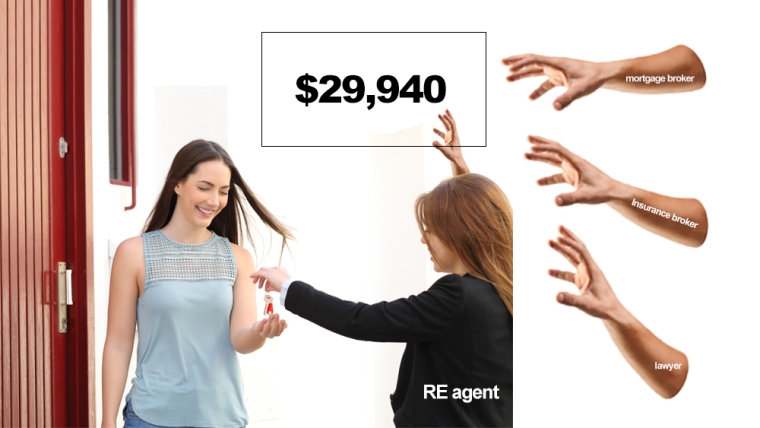
Every time there is a house sale, there is a pool of fees up for grabs.
A range of housing industry 'professionals' stand in line for their payday.
For almost all of them, this is their only chance to earn a living from what they do. If they can generate a regular run of transactions, the living can be good. But without a 'sale' there is nothing.
For them, the transaction is the thing - whether it is good for the buyer or the seller is of lesser concern. Churning transactions makes this 'sales model' work for these 'professionals'.
To give an idea of what is involved, we based our assessment on the New Zealand-wide lower quartile house transaction in December 2024, a $785,000 sale between a willing buyer and a willing seller. We found a number of December transactions in a range of cities that hit that FHB mark, mostly townhouses in Auckland.
And this is how one such transaction spilled out:
| See notes below | $ |
| Cost of house | 785,000 |
| Home loan | 706,500 |
| and that generates fees of ... | |
| Real estate agent commission | 21,550 |
| Mortgage broker commission | 6,005 |
| House insurance commission | 396 |
| Lawyer's fee | 1,990 |
| GST | 4,491 |
| Total "professional fees" | $34,432 |
In addition to these fees, there can also be fees for auctioneers, reimbursement for marketing costs, inspection reports, documentation and title transfer fees, and a range of other possibilities depending on the transaction. The ones in the table above are the minimum.
GST is charged on these fees, so the buyer also pays that. However the brokers don't receive that GST, so the net for them is $29,941.
In our example, these fees are 44% of the buyers deposit.
Of course, the real estate agent will tell the buyer the seller is paying their fee. The mortgage broker tells the borrower that the bank pays their fee. But in reality those costs are not really effectively paid by anyone other than the buyer. They are built in to the industry's cost base, and just like at the supermarket, the margins are extended so that these costs get covered - by the buyer.
And of course, we shouldn't forget Council rates ($1306 per year incl. GST if the above example was in Mt Roskill, Auckland). Perhaps Rates are different in that they cover ongoing services and recur every year. But the base transaction goes into the Rating Valuation mill and that affects everyone.
In an unfortunate irony, virtually no-one actually represent the interests of the buyer. The R/E agent is contracted to represent the sell. The mortgage broker is paid by the bank and is hopelessly conflicted. Ditto the insurance agent. Hopefully the lawyer is on the buyer's side but they come to the transaction right at the last minute.
How our fee table was calculated
1. The house selling price is the New Zealand national December lower quartile price. We used a Mt Roskill townhouse transaction for the detail.
2. We assumed the buyer only had a 10% deposit, a reasonable assumption for a first home buyer.
3. We used the advertised Barfoot & Thompson commission rate, because they are the largest agent in Auckland. But that does not imply that Barfoots actually sold this property.
4. We assumed the borrower used either ANZ or ASB for the loan, the two largest mortgage lenders. That set the mortgage broker commission level at 0.85%.
5. We used an online house-only insurance calculator, and an insurance agent commission of 17.5%. These can actually run between 17.5% and 27.5% in the real world.
6. We used an online quote from a property law specialist.
This exercise is only for illustrative purposes, to give a general sense of what fee pot is available for distribution on each sales transaction. It is probably close to the bottom end. And that is why your real estate agent or mortgage broker, who have no caps on what they can earn under this system (unlike bankers), probably arrived at your meetings in a Audi or Porsche.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.