
Despite recent falls, house prices remain "stretched" for prospective buyers, and are around the top of the Reserve Bank's estimate of "sustainable levels".
The RBNZ makes this comment in an Update on the Housing Market, which will be in the central bank's six-monthly Financial Stability Report coming out on Wednesday next week and has been released early.
The update, authored by RBNZ adviser, financial system analysis, Charles Lilly, says to assess the sustainability of house prices the central bank considers the mortgage servicing costs for a new buyer, both relative to average household incomes, and relative to the alternative option (renting).
"These two indicators rose rapidly as house prices were peaking in late 2021, and they have remained at historically high levels," he said.
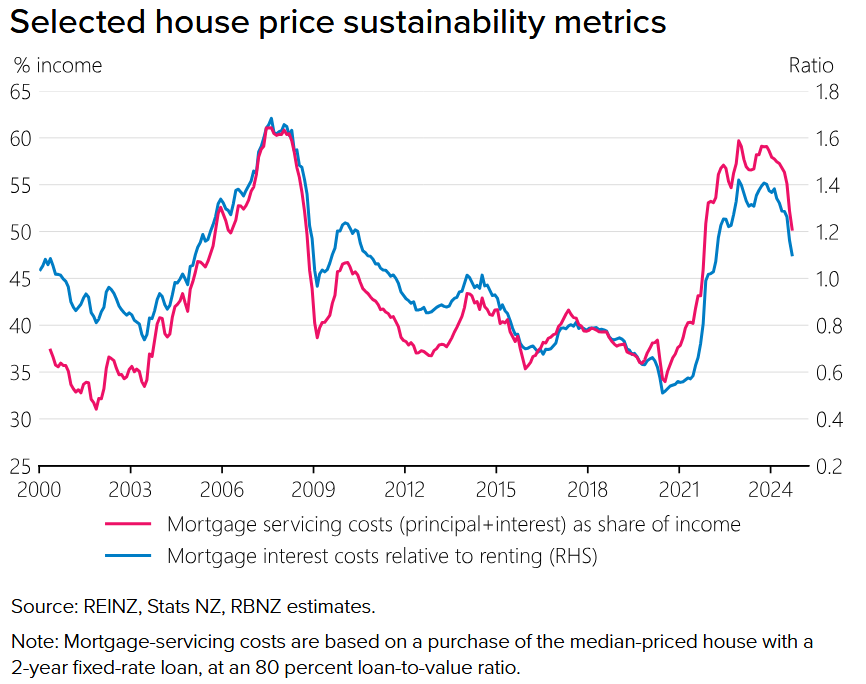
"Overall, our metrics for house price sustainability suggest that current levels are around the top of the indicator range. This assessment is based on interest rates returning to neutral levels," Lilly says.
Comparing New Zealand’s recent house price cycle with overseas, Lilly says our cycle "has been rapid", but with comparatively less financial system stress.
"Debt-servicing stresses are currently elevated and non-performing loans continue to climb. However, New Zealand has not yet seen the same widespread household balance sheet distress experienced in countries with similar house price boom-bust cycles."
He said banks’ lending standards have meant borrowers "have had financial buffers in place to handle shocks".
"Stringent testing of new borrowers’ servicing capacity has meant they have been able to absorb large increases in interest rates. Loan-to- value ratio (LVR) requirements, including speed limits applied by the Reserve Bank, have meant that borrowers can absorb substantial price declines without falling into negative equity."
"We estimate that less than 2% of the current stock of lending is to borrowers in negative equity."
Lilly also noted that house prices were at or near their peak level for only a brief period.
"This meant that a limited proportion of buyers from recent years purchased their properties at prices close to the peak. A prolonged period of purchases at unsustainable prices would have led to a larger accumulation of risk."
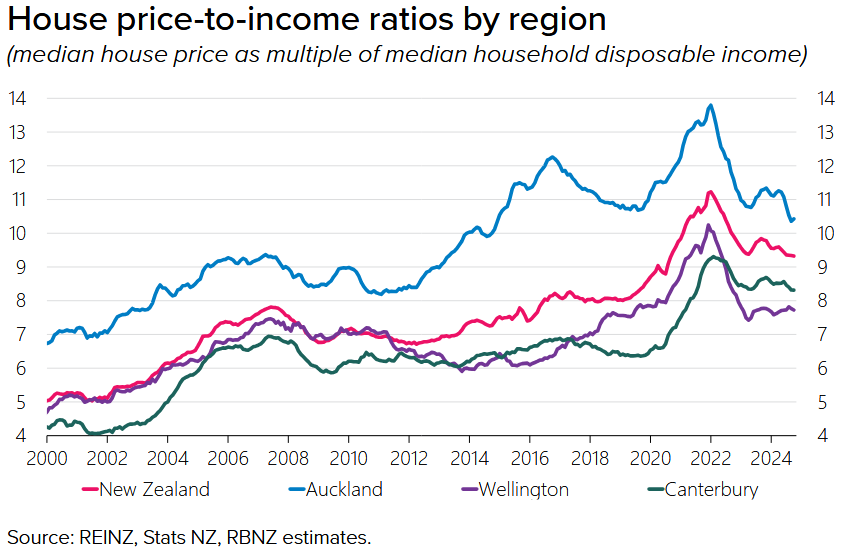
Lilly said from their peak level in late 2021, house prices have fallen an average of 14% nationally, although with significant regional variations.
"Auckland and Wellington prices fell 20% and 23% respectively, and have remained relatively flat over the past year. In contrast, prices in Canterbury experienced only modest declines, and have strengthened over the past 18 months. House price-to-income ratios have declined significantly from their peaks."
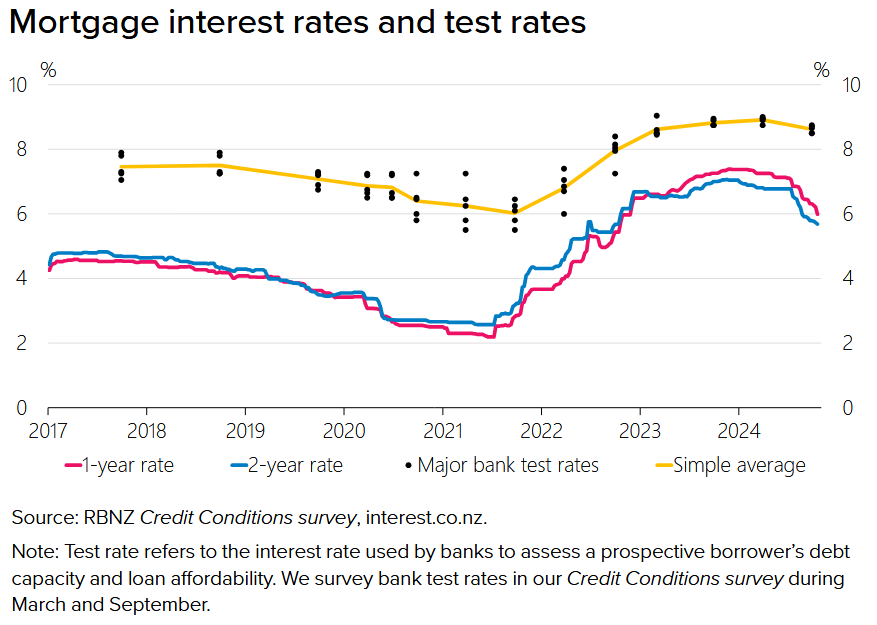
Lilly said advertised mortgage rates have begun to decline over recent months, but they remain at relatively high levels.
"This is continuing to constrain the borrowing capacity of potential homebuyers. The test interest rates that lenders use to assess borrowers’ debt-servicing capacity have fallen, from an average of 9% in mid-2024 to around 8% in October."
"Banks typically apply a buffer above the average of the 1- or 2-year fixed mortgage rate, although there is some variation in methodologies. Banks generally review their test rates on a quarterly basis."
"However, given the rapidly changing interest rate environment, some banks reported that they will review their test rates more frequently."
"Borrowers’ capacity to take on more debt could increase quickly given further easing in monetary policy."
Lilly said that with low overall lending growth, banks are facing "competitive pressures" to attract a limited pool of creditworthy borrowers. The slowdown in New Zealand’s population growth due to falling net migration is also dampening housing demand.
He said investor activity remains weak, "but may pick up following tax policy changes".
He notes that the deductibility of mortgage interest costs from taxable rental income will increase to 100% in April 2025, from 80% currently.
"Deductibility improves investors’ debt- servicing capacity and will increase investors’ valuations of existing properties."
Since July, the ‘bright-line’ period for assessing the taxable status of capital gains on investment property has been reduced to two years from 10 years.
"This change could increase speculative housing purchases, at the margin.
"In the short term, the change means that investors facing cash flow pressures from high interest rates may seek to sell properties they had been holding on to, due to the previous longer bright-line periods that applied."
Lilly noted that the annual number of new dwelling consents has fallen from its high of 51,000 in 2022 to around 34,000.
"This remains substantially above the level that consents fell to following the Global Financial Crisis (GFC), and is closer to a level that the construction industry can deliver on a long- term basis."
He said the large pipeline of consents from recent years continues to convert into completed houses.
"Industry contacts reported a potential glut of new townhouses in Auckland in recent months, given currently weak demand. A material share of the current property listings in Auckland and Canterbury are new build properties."
He said, however, that "prudent lending standards by banks" through the boom period mean that any surplus supply of new builds is unlikely to lead to material loan losses for them.
"Typically banks have required that the value of presales covers at least 100% of any borrowings.
"However, some non-bank lenders that provided additional financing, subordinated to the banks’ financing, may take some losses.
"Developers with unsold stock may also face equity losses if they are unable to achieve their desired prices."
Banks and industry contacts have reported that presales of new builds have been weak.
"Buyers in the current market have the option of purchasing completed new builds, rather than committing to lengthy waits for developers to build off the plans."
Lilly said banks have now generally eased their presale requirements for "high-quality developers who have established track records", to around 70% of borrowings.
"Banks want to maintain market share, and feel a competitive pressure to build back up their lending portfolios as projects complete and existing loans are repaid.
"The Government has announced an underwriting initiative to support new developments given the weakness in presales.
"The slowdown in the development pipeline, combined with some financial stresses among developers, has seen many firms exit the industry.
"Although this is to be expected at the end of a development cycle, a large drop in industry capacity would impair supply responsiveness to future increases in demand."
Lilly noted that in July 2024 the RBNZ had activated limits on banks’ high debt-to-income (DTI) mortgage lending.
Under the rules, banks can lend no more than:
• 20% of new owner-occupier lending to borrowers with DTI ratios greater than 6, and
• 20% of new investor lending to borrowers with DTI ratios greater than 7.
Lilly said DTI limits will act as "guardrails" on banks’ lending without needing the RBNZ to regularly adjust the limits.
"If interest rates decline, borrowers’ DTIs are likely to trend up, and the policy setting will effectively become tighter. This provides an offset against the potential build-up of financial stability risks."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.