
There's one thing better than a bold decision. And that's a bold decision that appears vindicated.
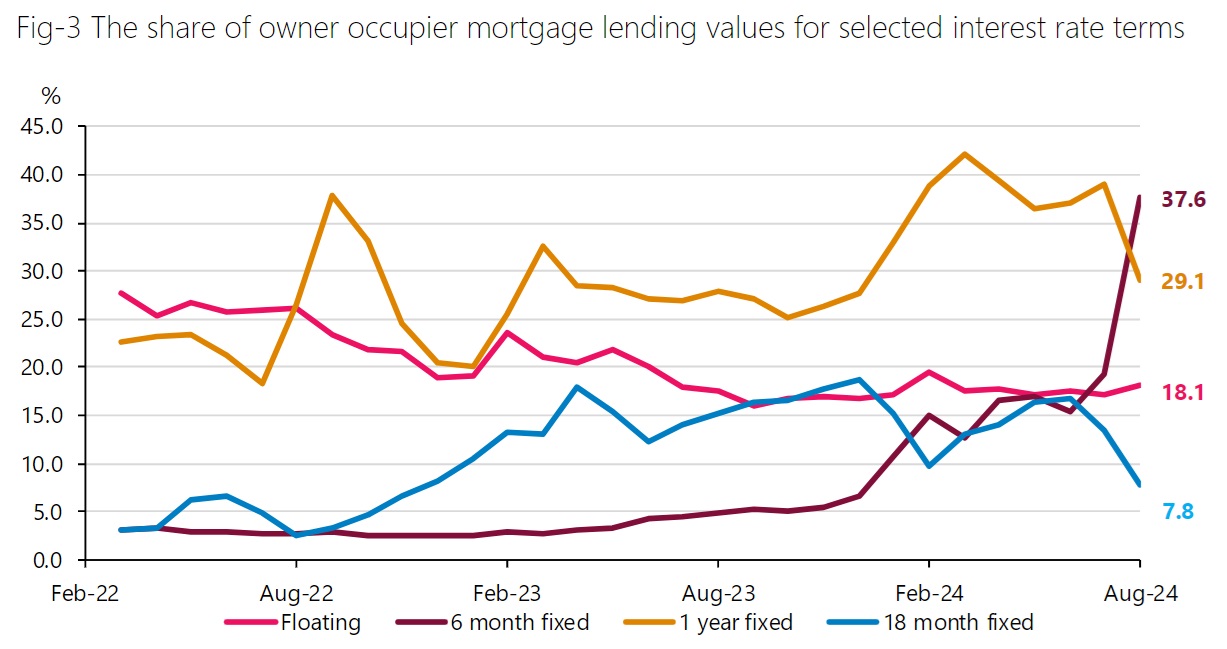
Contrary to my expectations when reviewing July mortgage figures, the move to ever shorter fixed terms for mortgages not only continued in August but soared, explosively, to new heights - to the point where the perennially popular one-year fixed mortgages were overtaken with six month fixed mortgages becoming most popular for the first time.
The Reserve Bank, in its latest monthly figures says that 37.6% of new mortgages taken up by owner occupiers during August were for a six month term.
The investors have been even bolder than that. Some 43.8% of investor new mortgage money during August was for six months.
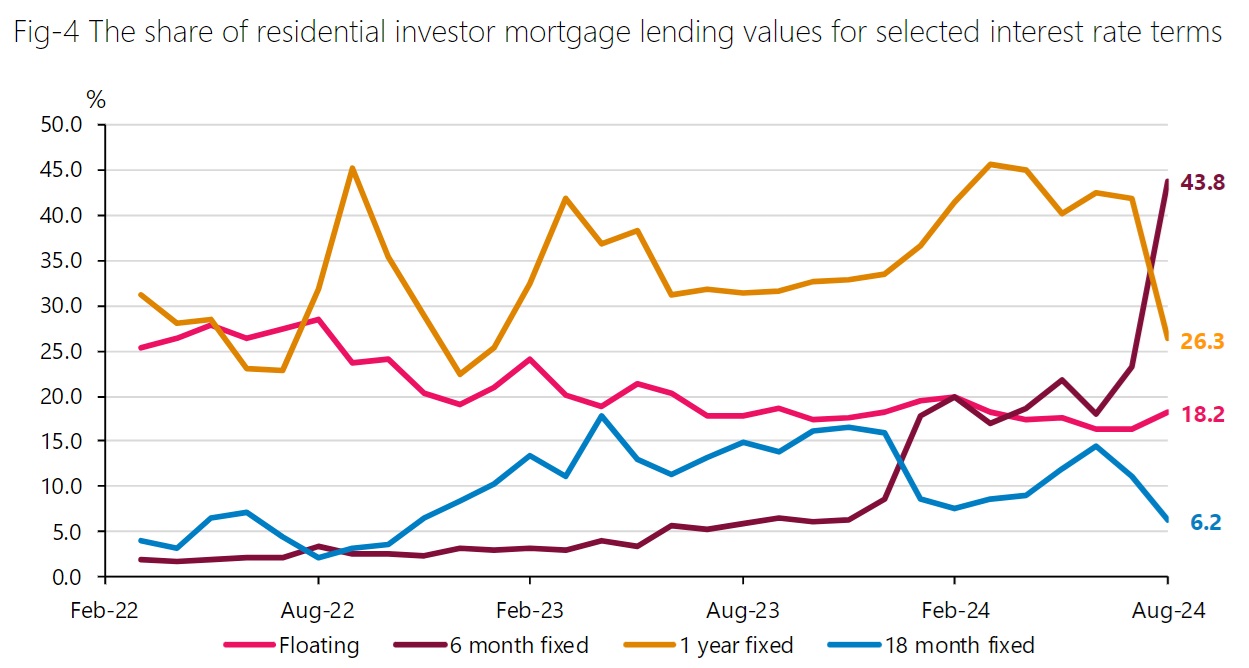
And yes, these figures are very much records for this data series - notwithstanding that the series dates back only to 2021. But clearly, it would be a very long time since people went this 'short' with their mortgages - and I would be reasonably happy to say they probably never have gone quite this short in terms of actual fixed rates. There was, however, a period in 2011-13 when far more money was actually on floating rates rather than fixed.
The significant thing about this data series is that unlike other monthly RBNZ series capturing mortgage information, this one records mortgage details as per when the mortgage is physically drawn down as opposed to when it is committed to.
So, for people to be drawing down mortgages in August on a six month term, there has to have been some good anticipation on the part of at least some on what the Reserve Bank was going to do. On August 14 the RBNZ dropped the Official Cash Rate from the 5.5% it had been on since May 2023 to 5.25%.
Mind you, people would have been helped in their anticipation by the fact that mortgage rates themselves were already heading down before that first OCR cut. But anyway, with at least 25 basis points more of cuts to the OCR expected this week, and more to come before the end of the year, anybody who took the six month option in August and who will therefore now be looking at refixing their mortgage in around February, is probably feeling justified.
In terms of the total sum of money that was drawn down in mortgages during August, it was $6.841 billion. Of that, $1.27 billion was on floating rates, while the investors and the owner-occupiers together took out $2.639 billion worth of six-month fixed rate mortgages. Add the floating and six month totals together and it means that some 57% of the new mortgage money drawn down can be reset by February. That's a big percentage.
To put some historical perspective on these figures, just a year ago in August 2023 the owner occupiers took out only $208 million of six month mortgages, which made up a mere 4.8% of the $4.347 billion of owner-occupier mortgage money.
The $75 million of six-month mortgages taken up by investors in August 2023 made up just 5.9% of the investor total of $1.266 billion then.
And yes, a swing to popularity for one thing, means a swing away from others. In August 2023 owner occupiers and investors together took out $1.206 billion of mortgages fixed for two years, which was over a fifth of the $5.699 total in that month.
A year on, in August 2024, a paltry $230 million worth of mortgage money was taken up for two-year terms. That's just 3.4% of the $6.841 billion total. And yes, that's a record low.
But as we've seen these things are obviously cyclical. I say again that I've been impressed by the keen way the country's mortgage customers have keenly tracked what's likely to happen with official interest rates. And they've got themselves, it seems, ahead of the game.
I reckon that refixing decision in February might be a bit harder though.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.