
More banks are falling into line now with 25 basis points (bps) rate cuts. ASB is the latest, and that now more or less completes the current phase of mortgage rate reductions.
The ASB change has two interesting features; first, it now offers the lowest six month rate of any bank, at 6.99%.
And second, it now reprises a sub-6% rate, offering 5.99% fixed for five years.
The last time any bank offered a fixed home loan rate below 6% was Heartland's three year fixed 5.95% in June 2023. For the majors, it was Kiwibank's 5.85% one year fixed offer ending December 12, 2022. So, it's been a while.
ASB has also chiselled away at its term deposit rates as well.
TSB also trimmed some rates. And it has matched ASB with a 6.99% six month offer.
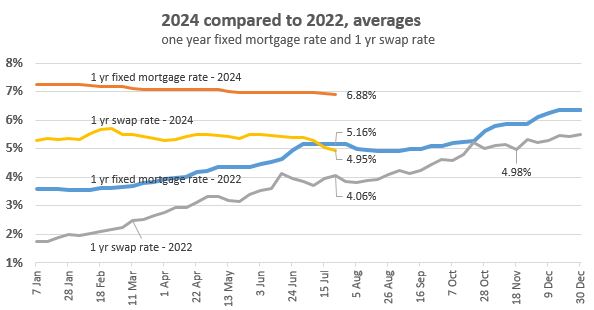
In a step back, we can note that since the last no-change Reserve Bank (RBNZ) Monetary Policy Review, the one year swap rate has fallen 34 bps. And that is more than the 25 bps cuts to mortgage and term deposit rates that are flowing through.
So without any RBNZ moves, other than a subtle signal via a slight change of wording, the market is charging lower and starting to price in not only a rate cut at the full MPS on August 14, but another at the review on October 9. But remember, market pricing signals are not infallible; they are always fluid and data, especially inflation data, have a major influence on these 'bets'.
Now the one year swap rate is back to where it was at the end of November 2022 (just prior to the RBNZ Official Cash Rate (OCR) hike on November 23, 2022, when the OCR was hiked +75 bps).
At that time in November 2022, most main banks were offering 5.99% one year fixed mortgage rates. Kiwibank was at 5.89%; Heartland was at 5.49%.
Now the rate trajectory is lower, from a higher starting point. Here is how 2024 looks like about July 20, compared to 2022, as that swap rate sinks:
But it is still Heartland Bank's 20 bps cut that gives it the lowest position of any bank for all the terms they offer; 12, 18, 24 and 36 months fixed,
Having noted that, we should also note that Heartland Bank's offer is online only. As such, there is no wiggle-room for negotiation with them. And brokers don't get paid by Heartland so there is no incentive for them to offer you these rates. You would have to go direct via their online process.
But almost all other banks will have some flexibility in their rate offers. So the carded rates are just the start. Negotiate. How flexible they may be will depend on the strength of your financials. And don't forget, banks have savvy tools at hand to 'know' the likely valuation of your property, so if the LVR is near 80% you may not find them very accommodating for a lower rate. With falling house prices, the point where low equity premiums start applying is shifting around as well. Beware.
And the carded rates we report here can be different to the rates banks might offer in their banking app. We would like readers to reveal what their banking app shows as the potential offer rates. Please add that market intelligence in the comment section below.
A quick check of the wholesale swap rate chart below gives a clear understanding of where funding costs are heading.
One useful way to make sense of the changed home loan rates is to use our full-function mortgage calculator which is below. Term deposit rates can be assessed using this calculator.
And if you already have a fixed term mortgage that is not up for renewal at this time, our break fee calculator may help you assess your options. Break fees will be minimal in a rising market. But they become important in a falling market.
Here is the updated snapshot of the lowest advertised fixed-term mortgage rates on offer from the key retail banks at the moment. Updated with Kiwibank changes effective Monday.
| Fixed, below 80% LVR | 6 mths | 1 yr | 18 mth | 2 yrs | 3 yrs | 4 yrs | 5 yrs |
| as at July 22, 2024 | % | % | % | % | % | % | % |
| ANZ | 7.05 | 6.85 | 6.69 | 6.49 | 6.35 | 7.14 | 7.14 |
 |
6.99 -0.25 |
6.85 -0.26 |
6.69 -0.20 |
6.49 -0.26 |
6.35 -0.04 |
6.29 -0.10 |
5.99 -0.30 |
 |
7.05 | 6.85 | 6.65 | 6.49 | 6.39 | 6.39 | 6.39 |
 |
7.05 | 6.85 | 6.49 | 6.39 | 6.39 | 6.39 | |
 |
7.05 | 6.89 | 6.79 | 6.75 | 6.39 | 6.39 | 6.39 |
| Bank of China | 7.05 | 6.85 | 6.75 | 6.49 | 6.29 | 6.29 | 6.29 |
| China Construction Bank | 7.19 | 7.09 | 6.89 | 6.75 | 6.49 | 6.40 | 6.40 |
| Co-operative Bank | 7.05 | 6.79 | 6.69 | 6.49 | 6.35 | 6.35 | 6.35 |
| Heartland Bank | 6.69 | 6.49 | 6.35 | 6.15 | |||
| ICBC | 7.19 | 7.05 | 6.79 | 6.69 | 6.59 | 6.49 | 6.49 |
 |
7.24 | 7.14 | 6.89 | 6.49 | 6.35 | 6.19 | 6.19 |
 |
6.99 -0.30 |
6.85 -0.14 |
6.89 -0.30 |
6.49 -0.26 |
6.39 -0.26 |
6.39 -0.20 |
6.39 -0.20 |
Fixed mortgage rates
Select chart tabs
Daily swap rates
Select chart tabs
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.