
The rush for ever-shorter fixed rate mortgage terms has continued in earnest.
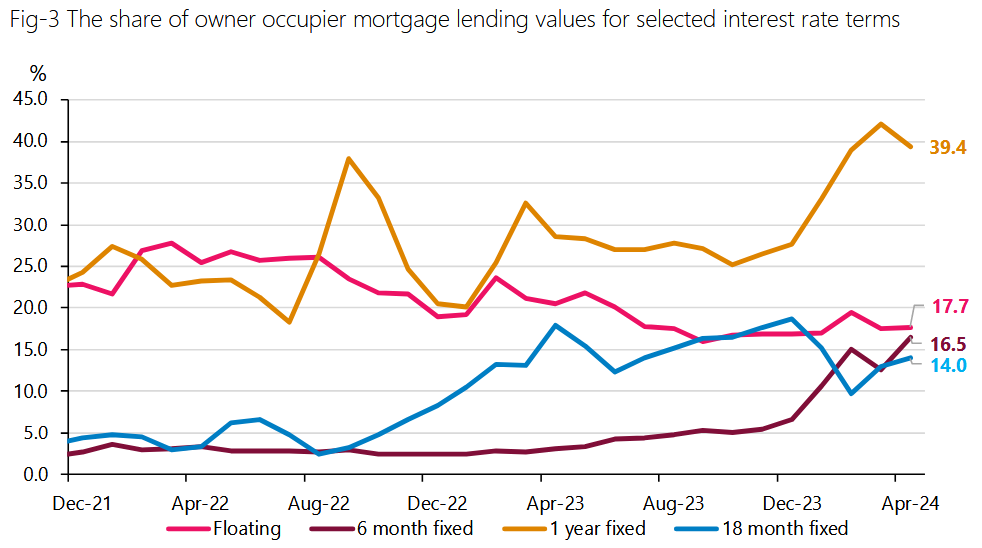
Latest monthly figures - these for April - show that some 73.6% of the new mortgage money taken out by owner-occupiers (including on floating rates) was fixed for a year or a shorter term.
This continues the stampede to shorter fixed rate terms that started at the beginning of the year and has only picked up pace since. People are picking that interest rates will go down sooner rather than later. Are they going to be disappointed? (Spoiler alert: The Reserve Bank's suggesting that they might be.)
The Reserve Bank (RBNZ) introduced the C71 data series, which details mortgages as they are actually drawn down and for what terms they are fixed for last year. It only goes back as far as 2021, but offers interesting insight into what the borrowers are thinking - and also shows to some extent what offers the banks have been pushing at various times.
In April 2024 owner-occupiers took out $4.683 billion worth of mortgages.
A stand out in those April figures is the fact that the amount of mortgage money fixed by owner-occupiers for just a six month term has hit a new high (albeit in a short-run data series, just three years) of 16.5%. Till this year the six-month terms have hardly featured as something the owner-occupiers have considered.
One-year fixed terms are still much the most popular term of owner occupier lending, accounting for 39.4% of the owner-occupier total, down from 42.1% in March.
But if short is hot long is not. It is getting colder and colder. As the RBNZ says in its summary of the highlights, the share of owner occupier lending on fixed terms above 18-month fixed terms decreased or held steady – with some at or close to historical lows.
"For example, the share of two-year fixed decreased to 8.6% from 10.2%, and the share of three-year fixed terms decreased to 2.8% from 3.3% - both are at historical lows. The four-year fixed terms held steady and are at a historical low at 0.3%.
There's an interesting point to make at this stage:
The fact that the latest figures highlight mortgages that were drawn down in April of this year means that the decisions on what term to take were all made well before the latest Reserve Bank Official Cash Rate decision and Monetary Policy Statement release on May 22.
That's important to bear in mind because prior to the RBNZ's latest OCR decision the wholesale interest rate markets had been fairly aggressively betting on rate cuts sooner rather than later, with the market pricing in a first OCR cut by October of this year and a fair chance of two cuts by November. Such a scenario would of course see likely significant falls in mortgage interest rates well before Christmas.
But the RBNZ's statements on May 22 were much more 'hawkish' than had been expected, with the central bank pushing back the expected time of a first cut to the OCR (currently on 5.5%) to the second half of next year.
If everything turns out as the RBNZ is currently forecasting then the hoped for mortgage cuts might not happen within the next year - certainly not in a meaningful way, so, maybe the 'go short' strategy might not pay off.
The wholesale interest rate markets ARE still pricing in an OCR cut in November, so the RBNZ's words don't necessarily take away the chance of earlier mortgage cuts. It will though be interesting to see if in the wake of the RBNZ's latest statements there is any change in the mortgage rate fixing strategies of the home buyers.
Separate figures earlier released by the RBNZ that lay out the county's entire mortgage stock and times to the next repricing show that as of April 2024 some 71% of the $262.4 billion of owner-occupier mortgages were either on floating rates or on fixed terms of a year or less. That's up from a comparative figure of just 59.4% as of April 2023 - demonstrating the extent to which homeowners have been 'going short' with their mortgages.
In means that homeowners will be very responsive to cuts in mortgage rates when they come (well, or for that matter, RISES if something untoward happened), with basically nearly three quarters of the owner-occupier mortgages due to be repriced in a year or less.
As said above, however, the RBNZ's dogged determination to get inflation under control, coupled with a desire to not see interest rates come down till it's good and ready, could yet frustrate homeowners.
Some quick details on the borrowing of investors:
The RBNZ says new residential investor mortgage lending rose to $1.48 billion in April 2024 from $1.336 billion in March.
For the investors, one-year fixed terms also continue to be the most popular, making up 45.0% of new lending, down from 45.7% in March-24.
The share of new residential investor lending on six-month fixed terms increased from 16.9% to 18.7% in April.
The share of three-year and four-year fixed terms decreased from 2.2% to 1.6% and from 0.3% to 0.1%, respectively. These figures at are historical lows.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.