

Here are my Top 10 links from around the Internet at 10 past 10 pm (!), brought to you in association with New Zealand Mint for your reading pleasure.
My apologies for lateness today. I had to spend some time at home with the family and we had some Friday afternoon finance company dramas to report.
I welcome your additions and comments below, or please send suggestions for Monday's Top 10 at 10 via email to bernard.hickey@interest.co.nz.
I'll pop any surplus suggestions I get into the comment stream under the Top 10.

1. The death of the McMansion - The WSJ reports that Americans have fallen out of love with the McMansion. HT Gertraud.
Will the same happen here as the Baby boomers look to down-size?
Or is it not such as issue here because so many of the houses built in the last decade are leaky anyway and impossible to sell...
The golden age of McMansions may be coming to an end. These oversized homes -- characterized by sprawling layouts on small lots, and built in cookie-cutter style by big developers -- fueled much of the housing boom. But thanks to rising energy and mortgage costs, shrinking families and a growing number of retirement-age baby boomers set on downsizing, there are signs of an emerging glut.
Interviews with dozens of real-estate agents, sellers, developers and housing economists turn up signs across the country. In an affluent Dallas ZIP Code, where half the houses have four bedrooms or more, home sales fell 31% in the first quarter compared with the previous quarter. But sales rose 23% in a nearby ZIP Code where 7% of houses have that many bedrooms. In Santa Fe, N.M., homes in the 2,000-square-foot range sell within weeks, while larger ones languish for months, says broker Pat French.
Developers market the homes under names such as the Grand Michelangelo, Hemingway and Hibiscus -- while detractors have dubbed them "garage mahals," "faux chateaux" or "tract castles."
Now, some boomers in their late 50s are counting on selling their huge houses to help fund retirement. Yet a number of factors are weighing down demand. With the rise in home heating and cooling costs, McMansions are increasingly expensive to maintain. Nationwide, electricity rates have risen 12% over the past three years, while the price of natural gas for heating has risen 43% in the same period, according to the U.S. Energy Information Administration.
As the nation's 78 million baby boomers, born from 1946 through 1964, become empty-nesters and hit retirement age, many are already selling their trophy homes and trading down to smaller models. There are roughly the same number of people in the next pool of potential buyers, but they're marrying later and often have smaller families.

2. Profits up but employment down - Is the Western model of capitalism that worships quarterly profit growth above all else sustainable? The latest figures from the US employment market raise the question. Companies are boosting their profits by cutting costs and then stopping investment (to further save costs) and because demand is not there. It does not compute.
Henry Ford kick-started the creation of the American middle class and its golden era by paying his workers more so they would buy his cars. America seems to have forgotten this. It disguised the destruction of its middle class by lending them money to keep consuming over the last decade. Now the lending has stopped, so has the consumption.
Here's the Globe and Mail reporting on the latest figures showing America's number of unemployment applications hitting the half million mark last week for the first time since last November.
July marked the third straight month that the private sector hired cautiously. Economists are concerned that the unemployment rate will start rising again because overall economic growth has weakened significantly since the start of the year.
In a healthy economy, jobless claims usually drop below 400,000. But the recent increases in claims provide further evidence that the economy has slowed and could slip back into a recession. Many analysts are worried that economic growth will ebb further in the second half of this year.
After growing at a 3.7 per cent annual rate in the first quarter, the economy's growth slowed to 2.4 per cent in the April-to-June period. Some economists forecast it will drop to as low as 1.5 per cent in the second half of this year.
3. Tier One capital notes - The Basel Committee reckons Tier One capital notes should be written off or converted into equity in the event of a crisis, Bloomberg reports. New Zealand's banks have sold a lot of these in the last three or four years.
The Basel Committee on Banking Supervision is proposing that debt counted as bank capital should be converted to stock or written off in a crisis, forcing bond investors to bear some of the cost of future bailouts.
All regulatory capital instruments sold by banks should be capable of absorbing losses if the company can’t fund itself, the committee said in a consultative paper today. Before taxpayers’ cash is used to rescue a lender, so-called contingent capital should be converted to equity or written off.
The committee, which sets international banking rules, wants to avoid a repeat of the financial crisis when government assistance to failing banks helped holders of some subordinated bonds dodge losses. Banks’ cost of capital may rise as investors demand compensation for the increased risk they won’t be repaid.
“It looks like the banks are going to be paying more for regulatory capital,” said John Raymond, an analyst at credit research firm CreditSights Inc. in London. “They’ll also have to look for a different investor base.”
4. Are bonds the new bubble? - US Treasury bond yields are extraordinarily low, which means their prices are extraordinarily high. Barry Ritholz at The Big Picture compares US Treasuries to the dot com bubble market that started in 1997/98. The chart looks familiar... What would happen if the bubble burst? Everyone's interest rates would rise.
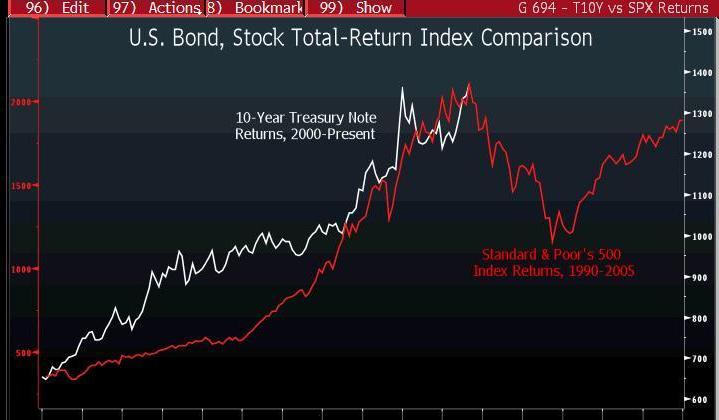
Over the past few months, I have been saying US Treasuries remind me of the dot com stocks circa 1997-98 in three ways:
1) You knew momentum was taking them (much) higher;
2) You knew it was going to end badly;
3) If you were honest, you admitted you had precisely zero idea when the day of reckoning would be.

5. Japan then was better placed than America and UK are now - Adam Posen, a member of the Bank of England's rate setting committee, has a 32 page paper here explaining why America and Britain are actually in a worse position now than Japan was at the start of its long stagnation. He also argues Japan need not necessarily have suffered a long recession.
Here's one of the reasons.
One major problem which Japan did not face during its Great Recession was poor prospects for external demand and the need to reallocate productive resources across export sectors.
The UK, US, and many Euro Area economies do now face this challenge simultaneously, which may limit the pace of, and our share in, the global recovery.
6. What if everyone starts printing? - One problem with trying to run a lower currency is that eventually tries to do it. Ryan Avent at The Economist says that may not be such a bad thing. Sounds like a whole lot of printed money to me, but hey...
Not everyone can push down their exchange rate at once, it's true. But if central banks seek to reduce the negative growth impact of a rising real exchange rate by increasing monetary expansion, then it's possible for everyone to win—the attempt to win the battle over the limited pool of global demand will help reflate domestic economies.
The situation is not unlike that in the Depression. Struggling economies progressively left the Gold Standard to prevent a costly loss of international competitiveness, but while it wasn't possible for every country to benefit from the devaluation associated with departure from gold, the end of the Gold Standard meant a freeing of monetary policy, which allowed economies to reflate and recover.

7. A recession of the banks, by the banks and for the banks - P O'Neil points out at A fistful of euros that some funny things are happening in Ireland because the banks now own everything because they repossessed so many things. The government is reluctant to kill off the banks, which means they are the only ones spending money. This is the problem when you leave zombies to stagger on. Timaru is a lot like Ireland at the moment...
A farmer goes into an embattled tractor dealer and reaches an understanding on the purchase of an expensive tractor. The farmer then goes to his local bank manager to get financing to purchase the tractor; as agriculture is not doing too badly despite the recession, there is some hope. But the bank has an unexpected response: we can’t give you a loan to buy that tractor, but we can finance one very like it — that we recently reposessed. So banks are in the farm machinery business, at the expense of actual farm machinery businesses.
A recreational golf player reports that it’s a good time to play golf in Ireland. Some local courses that had gotten shabby and run-down are finally having some needed working capital put into them, and now they look good. How did this happen? The banks took them over and will do anything to attract a bit of business, even if it means putting in some additional money.
The big picture is that the Irish debt crisis has put the banks into lines of business that they never planned to be in. With the result that significant sectors of the Irish domestic economy are now being run by them. But there is a strange flip side to this situation. There is exactly one sector of the economy that the government has declared off-limits from the process of debt distress, restructuring, and external management — the banking sector. And so it is that unlimited public funds are available to keep solvent what would otherwise be insolvent banks, the €24 billion or so directed to Anglo Irish Bank being the epitome of this problem.
8. 'There is no such thing as a bond bubble' - Pragmatic Capitalist argues there is no such thing as a US Treasury Bond bubble and can never be such a thing because the US Treasury bond market is simply a way to soak up cash already spent by politicians. The flaw I see in this is that at some stage the US government will have issued so much debt that it can't pay the interest. Unless of course interest rates are dropped to zero and stay there for ever... I have a cunning plan Balderick...
What exactly is the U.S. government bond market? In a country with monetary sovereignty in a floating exchange rate system (USA & Japan, for instance) the bond market is really nothing more than a mechanism through which the central bank controls the money supply. It doesn’t actually fund anything as it does in Europe or under a gold standard.
This is best understood by studying the bond auction data in the USA. Despite constant shrieking of a potential lack of buyers in government bonds over the years we continue to see incredibly high demand for US debt. The auctions are always oversubscribed. They never fail. Why is this? Why do the buyers keep coming back for more? The simple answer is because the government puts the buyers there. The auctions are designed not to fail. How is this you ask? The government bond market is merely a monetary tool that the central bank utilizes to control the cost (or supply) of money by controlling the level of reserves in the system. So, when the government auctions bonds they are merely targeting reserves in the system.
This action is mandated by Congress as an accounting tool and so is seen as a source of funding, however, in reality the Central Bank is merely draining reserves that the Treasury already spent into existence – reserves that were deposited at various banks (read this process in greater detail here). Therefore, it’s incorrect to argue that there won’t be buyers of U.S. bonds – with the banks earning 0.25% on their reserves and the government offering anything above that (depending on duration) the trade is a no-brainer for the banks who hold these reserves.
The government is basically offering them free money and the Central Bank keeps control of the money supply in exchange (at least in theory). What is not occurring is some sort of funding mechanism. The Fed could care less if the auctions are 2X, 3X or 4X oversubscribed. They don’t get extra money when this occurs. They don’t get a gold coin that can then be spent. So long as they meet the 1:1 bid to cover the auction is a huge success because they drained their targeted reserves and convinced Congress that we aren’t going bankrupt.
9. The Greek crisis is far from over - Ambrose Evans Pritchard reminds everyone that the Greek crisis is far from over and we face a rocky few months ahead as the scale of the problems in Europe dawn on financial market players returning from their summer holidays.
A report by HSBC said banks had lost 8pc of their entire deposit base in the five months to May. "The Greek market has never, since the first data in 2001, experienced such attrition," said banking analyst Joanna Telioudi.
While some withdrawals point to capital flight by wealthy Greeks, it is clear that households and companies are running down savings to make ends meet. The Athens Chamber of Commerce warned yesterday that its members are in "dire straits", with a majority facing a liquidity threat.
Ian Stannard, a currency strategist at BNP Paribas, said investors have been unsettled by news that Spain is planning to soften its austerity package by renewing €500bn of rail and road projects. "The fear is that if Spain backtracks, then others like Greece are going to follow. This is creeping on to the radar screen," he said.
Mr Stannard said a report on Greece by Spiegel magazine entitled "Entering a Death Spiral" revived worries about political stability, painting a picture of a country nearing popular revolt. It said unemployment had reached 60pc to 70pc in depressed areas.
Willem Buiter, chief economist at Citigroup, said it remains unclear whether eurozone debtors can recover amidst severe fiscal tightening. "Europe's underlying problems have not been resolved. Medium-term worries over sovereign credit quality in periphery countries will probably resurface in coming months," he said.
Chris Pryce, of Fitch Ratings, said Greece is teetering on the edge of junk status but can still claw its way back. He expects the economy to contract by 4.5pc to 5pc this year, worse that official forecasts. This is manageable. The key is whether the pace of decline slows enough next year to make q dent in the deficit, and whether the country will accept yet another round of austerity.
"Everybody is away on holiday. When they get back they will have to face their miserable new world going into the autumn, and then we will see," he said.
10. Totally irrelevant video - Jon Stewart on the corrupt politician with the silly hair.
| The Daily Show With Jon Stewart | Mon - Thurs 11p / 10c | |||
| Law & Order - Time Wasters Unit | ||||
|
||||
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.