

HSBC, which announced in June it was quitting New Zealand retail banking, says it's selling its NZ mortgage portfolio to a NZ subsidiary of Australian non-bank lender Pepper Money.
HSBC says the agreement with Pepper Money, which is listed on the Australian Securities Exchange (ASX), is expected to include about $1.4 billion of mortgages. The deal's expected to go through by late November, subject to approval from the Overseas Investment Office. Pepper Money has had a presence in the NZ mortgage market since 2011 when it acquired GE Capital’s Australian and New Zealand home lending business.
"The sale of the mortgage portfolio to Pepper Money will ensure our customers have continued financial solutions and support. The mortgage portfolio sale is part of the wind-down of HSBC’s wealth and personal banking (WPB) business in New Zealand, which was announced in June 2023. The wind-down of the rest of the WPB business will continue in phases with adjustments made to accommodate the sale of the mortgage portfolio," HSBC says.
"HSBC will continue to operate its wholesale banking business, which includes commercial banking and financial institutions & government, along with its markets & securities services business. Each of these businesses is primarily focused on supporting internationally oriented clients that benefit from the HSBC Group’s unique global network and international financial capabilities."
An HSBC spokeswoman says the value of the deal wasn't being disclosed.
For borrowers on a fixed mortgage interest rate, HSBC says this will remain for the duration of the agreed term. Meanwhile, the wind-down of HSBC's deposit business will continue in phases, it says, with some adjustments made to accommodate the sale of the mortgage portfolio.
"We remain committed to supporting you and will do everything possible to ensure a seamless transition," HSBC says.
A big step for Pepper Money
HSBC, best known for its "premier" service, is an interesting combination with Pepper Money, which provides home loan options for people who don’t meet banks' lending criteria.
Pepper Money doesn't take deposits and is funded by money raised through professional, or institutional, investors from the likes warehouse facilities and securitisation programmes including residential mortgage backed securities (RMBS) and auto asset-backed securities (ABS).
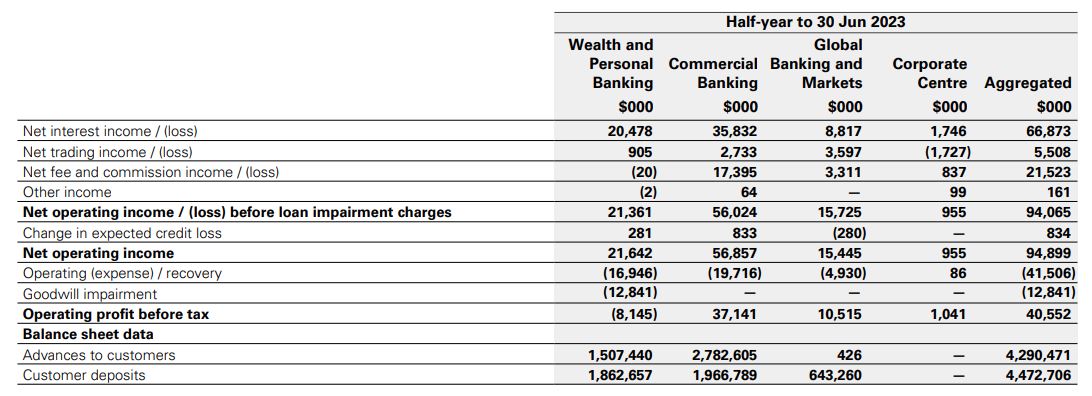
As of June 30, HSBC NZ's wealth and personal banking had home loans of $1.5 billion, and customer deposits of $1.87 billion. HSBC NZ made unaudited half-year profit of $29.2 million. In comparison Pepper Money had NZ assets under management of just A$300 million as of the end of 2022.
Pepper Money says it'll fund the deal in a similar way to how it funds its loan origination activity, and as it has funded other loan book acquisition in the past. That is through a combination of senior and mezzanine funding with Pepper Money contributing the first loss equity.
"The portfolio being acquired is a prime, seasoned and well performing portfolio, and the level of first loss required reflects this," says Pepper Money’s CEO, Mario Rehayem.
"Pepper Money has been servicing mortgages in New Zealand since 2011 when it acquired GE Capital’s Australian and New Zealand home lending business. Since then, Pepper Money has continued to grow its presence in this market with establishment of an end-to-end mortgage platform and nationwide rollout of a full suite of residential home loans (prime, near prime and specialist loans) in 2019."
"Today’s announcement of Pepper Money’s agreement to acquire HSBC’s $1.4 billion mortgage portfolio is a further step in our growth strategy. It is a testament to the ongoing diversification of Pepper Money’s revenue streams. Pepper Money has continually demonstrated our strong capabilities in loan portfolio acquisition and management, over 23+ years, and this acquisition will see the business continue to build scale in New Zealand, a market which we understand well having serviced mortgages and delivered compelling customer service since 2011," Rehayem says.
Quitting with Reserve Bank branch review underway
In June HSBC said it would wind-down its NZ wealth and personal banking business over several years, and was stopping accepting new NZ retail customers with immediate effect. The bank said the decision followed a strategic review and reflected the rapidly evolving commercial, regulatory and technology environment for running a sustainable retail banking business.
HSBC established a branch in NZ in 1987 becoming the first overseas bank branch to be registered here. However, it's not locally incorporated in NZ. The Reserve Bank is reviewing its policy for branches of overseas banks, proposing all branches of overseas banks operating in NZ be restricted to wholesale business with corporates, institutions and other wholesale investors, meaning they couldn't take retail deposits or offer products or services to retail customers.
In a submission to the Reserve Bank last year, HSBC said it supported the current policy saying it; "may need to substantially change strategy in response to such a significant change in the regulatory environment."
Despite this an HSBC NZ spokesman told interest.co.nz in June the decision to exit NZ retail banking wasn't prompted by the Reserve Bank's proposed changes. The group's review explored a variety of options and the ultimate decision wasn't just about NZ with the HSBC Group having been reviewing various businesses around the world, the spokesman said. The review followed pressure from Chinese shareholder Ping An Insurance, which wants HSBC to prioritise growth in Asia.
In its latest disclosure statement HSBC NZ notes the Reserve Bank proposes that branches of overseas banks operating in NZ will be allowed three years from the publication of its final policy settings in the second half of 2023 to be fully compliant.
"The outcome of this consultation could have an impact on the schedule of the exit of the wealth and personal banking business in New Zealand via a wind-down," HSBC NZ says.
"The schedule of the retail wind-down will be reviewed once the Reserve Bank has issued a final decision on this policy."
Separately, HSBC NZ has disclosed an impairment of $12.8 million reducing the value of goodwill related to its wealth and personal banking unit to nil. Winding down the personal banking business has also seen HSBC NZ impair software worth $800,000.
The HSBC-Pepper Money deal does not require Reserve Bank approval.
*The HSBC NZ table below breaks down its operations across its four business units.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.