Seldom have the decisions of central bankers been so consequential. Never have their pronouncements attracted such scrutiny.
The outcome of Tuesday’s meeting of the board of the Reserve Bank of Australia (RBA) was no exception.
An increase of 0.50% in the cash rate was almost universally expected, the fifth such increase in as many months. Hence the widespread surprise when the bank announced a rise of only 0.25% (to 2.60%). At a time when many central bankers around the world are pressing on with oversize rate hikes of 0.5% or more, the RBA slowed down.
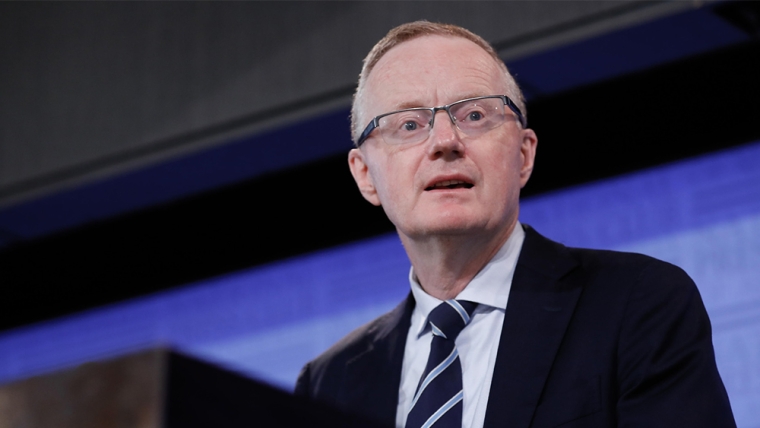
Why? RBA Governor Philip Lowe stated that the 25 basis point rise reflected the fact that “the cash rate has been increased substantially in a short period of time”. The lower-than-expected increase will suffice while the RBA “assesses the outlook for inflation and economic growth in Australia”.
The RBA is clearly nervous about pushing interest rates too high too quickly and tipping the Australian economy into recession. The objective is to return the inflation rate to the target 2-3% band “over time” and “while keeping the economy on an even keel”.
Philip Lowe captured the view of the RBA, the government, and most commentators when he stated that “the path to achieving this balance is a narrow one and it is clouded in uncertainty”.
The economy is sending mixed signals. Inflation is at its highest since the 1990s. The monthly Consumer Price Index (CPI) rose 6.8% in the year to June, 7% to July, and 6.8% to August. High but steady through the last three months. The RBA is forecasting a peak of 7.75% this year falling to 4% over 2023.
House prices, undoubtedly a factor in the RBA’s analysis, are heading in the opposite direction. The rapid rise in interest rates over the last six months has driven house prices down at a pace that, if maintained for much longer, could spell real trouble for the economy. By choosing a 0.25% interest rate hike this week, rather than the expected 0.5%, the RBA may have offered nervous homeowners and would-be first home buyers some hope that rates may not go as high as initially anticipated.
Relative to many similar countries, Australia has a high proportion of borrowers paying floating interest rates. This makes the market more sensitive to interest rate increases. Accordingly, rate increases in Australia may not need to be as great to dampen the economy as is the case elsewhere.
Falling house prices and a drop in Australians’ superannuation balances contributed to a not insignificant 3.3% fall in household wealth in the June quarter. It will have fallen further in the September quarter. The ‘wealth effect’ says that consumers spend more as the value of their assets increases and less when asset values fall.
In the week ended 2 October, the ANZ-Roy Morgen Consumer Confidence Index dropped by 2.3 points to 85.5. According to the report, “driving the decline was less confidence about the Australian economy’s performance”. This large drop will have been partly attributable to one noteworthy event during the survey period, namely the government ending the temporary halving of the fuel excise tax that it previously implemented to help with the cost of living.
However, there is also plenty of good news for Australia. The economy continues to grow, and unemployment remains at a near record low of 3.5%. Job vacancies are at record levels and wages are rising.
Retail spending is proving resilient and the latest monthly lift in spending exceeded expectations. For the moment at least, job security and the high level of savings that consumers built up through the pandemic may be compensating for declining household wealth.
The nation’s finances are also in much better shape than was projected just last year. Two weeks ago, the Treasurer, Jim Chalmers, announced that the budget deficit for the year to 30 June 2022 would be $50 billion less than predicted at budget time. This windfall for the new Treasurer is largely the result of higher-than-expected commodity revenues and lower-than-expected welfare payments.
Thanks to the war in Ukraine sustaining high energy prices, the lucky country’s export boom looks likely to continue for at least another year. According to the September report from the Department of Industry, Science and Resources, Australia’s commodity exports soared from A$308 billion in the June 2021 year to A$421 billion in the June 2022 year and are projected to rise further to $450 billion in the current year.
Iron ore, gas, and coal are the major contributors. A rapidly rising export star is lithium for use in batteries, with exports forecast to grow from $1 billion to $13 billion in just two years.
The export boom has been assisted by a significant fall this year in the value of the Australian dollar against the US dollar. The downside of that fall is upward pressure on inflation. The RBA will be conscious that slowing the pace of its rate hikes relative to the US risks weakening the $A further and exacerbating inflation.
The immediate response on Tuesday afternoon to the RBA’s lower-than-expected 0.25% cash rate increase was a 1.2% jump in the share market, a slump (albeit temporary) in the Australian dollar, and a fall in bond yields.
There was also a rush of commentary on the wisdom or otherwise of the RBA’s move. Some praised the RBA for its cautious approach. Others criticised the approach as risky, saying that it may ultimately result in Australian interest rates having to be higher for longer with adverse results for the economy.
RBA Governor Lowe is no stranger to criticism. In late 2021 he was still predicting that there would be no increase in the RBA cash rate until 2024 at the earliest. That didn’t turn out well.
Let’s hope the Governor’s forecasting skills prove more accurate this time around.
Ross Stitt is a freelance writer with a PhD in political science. He is a New Zealander based in Sydney. His articles are part of our 'Understanding Australia' series.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.