sign up log in
Want to go ad-free? Find out how, here.

Residential auction activity bounces along at winter lows as the market waits for the spring lift

Property / news
Residential auction activity bounces along at winter lows as the market waits for the spring lift
auction today sign

Residential auction activity continues to bounce around winter lows.

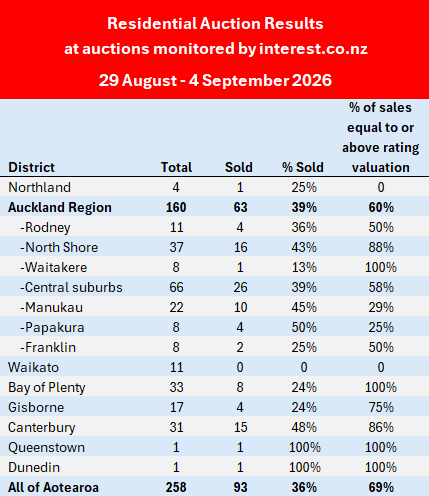
Interest.co.nz monitored the auctions of 258 properties over the week of 29 August to 4 September. That was down from 290 the previous week but up from 214 the week before that.

Auction numbers would need to remain above 300 a week before we could be sure that the usual spring lift was underway, something that occurred in mid-September last year, so it may not be far off.

However, while the number of properties being auctioned goes up and down, the sales rate remains as flat as a pancake, sitting on exactly 36% for the last three weeks.

That suggests a market that's biding its time, as buyers take their time to see how events such as rising interest rates and high stock levels play out.

Details of the individual properties offered at all of the auctions monitored by interest.co.nz, including the selling prices of those that sold, are available on our Residential Auction Results page.

The comment stream on this article is now closed.
 

We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

14 Comments

Wow, this NZ housing market is sick as an old, worm and lice riddled, dog.

Or perhaps, more  existentially dangerious to speculords, as ye olden times influenza wards!

You see, the once wirely and smart Sprucy LL, is now coughing and spluttering in a market that has flipped a complete 180, as a "wise investable"  

All the pre 2021 tailwinds, have vanished without trace. 

Now the lords of the land, are facing bitterly cold roaring 40s gusts, with orifice piercing financial hail, making "holding on" near impossible. 

Yet grip some still do, with white knuckle tenacity.  Heartened by the sweet lovelies written by the now highly discredted Oneroof paid property stooges.  These nefariously selfishly interested Onewoofers, have seemingly talked about "green market shoots" their entire lives...... clown car jockeys, the lot of them!


As spring will inevitably bring back the 10s of thousands of stale, previous years attempts at sale, meeting the market to just liquidate bad investment calls is about to happen enmasse.

Then at the same time, many thousands of nice oldies are still rsttling around their 1960s to 1980s unmaintained homes, Probably 2 to 4 years past due, when they should have moved to the cash gouging corporate overlords, at the Rymans care home.  

Sorry youngins, the leftovers, when they depart, will be exhausted or a very skinny cash bag.


My my, we are about to see this sick housing markets influenza ward, morph into the logical next stage of capitulation and the mortuary chillers.....

Up
3

The Auckland Property Man

He bought his first house in Onehunga
With a deposit from the bank
The agent said, “You can't go wrong, mate”
And the auctioneer said, “Thanks”

He borrowed against the equity
Then borrowed some more
Bought a villa out in Mt Roskill
And a townhouse by the shore

He had a spreadsheet on his laptop
With the numbers looking grand
Every column said “capital gain”
Every row said “rising land”

He's the Auckland property man

Buy it high, sell if you can

Mortgage up, rent it out

“Capital gain!” — that's what he's about!

Auckland property man

Got a mortgage in each hand

Prices rise — that's the plan

Till the bloody bank says, “Pay, my man!”

He bought a place in Henderson
Said, “This one's got potential”
Another one in Papatoetoe
“It's practically essential”

He called himself an investor
But his mates called him a landlord
He'd talk about his passive income
While fixing up the bathroom floor

Then the interest rates started climbing
And the rent began to lag
He looked at his portfolio
And suddenly looked sad

He said, “It's just a temporary correction
The market's coming back”
Then quietly checked the listings
For a buyer who'd bite back

He's the Auckland property man

Buy it high, sell if you can

Mortgage up, rent it out

“Capital gain!” — that's what he's about!

Down on the North Shore
There's a bloke who owns a few
He bought them back in twenty-ten
When nobody thought he'd do

Now he drives a European
And he talks about his wealth
But every time the bank calls up
He suddenly checks his health

There's another down in Howick
Who bought a block of four
Said, “I'll hold them for my children”
Then bought himself four more

But the auction rooms are quieter
And the buyers aren't as keen
The house that would've sold for millions
Can't get anybody seen

The listings keep on growing
The offers keep falling through
And every morning's headline says
“It's worse than yesterday, mate.”

HEY!

HEY, HEY!

They know every suburb's median
Every yield and every rate
They know the auctioneer by first name
And they're always ten minutes late

They'll tell you about depreciation
They'll tell you about the tax
They'll tell you how they “built their wealth”
But never mention what they owe the bank

And now the market's falling
And it's looking worse each day
The spreadsheet isn't smiling
And the buyers walked away

The agent says, “Be patient”
The banker says, “We'll talk”
And the property man keeps staring
At the value of his block

He's the Auckland property man

Buy it high, sell if you can

Mortgage up, rent it out

“Capital gain!” — that's what he's about!

Auckland property man

Got a mortgage in each hand

Prices rise — that's the plan

But the bloody market's falling every day.

And tomorrow it'll be lower
And the day after that
He's still telling all his mates
“It's just a little pullback.”

But the signs are on the windows
And the auction rooms are bare
And every house in Auckland
Seems to be for sale somewhere.

Auckland property man...

Got a mortgage in each hand...

He bought the dream.
He bought the land.

Now he's hoping someone else
Will buy it off his hands.

Up
8

Anyone who bought a city dwelling 20 years ago is going to make money.  He should have sold in la la land of 2021, as would have made more from the stupid buying with 2% loans. Perhaps this should be called the suckers loans period. 

The real point is that was the past. This is today, and we all think/plot about near and medium term future.

Team ponzi seems to think that will repeat again and again. Some, me included, disagree.

Thats all folks.

Up
7

Anyone who bought a city dwelling 20 years ago is going to make money.

Those who really made the moolah were the banks. And it was so easy. The loan was created out of thin air - no money was transferred from anywhere. People think that the bank would have taken from a pool of pre-existing money from the aggregate of saver’s deposits, its own cash vault, or its central-bank reserve account and moved it to the borrower. 

But no, the bank made two matching accounting entries: a new loan asset and a new deposit liability in the borrower’s account. Just like that. No other customer’s deposit fell by an equivalent of the mortgage at that moment. What is newly created is bank-deposit money: an electronic claim on the bank, usable for payments. At the same time, the borrower has an equal-sized debt. The bank’s net worth does not mechanically rise by the principal amount when it enters these two equal entries.

But the bank has the privilege of charging for its ability to create something out of nothing. 

This is just the initial booking of a loan, not necessarily to the later payment and settlement process.

If you borrow $100,000,000 and pay the house seller who banks with the same bank, the bank can normally just reduce your deposit and increase the seller’s deposit. It is an internal book-entry transfer.

If you pay someone whose account is at a different bank, the two banks must settle the net payment position - typically using central-bank reserve balances or other interbank arrangements. So reserves can matter materially after lending, especially for payments, liquidity management, and regulatory requirements, even if the bank did not first “take reserves” and hand them to you.

Up
2

It really does look like a global scam. 

Up
0

Not necessarily a scam. That's how Anglosphere banks work. But many people don't really understand that house prices are essentially a product of broad money growth. 

Problem as I see it is the extent to which broad money growth can outstrip income growth of the majority. The ruling elite don't want to talk about it as I suspect they have no idea how to tackle it.  

Up
3

its likely the next wave of productivity will be enabled by AI and at the detriment of most middle class


Up
1

What to do.... history shows that eventually something happens. The French peasant class found a way to deal with their inequality as did Russia, China and others. Didn't change much in the long run other than a different rulling class, but the original group not caring about inequality had a very bad and shortened time.

Up
2

In NZ the limit of any revolution may well be voting opportunity, we don't want change.

Germans do -

https://www.afr.com/world/europe/germany-s-far-right-set-for-power-for-first-time-since-the-nazis-20260903-p60ubx

Segregating refugee children

AfD performs strongest in the former communist-ruled East Germany, Despite the fall of the Berlin Wall almost four decades ago, many of the towns and cities languish behind the more prosperous west on economic and social measures.

Unemployment in Saxony-Anhalt is 8.2 per cent, higher than the national average of 6.5 per cent. The median wage is about €4000 ($6500) lower than the German average too. Tapping into this sense of being left behind has been one of the key drivers of the AfD’s gains.

A healthy dose of “anti-wokeism” also exists too, such as banning gay pride flags and opposing transgender rights, despite co-leader Alice Weidel being a married lesbian.

Arguably the biggest factor propelling the AfD is immigration, in particular resisting the “Islamification” of Germany. Former chancellor Angela Merkel’s decision to let in more than a million refugees fleeing Middle East war a decade ago continues to fuel the AfD’s most potent line of attack.

The party’s policies include segregating refugee children from German kids in schools; sealing the European Union’s external borders; mass deportation of foreigners without legal status; and stripping foreigners convicted of crimes of their residency permits.

Up
0

That article seems quite positive. I'm wondering, though, if cheap terraced housing will become the new apartments. The take away was that cheaper housing brings more choice and buyers are choosing standalone houses if they can afford them.

Up
0

Bishop said since the scheme’s inception it had helped more than 33,000 households into home ownership, with Kāinga Ora approving more than 7700 new First Home Loan applications between July 1, 2025 and April 30, 2026.

so 33,000 in on 5-10% equity and cotality estimate only 3600 low equity lenders are in negative equity, I call complete BS on that.


Up
1

Yes utter market bedeviling lies.  No way this number is right.  Would not put it past the banks to be massaging their bad or underwater loan books.

20,000 + would be a more legit underwater loan total, rising every day for the next 2 or 3 years IMHO.

Up
0